F5 Beats On An AI-Fueled Product Surge, But FY27 Becomes An Investment Year As Margins And Cash Flow Compress
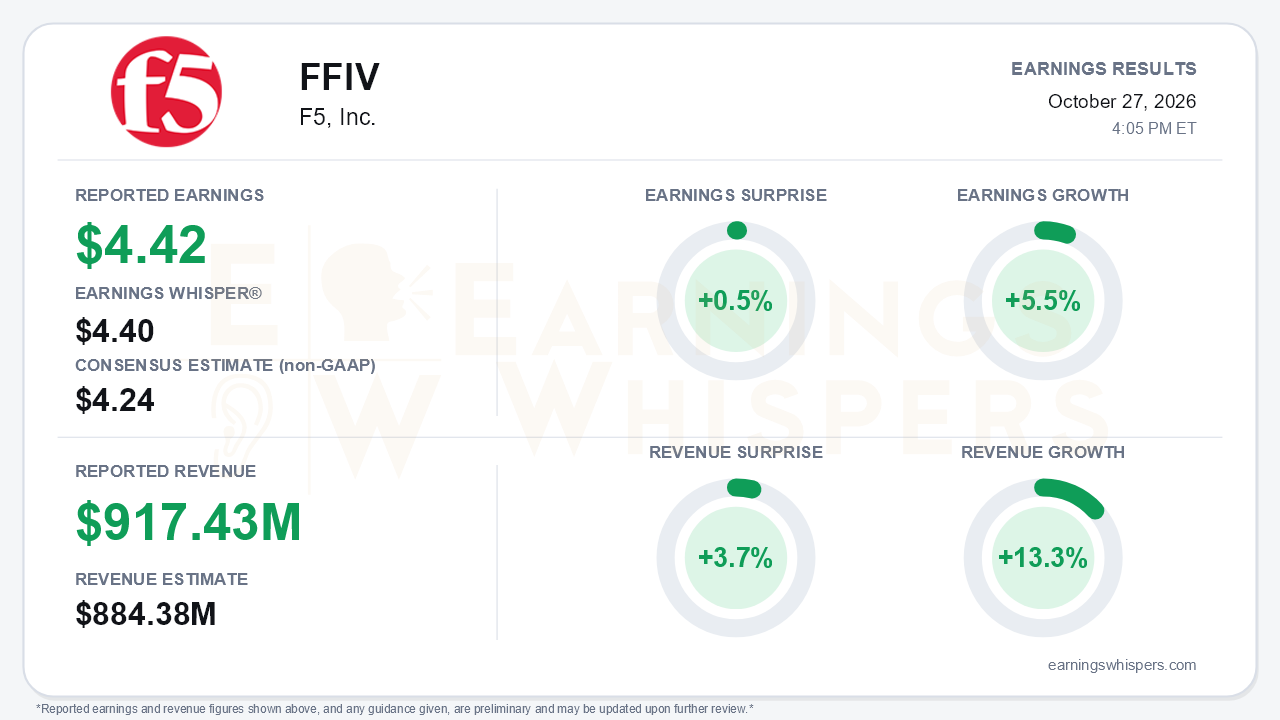
F5 closed fiscal 2026 with its strongest top-line quarter in years, but the report also marked a turn in the earnings story. Fiscal fourth-quarter non-GAAP earnings of $4.42 per share edged past the $4.40 Earnings Whisper number, a 0.5% surprise, and cleared the $4.24 consensus. Revenue of $917.43 million beat the $884.38 million consensus by 3.7% and grew 13.3% year over year. The gap between those growth rates is the central tension. Revenue grew 13.3%, but earnings grew only 5.5%. F5 is now spending its top-line momentum rather than banking it, and the fiscal 2027 outlook makes that choice explicit.
The revenue mix was impressive. Product revenue rose 23% to $510 million, up from 19% growth in the third quarter. It was the ninth straight quarter of double-digit product growth. Software reaccelerated sharply to 19% growth from 7% in Q3, while systems grew 29% on the iSeries refresh. Services remained a laggard at 3% growth. Below gross profit, however, the quality of the beat deserves scrutiny. Non-GAAP operating expenses of $462 million overshot the company's $430-442 million guide. Non-GAAP operating margin fell to 33.7%, compared with 35.0% in Q3, 37.0% a year earlier, and 38.2% in the first quarter. On a GAAP basis, diluted EPS slipped to $3.23 from $3.26 despite the double-digit revenue gain. A higher tax provision and rising acquisition-related charges contributed to that decline.
The conference call preserved a credible growth story, and the AI narrative is becoming tangible. Direct AI use-case bookings topped $100 million in fiscal 2026, up nearly 300%, compared with roughly $50 million cited at midyear. Active direct AI customers quadrupled to more than 200. The AI-powered WAF reached more than 300 customers within about six months of launch, with over 75% running in blocking mode. Notable wins included:
- an AI guardrails deal covering up to 500 hosted models;
- sovereign AI wins with Indosat Ooredoo Hutchison and Telenor;
- an eight-figure financial-institution consolidation that displaced four incumbent vendors.
Management described the quarter as one of its strongest ADC competitive-takeout periods in years. It also said SaaS ARR of $211 million, up 14%, is now a growth leg after the legacy transition was completed.
Guidance is where the setup gets more complicated than the surprise implies. F5 guided fiscal 2027 revenue growth to 8% to 9%, building on a fiscal 2026 base that ended near 11% after guidance was raised every quarter. The company expects double-digit software growth. Non-GAAP EPS guidance of $18.00 to $18.30 implies only modest growth from $17.49. First-quarter EPS guidance of $4.25 to $4.37 sits below the $4.45 earned a year ago. Several factors drive that outlook:
- Gross margin is guided to 80.5% to 82.5%, a step down from about 84% in fiscal 2026. That range is still 50 basis points above the earlier 80% to 82% framework.
- Memory cost inflation is expected to persist.
- AI security specialist headcount and marketing spend are both slated to more than double.
- Systems growth is expected to slow in the second half as the refresh fades.
Cash flow is the other pressure point. Q4 free cash flow fell to $91 million from $281 million in Q3 and a record $348 million in Q2. Inventory climbed to $262 million from $77 million a year earlier, and capital spending more than doubled for the year. Management characterized the inventory and supplier-prepayment builds as deliberate. It also warned that first-quarter operating cash flow will be weighed down further by inventory and bonus payouts. The new $1.5 billion buyback authorization, which adds to $322 million remaining, offers some per-share cushion.
The market had already priced in a good deal of optimism. Shares rose 17.2% from the opening after the July report to $461.60 heading into the release. That left the stock 28% above its 200-day moving average, about 4.5% below the 52-week high of $483.30 set on October 12, and near the top of its inter-earnings range. Investor sentiment remained positive but cooled noticeably, falling from 0.70 to 0.57. That suggests expectations were already tempering before the print. Price, momentum, and AVWAP trend readings remain positive, while sequential growth is neutral. That mix fits a business with strong demand but flattening near-term profitability.
The bottom line is that F5 delivered what bulls wanted on revenue: accelerating product and software growth, real AI traction, and guidance above estimates on a higher base. But bears have legitimate ammunition. Operating margin has compressed for three straight quarters, opex overshot guidance, free cash flow collapsed in Q4, and first-quarter EPS is guided down year over year. With the stock trading near its highs, the debate now centers on whether fiscal 2027's heavy investment produces durable AI security revenue fast enough to restore operating leverage.
Read our earnings preview for F5, Inc.: https://www.earningswhispers.com/article/FFIV/20761
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 24 min | |
| 1 hour | |
| 3 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-15 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Oct-01 |
