Grand Canyon Education's Fall Enrollment Test Arrives With The Street Already Above Guidance
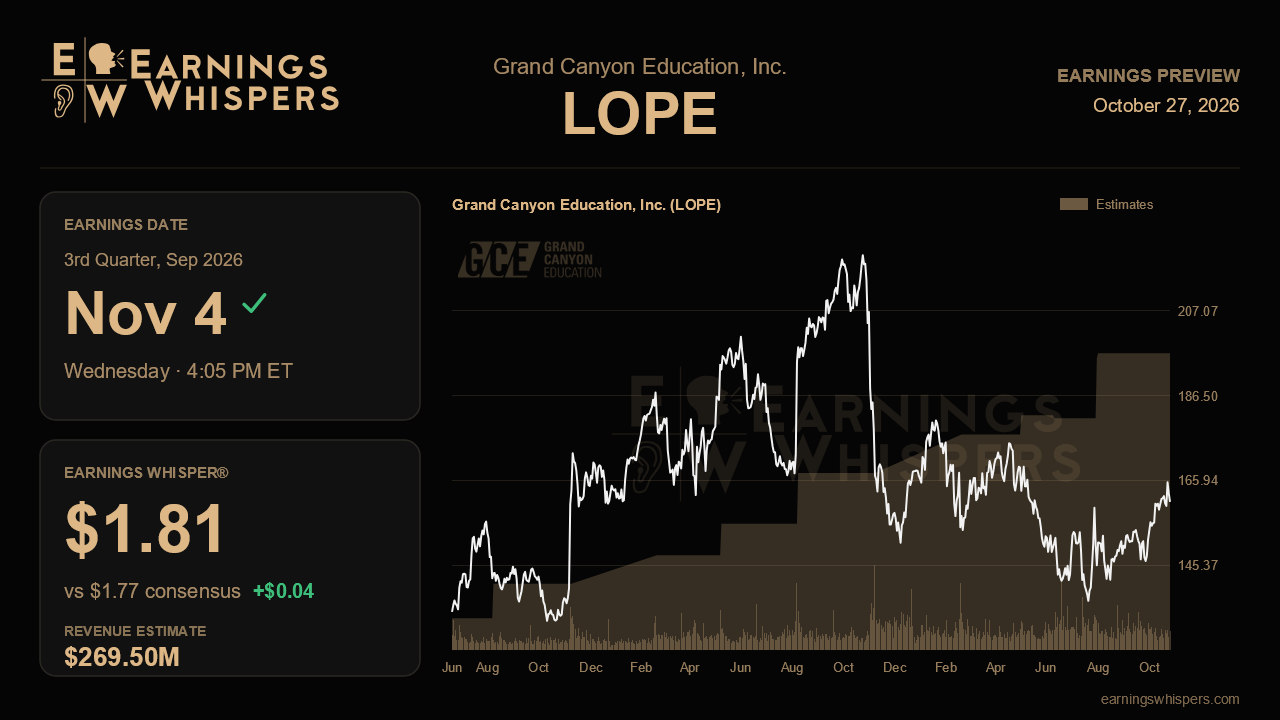
Grand Canyon Education heads into its third-quarter report with a peculiar expectations gap. Management guided to earnings of $1.68 to $1.72 per share, yet consensus sits at $1.77 and the Earnings Whisper at $1.81. Analysts are betting the company will once again outrun its own forecast, as it did last quarter when adjusted EPS of $1.81 topped estimates by 14 cents. That habit of conservative guidance followed by a clean beat has become central to the bull case. This quarter tests whether it still holds while the underlying growth story shifts from online momentum toward newer, longer-dated campus catalysts.
The headline numbers point to a flat quarter rather than a growth one. Consensus revenue of $269.5 million sits at the midpoint of management's $268.5 million to $270.5 million range and implies growth of about 3.2%. Expected EPS is essentially unchanged from the year-ago $1.78. Some of that softness is mechanical. The amended master services agreement with Grand Canyon University cuts roughly $4 million from third-quarter revenue and about $20 million a year going forward. Management said the operating-income hit is under $1 million a quarter because an offsetting reimbursement payment disappears. If that holds, a smaller revenue base should flatter margins, so a reported operating margin that fails to expand would be a warning sign. The full-year outlook frames the stakes. Management narrowed 2026 EPS guidance to $9.93 to $10.07 from $9.69 to $10.26, nudging the midpoint up even as it trimmed the revenue range. Consensus of $10.04 sits toward the upper part of that band, leaving limited room for slippage in the fourth quarter.
Operationally, this is the fall start quarter, which makes it the first real scorecard for the catalysts management promoted last time. Online new-start growth slowed to low single digits in the second quarter after high single digits in the first, and total online enrollment growth eased to about 7.8%. A further slide toward flat starts would suggest the AI-driven decline in web leads is hurting more than management's employer-partnership channel, which sources 30% to 40% of starts, can offset. Stabilization or a modest reacceleration, helped by easier comparisons, would support the view that the slowdown was about tough comps rather than weakening demand. On the ground campus, investors should look for evidence that the Honors College reached its 3,500 target, that the new College of Construction and Industrial Technologies drew a meaningful first class toward its goal of thousands of students, and that overall traditional enrollment held near 25,000. The hybrid business, which grew 18.5% excluding teachouts last quarter, faces capacity limits at 14 sites, so any sign of decelerating fall enrollment there would matter.
Capital allocation is another swing factor. Management was finalizing a credit line to fund faster buybacks, and a lower share count could help EPS clear the Street's above-guidance bar even if interest income keeps falling as cash balances shrink.
The market has already rewarded the post-call story. Shares are up 11.1% since the last report, beating the S&P 500 by more than 8 percentage points, as the 15-year contract removed a long-standing overhang. Yet sentiment has cooled, with bearish readings rising to 50% from about 40% a quarter ago. At $160.71, the stock trades just above its 200-day moving average and in the upper half of its post-earnings range, roughly 4% below the $167.76 high.
Ultimately, the report hinges on whether fall enrollment shows the new colleges and Honors College expansion beginning to offset decelerating online starts. A beat paired with stable online trends would keep the margin-expansion narrative intact. A guidance-level print alongside softer starts would leave the stock's recent gains looking premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-16 | |
| Oct-06 | |
| Aug-06 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jun-24 | |
| May-20 | |
| May-08 | |
| May-01 | |
| Apr-30 | |
| Apr-30 | |
| Apr-01 | |
| Mar-09 |
