Rogers Posts Multi-Year Margin High And 17% EPS Beat, But Supply-Limited Sales Leave Investors Watching For Growth Proof
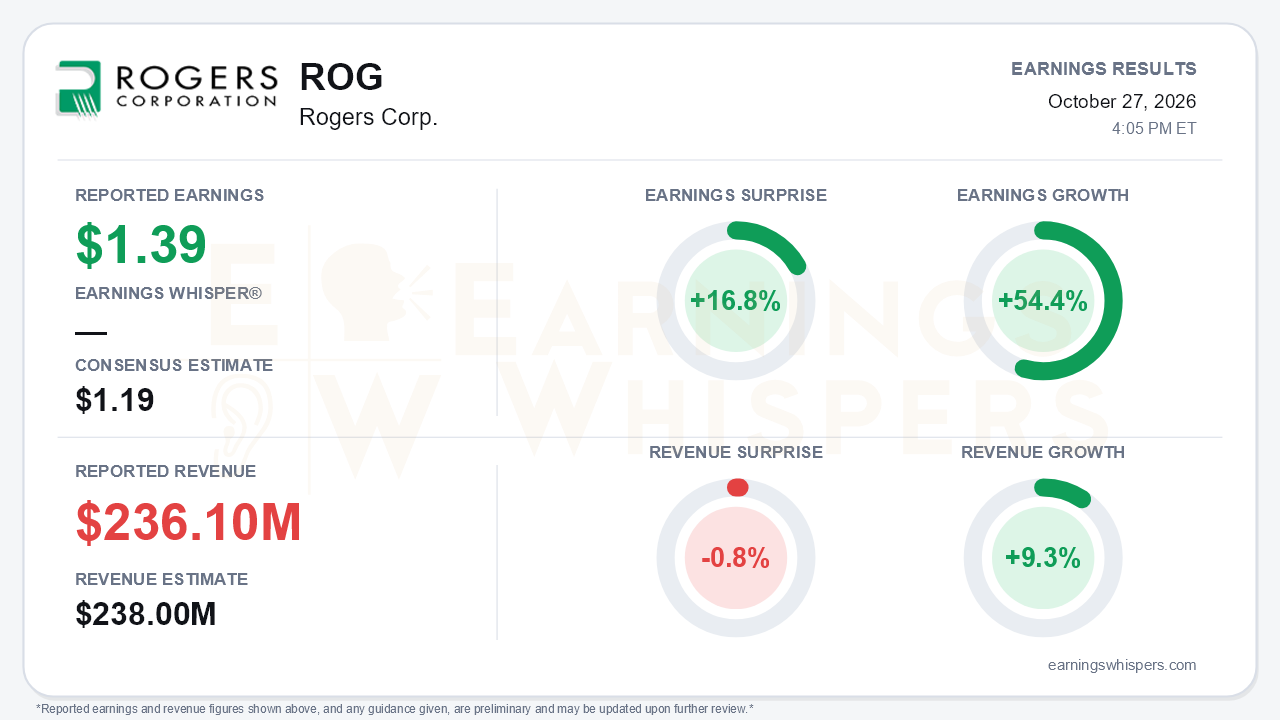
Rogers Corp. (NYSE: ROG) delivered its most profitable quarter in years, and margins drove the result. Adjusted earnings of $1.39 per share beat the $1.19 consensus by 16.8% and grew 54.4% year over year. They also cleared management's own $1.10-$1.30 guidance range, a sharp contrast with the second quarter, when adjusted EPS of $0.92 landed below the midpoint. Revenue of $236.1 million rose 9.3% but missed the $238.0 million consensus by 0.8%. That is the central tension in the quarter. Rogers is extracting far more profit from each dollar of sales, but supply constraints kept the top line from fully reflecting the demand management described.
The quality of the beat holds up well. Adjusted EBITDA reached $47.7 million, a 20.2% margin, up from 17.3% in Q2, 16% in Q1 and roughly 17% in both the year-ago quarter and Q4 2025. Gross margin expanded to 34.2% from 32.5% sequentially and 33.5% a year ago. GAAP results improved even more dramatically. Diluted EPS rose to $1.26 from $0.48, as restructuring and impairment charges fell to $1.0 million from $7.1 million. The gap between GAAP and adjusted earnings is now narrow, suggesting the restructuring era is largely behind the company. Management said the $45 million cost program is fully achieved exiting 2026. Cash generation reinforced the picture:
- **Free cash flow:** nearly doubled sequentially to $35.4 million.
- **Liquidity:** cash and short-term investments rose to $236.4 million.
- **Buybacks:** stepped up to $9.3 million from $3 million in Q2 and nothing in Q1.
Two caveats temper the margin story. Currency added $2.4 million to sales, and equity compensation, which is excluded from adjusted EBITDA, rose to $3.0 million from $0.8 million a year ago.
The revenue trajectory is improving. Year-over-year growth accelerated from 5% in Q1 to 6.9% in Q2 and 9.3% in Q3, with all four end markets growing. Electronics and communications and automotive led the gains. The CEO said organic growth is tracking near 9%, well ahead of the roughly 5% framework laid out at the September 30 Investor Day. He also said design wins are ahead of schedule, customer engagement is intensifying and there is no macro slowdown. Beneath that optimism, the mix is shifting:
- **Smartphones:** a driver in the first half, but sales were lower in Q3.
- **Industrial:** growth slowed to "slight," after double digits in Q1 and high single digits in Q2.
- **Costs:** higher silver and copper prices are offsetting operational savings, and pricing actions remain under evaluation.
- **China ceramics:** the facility ramp is still adding year-over-year cost.
The forward story now centers on growth and capital deployment rather than cost cutting. Management reaffirmed its target of about $100 million in high-growth adjacency revenue by 2028 and said it aims to beat the roughly $450 million goal for 2030. Recent product milestones include:
- design wins in drone-detection laminates, EV battery-pack elastomers and ceramic AMB substrates for multiple EV models at a global OEM;
- wins in data-center server-tray silicones;
- thermal runaway protection entering customer sampling.
M&A language has firmed noticeably, moving to one or possibly two actionable deals expected within about two quarters. Fourth-quarter guidance is more restrained. Management expects revenue of $215-$225 million, down sequentially on seasonality but up about 9% year over year. It guided adjusted EPS to $0.90-$1.10, against $0.89 a year ago, and gross margin to 32.5%-33.5%. That outlook is essentially in line with expectations. It also embeds a tax headwind and rising operating expenses to fund growth, so the Q3 margin peak is not expected to repeat immediately.
The market setup is more complicated than the surprise implies. Shares surged to an inter-earnings high of $165.94 on Investor Day, then surrendered most of that move. Heading into the report, the stock was 23% below that peak at $127.72, just 0.9% above its 200-day moving average and only 6.4% above the open following the July report. Investor sentiment cooled over the same period, slipping from modestly positive (0.11) to essentially neutral. Expectations had been substantially reset after the Investor Day enthusiasm faded. The Earnings Whispers trend signals are mixed, with momentum positive while sequential growth and AVWAP remain negative.
The bottom line is that Rogers delivered a high-quality quarter on margins, cash flow and growth acceleration, and the narrative has credibly shifted from restructuring to expansion. Bears still have legitimate ammunition:
- revenue fell short because of supply push-outs;
- commodity costs are eating into savings;
- smartphone and industrial demand are softening;
- the Q4 guide steps down sequentially and is merely in line.
With sentiment neutral and the stock back near its 200-day average, the next leg depends on whether supply constraints ease and announced design wins convert into revenue, not on further margin surprises.
Read our earnings preview for Rogers Corp.: https://www.earningswhispers.com/article/ROG/20792
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-13 | |
| Sep-30 | |
| Sep-30 | |
| Sep-30 | |
| Sep-09 | |
| Aug-12 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-16 | |
| Jul-14 | |
| May-19 | |
| May-07 |
