NXP's Thin Q3 Beat Undersells A Quarter Of Rising Margins, Surging Cash Flow And A Firmer 2027 Framework, But Q4 Growth Slows To 2% Sequentially
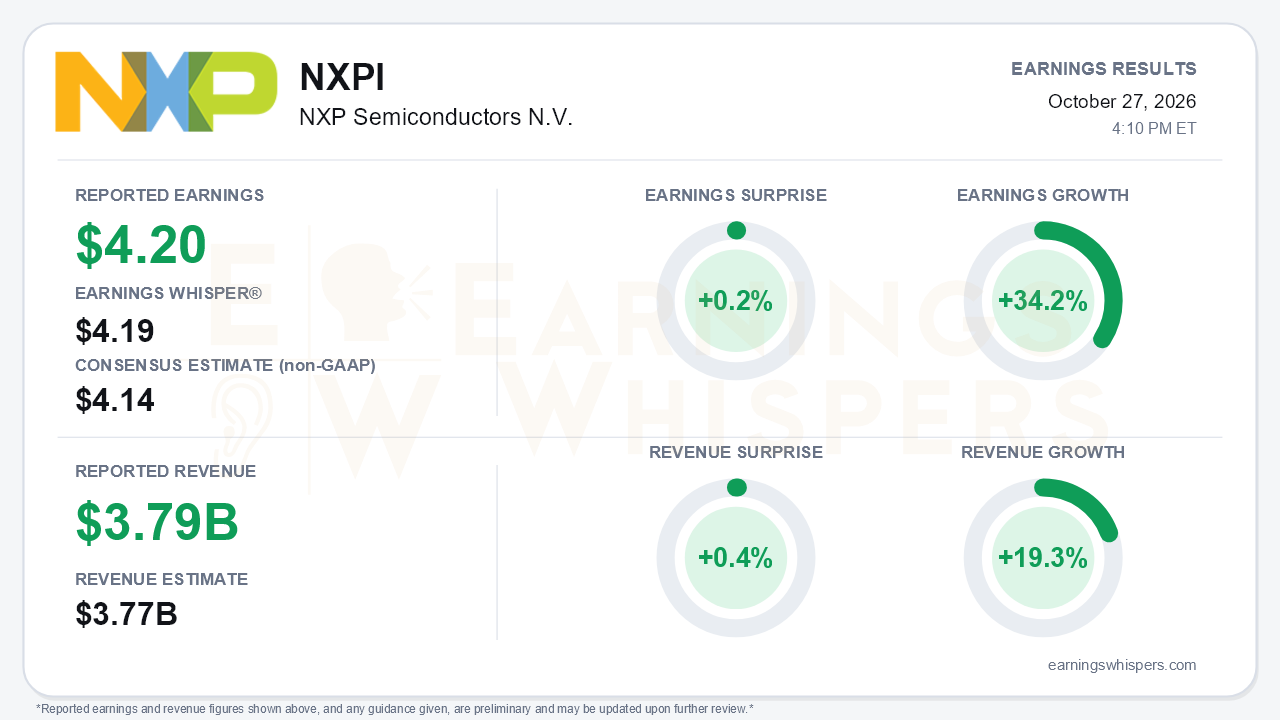
NXP Semiconductors delivered a beat that looks marginal on paper and substantial underneath. Third-quarter non-GAAP EPS of $4.20 topped the $4.14 consensus and edged past the $4.19 Earnings Whisper, a 0.2% surprise. Revenue of $3.786 billion beat the $3.77 billion consensus by 0.4%. The growth profile matters more than the size of the surprise. Earnings grew 34.2% year over year on 19.3% revenue growth, and GAAP diluted EPS rose 40% to $3.48. That is meaningful operating leverage. The central tension is that a quarter showing clear improvement in margins, cash generation and pricing was paired with a fourth-quarter outlook the company characterizes as in line and that implies slower growth.
The quality of the quarter is strong. Non-GAAP gross margin reached 58.6%, up from 58.0% in Q2 and 57.1% in Q1. Non-GAAP operating margin climbed to 37.1% from 35.1% and 33.1% over the same two quarters. Free cash flow was the standout at $1.21 billion, or 31.9% of revenue, compared with $791 million in Q2 and just $509 million a year ago. Trailing free cash flow rose to $3.5 billion, or 25% of revenue. Part of the cash jump came from a $196 million swing in payables and other liabilities, so the run rate deserves some scrutiny. Even so, the cash conversion cycle shortened to 116 days from 134 a year ago, and net leverage fell to 1.3x. One item bears watching: channel inventory held at 11 weeks, above the 9 weeks of a year ago.
The segment mix shows where the momentum is. Automotive topped $2 billion for the first time, rising 13% reported and 17% excluding the divested sensors business. Industrial & IoT jumped 39% to $802 million, and management said the industrial portion grew nearly 50%. Communications infrastructure surged 54% to $503 million, driven by data center demand. Mobile fell 4% and is the clear laggard. Demand signals on the call were unusually firm:
- book-to-bill well above 1 across all markets;
- backlog extending into 2027;
- 80% of the portfolio carrying lead times above 16 weeks, versus 25% a year ago;
- 2026 pricing now neutral rather than the low-single-digit decline assumed at the start of the year.
Utilization has risen from the high 70s to the mid 80s.
Management also put harder numbers on the forward story. NXP now targets double-digit revenue growth in 2027, a 60% gross margin during 2027 and above 60% in 2028. Data center revenue is expected to exceed $500 million in 2026 and reach about $1 billion by 2028. Software-defined vehicle revenue is running above $1.5 billion annualized against a $2 billion 2027 target. New design wins include the RVtech Volkswagen-Rivian joint venture standardizing on S32K5 and a first humanoid robotics win. A new $5 billion repurchase authorization brings total capacity to roughly $6.3 billion, with accelerated buybacks planned from Q4. That is notable given that Q3 capital returns consumed only 29.8% of free cash flow.
Bears still have legitimate ammunition. The Q4 guide calls for $3.85 billion at the midpoint, just 2% sequential growth after two quarters of 7-8%. Year-over-year growth slows to 15%, and guided EPS of $4.36 implies about 30% growth, both below Q3's pace. Management describes the outlook as above seasonal, but the deceleration is real. Costs are also stepping up:
- Q4 operating expenses rise to $830 million;
- first-half 2027 opex is expected to run about 23% of revenue on new tape-outs;
- capex climbs toward 5% of revenue from 2-3%;
- joint-venture losses rise to roughly $80 million in 2027.
Tight back-end capacity, expected front-end tightness, foundry price increases and a mid-teens mobile decline add friction. Some analysts also viewed the $1 billion data center target as slower than peers.
The market setup is more complicated than the fundamentals imply. Shares closed at $245.83 before the report, down 2.8% from the open following the July release. They sat essentially on the 200-day moving average and 4.5% below the inter-earnings high, which was set the day after that report. The stock had recovered 13.5% from its September 16 low. Investor sentiment improved from roughly neutral to modestly positive, which suggests expectations firmed without becoming crowded. Most Earnings Whispers trend readings are positive, though the price trend remains negative. Operating improvement has so far outpaced the stock's progress.
The bottom line is that NXP's small headline surprise understates a quarter of expanding margins, sharply higher free cash flow, better pricing and a more concrete 2027 margin target. The debate now centers on whether a softer Q4 cadence, rising investment spending and supply tightness slow that progress before the 60% gross-margin framework and buyback can lift a stock still stuck near its 200-day average.
Read our earnings preview for NXP Semiconductors N.V.: https://www.earningswhispers.com/article/NXPI/20781
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 36 min | |
| 1 hour | |
| 2 hours |
NXP Semiconductors Profit Jumps on Automotive, Industrial Growth
NXPI NXPI -7.69% AH
The Wall Street Journal
|
| 2 hours | |
| Oct-26 | |
| Oct-26 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Sep-30 |
