OrthoPediatrics Accelerates To 19% Growth And Raises Guidance Again, But The Flat EBITDA Outlook Keeps Margin Leverage In Question
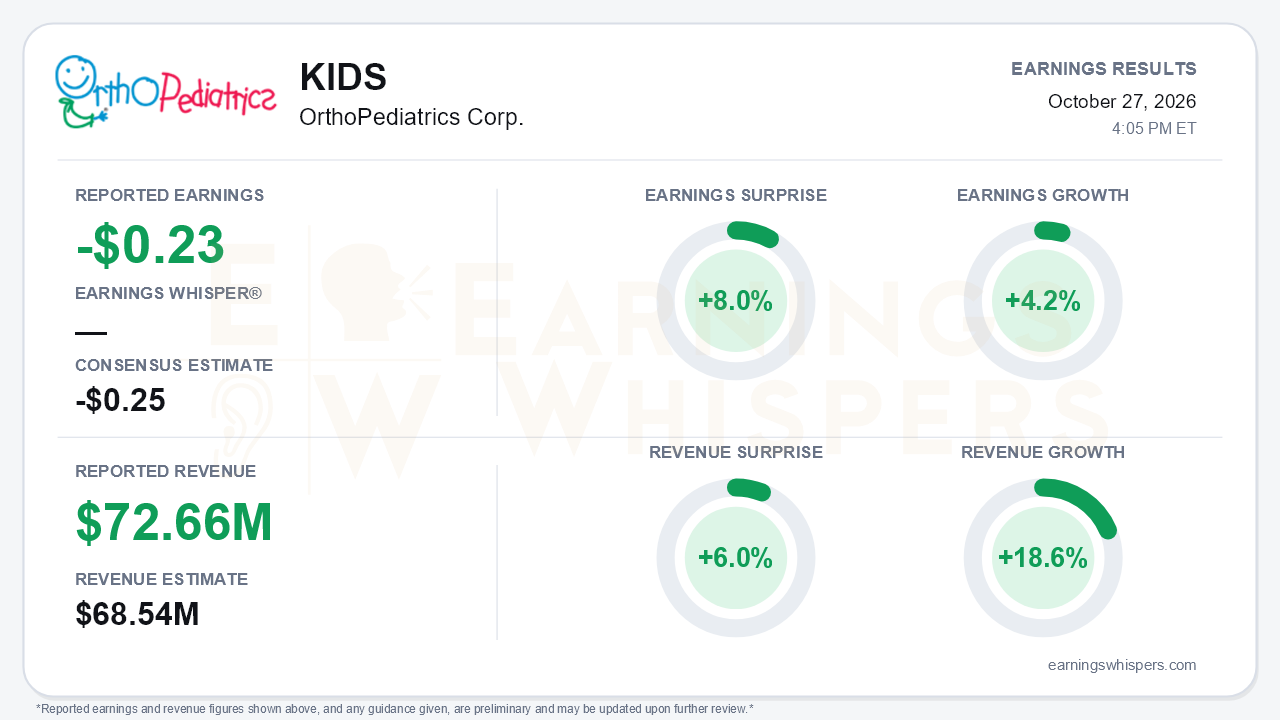
OrthoPediatrics (NASDAQ: KIDS) delivered its strongest top-line quarter of the year. The adjusted loss of $0.23 per share beat the -$0.25 consensus by 8.0%, and record revenue of $72.66 million topped the $68.54 million estimate by 6.0%. Revenue grew 18.6% year over year, extending a clear acceleration from 13% in the first quarter and 15% in the second. Management also raised full-year revenue guidance for the third straight time, to $270 million to $273 million. That range implies 14% to 16% growth, against the 11% to 13% the company outlined at the start of the year. The central tension is that the extra revenue is not yet moving profitability expectations. Adjusted earnings improved only 4.2% from a year ago, and the roughly $25 million adjusted EBITDA target was left unchanged for a fourth consecutive call.
The quality of the beat deserves scrutiny. On a GAAP basis, the net loss halved to $0.25 per share from $0.50. Much of that improvement came from items that did not recur. The year-ago quarter carried $2.3 million of restructuring and a $2.3 million impairment, while this quarter's impairment on the ApiFix and MedTech trademarks was only $0.6 million. This quarter also benefited from an $0.8 million non-cash gain on contingent consideration. The adjusted figures tell a more modest story:
- The adjusted loss narrowed by only a penny, from $0.24.
- Year-to-date adjusted loss of $0.90 is wider than last year's $0.74.
- Gross margin held at 74%, but sales and marketing jumped 24% to about 31.5% of sales.
- Net interest expense rose to $2.6 million from $1.8 million.
- Adjusted EBITDA reached a record $6.9 million but grew more slowly than revenue, leaving the margin near 10%, essentially flat with the second quarter.
Management attributed roughly $0.7 million of the selling-expense spike to distributor quota kickers and characterized it as a timing anomaly.
Beneath the headline, demand looks broad-based:
- Trauma & Deformity grew 19% to $52.6 million, led by cannulated screws, PNP Femur, PediPlates and the new 3P Hip.
- Scoliosis swung from a 9% decline in the second quarter to 18% growth, reaching $19.2 million on VerteGlide and Response.
- International grew 18% despite continued restrictions on set sales in Brazil and Latin America.
- The OPSB clinic strategy kept growing above 20%, with more than 60 clinics now open versus roughly 45 last quarter, ahead of plan.
Management's tone was noticeably more emphatic. It cited very strong procedure volumes into the fourth quarter and 2027 even as peers offered mixed commentary.
The product calendar is the main forward catalyst:
- 3P Hip moved to full release.
- PNP Retrograde won FDA clearance and logged its first cases in October.
- The PediHip Rigid Brace reached full release.
- TractorFIX entered limited launch.
- Initial Traxio units sold out, prompting an accelerated 2027 build.
Cash flow is the other improving thread. Free cash flow was a positive $1.6 million, compared with $3.4 million of usage a year ago and negative results in each of the first two quarters. Management extended its commitment to positive free cash flow in 2027 and beyond. Bears still have legitimate ammunition, however:
- Year-to-date free cash flow remains a negative $6.6 million, so breakeven for 2026 requires a strong fourth quarter.
- Cash and investments have fallen to $44.9 million from $62.9 million at year-end.
- Ellie's first-in-human procedure slipped to early 2027 pending FDA IDE approval and is now a 2028-2029 revenue story.
- The implied fourth-quarter revenue midpoint near $69 million points to slower growth against tough comparisons from prior-year Brazil set sales and 7D units.
- Holding the EBITDA guide implies roughly $9 million in the fourth quarter, a meaningful sequential step-up the company must now deliver.
Investor sentiment improved materially heading into the report, rising from 0.07 to 0.30. That is a shift from essentially neutral to moderately positive. Shares closed at $24.02 ahead of the release, up 8.7% from the open after the August report. The stock sat about 24% above its 200-day moving average, but roughly 10% below the $26.74 52-week high set on August 20. In other words, the market had already rewarded the growth story and then given back part of a post-report spike. The Earnings Whispers trend signals are mostly positive, with price, momentum and AVWAP constructive and sequential growth neutral.
The bottom line is that OrthoPediatrics answered the growth question convincingly, with accelerating revenue, a scoliosis rebound, a crowded launch pipeline and a third guidance raise. It has not yet answered the leverage question. Profit guidance has stayed static while revenue expectations climbed, adjusted losses barely moved, and full-year cash goals hinge on the fourth quarter. With sentiment already more constructive and shares well above long-term trend, the next leg likely depends on proving that growth can finally show up in EBITDA margins and sustained free cash flow.
Read our earnings preview for OrthoPediatrics Corp.: https://www.earningswhispers.com/article/KIDS/20768
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-13 | |
| Oct-07 | |
| Oct-01 | |
| Sep-22 | |
| Sep-18 | |
| Aug-25 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-29 | |
| Jul-21 |
