MNTN's Q3 Must Prove Revenue Growth Can Reaccelerate After Three Straight Slowdowns
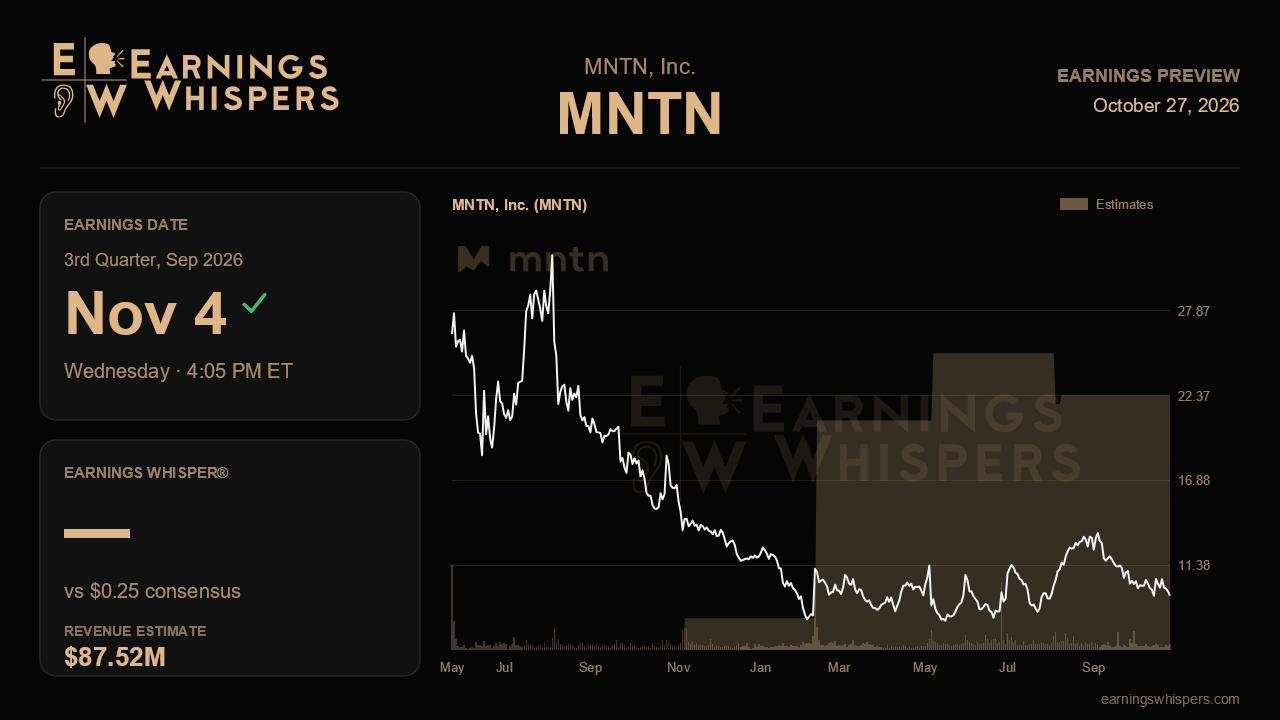
MNTN heads into its third-quarter report with an unusual promise to keep. Revenue growth has slowed for three consecutive quarters, from 36% to 25% to 21%. Yet management's own outlook calls for growth to climb back to roughly 25% this quarter. That turns the November 4 release, due after the close, into a direct test of whether the newer products management has been promoting can start to offset a maturing core business.
The Street is lined up squarely behind the company. Consensus calls for revenue of $87.5 million, the exact midpoint of management's $86 million to $89 million guidance and about 25% above the $70.0 million reported a year ago. On the bottom line, analysts expect earnings of $0.25 per share. That is more than triple the year-ago $0.08 and more than double last quarter's $0.11, a demanding sequential step for a business adding only about $5 million in quarterly revenue. Hitting it would require the operating leverage management has demonstrated to keep compounding. Last quarter, adjusted EBITDA rose 48% and margin widened nearly five points to 26.1%, while gross margin held near 80%.
Profitability has been the dependable part of the story. Management lifted its full-year adjusted EBITDA outlook early in the year and reaffirmed it at $96 million to $101 million last quarter. Another hold or a modest raise would signal that margin expansion is intact. Revenue is less settled. The full-year range of $347 million to $357 million was nudged higher after the first quarter but only reiterated in August. Merely reaffirming it again would do little to dispel the sense that top-line momentum has stalled. A raise, even a small one, would be the clearest sign that the second-half reacceleration is real rather than hoped for.
The operating details matter as much as the headline numbers. Growth in active performance TV customers has slowed every quarter, from 67% to 40%. Another sharp step down would undercut the reacceleration thesis even if revenue lands in range. Management has pointed to several new levers. Mountain Express, the small-business tier launched in April, drew more than 7,000 signups in its first 120 days, but only hundreds have converted to paying customers. QuickFrame AI, which logged 73,000 signups through midyear, is now being framed as a possible standalone product. Premium sports inventory, including the World Cup and major league games, could also help. Evidence that these signups are turning into revenue, along with an expansion rate holding above 115%, would validate the story. Continued deferral of the payoff into 2027 would weaken it, especially with larger rivals such as Roku, The Trade Desk and Amazon eyeing the same small-business connected TV market.
The market is not giving MNTN the benefit of the doubt. Shares have slipped 3.6% since the last report, trailing the S&P 500 by about two percentage points. At $9.40, the stock trades below its 200-day moving average of $10.04 and only about 3% above its post-earnings low of $9.13. It has surrendered nearly all of a rally that briefly reached $13.66. Sentiment has edged slightly more bearish than it was ahead of last quarter, though the shift is modest. A new $100 million buyback signals management confidence, but it has not yet changed the tape.
That setup lowers the bar for a relief move, but only if the right number improves. Margin strength is largely expected. What will decide whether the narrative holds is whether revenue growth actually turns higher, customer growth stabilizes, and Express and QuickFrame begin showing up as paying business rather than signup counts. If they do, the deceleration story ends. If not, the market will likely keep treating MNTN as a profitable company whose best growth is behind it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-20 | |
| Oct-14 | |
| Oct-14 | |
| Sep-28 | |
| Sep-24 | |
| Sep-17 | |
| Sep-09 | |
| Aug-25 | |
| Aug-19 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-14 |
