National Fuel Gas Faces Production Test As Ohio Deal Shifts Focus To Fiscal 2027 Outlook
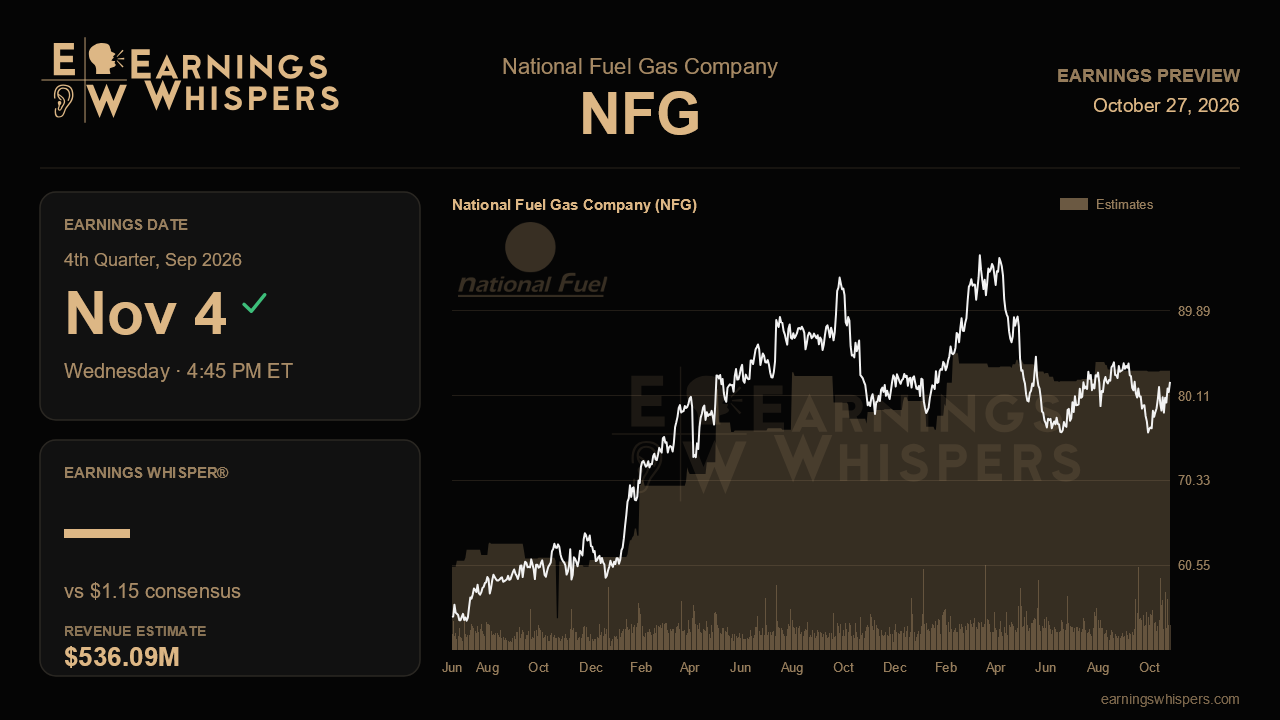
National Fuel Gas heads into its fiscal fourth-quarter report with two stories pulling in opposite directions. Its upstream business has disappointed for three straight quarters. Meanwhile, the regulated side is about to roughly double in size with the CenterPoint Ohio utility acquisition, which management targeted to close on October 1. This report closes out a fiscal year marked by repeated guidance cuts. It should also deliver the first formal look at fiscal 2027, and that outlook may matter more to the stock than the quarter itself.
Wall Street expects earnings of $1.15 per share on revenue of about $536.1 million. That would be a 5.7% decline in EPS from $1.22 a year ago, even as revenue climbs 17.5%. The gap between the two lines says a lot. Top-line strength is not flowing through to the bottom line, and the culprits management flagged last quarter are easy to identify. Seneca is producing less gas, and operating costs are higher. A new Pennsylvania labor agreement added expense, and a New York bad-debt tracker benefit will not recur. The sequential drop from last quarter's $1.54 also reflects the usual seasonal softness in the utility business during the summer months.
The guidance history frames the setup. Management opened the year calling for $7.60 to $8.10 per share. It trimmed that to $7.45 to $7.75 and then to $7.40 to $7.60 last quarter. The full-year consensus of $7.66 still sits above the top of the current range, which suggests some estimates have not fully caught up with the latest cut. That creates a modest risk that the final tally looks like a miss against stale numbers, even if the company lands squarely inside its own range. A fourth-quarter result that holds the full year near the midpoint would show the bleeding has stopped.
Production is the operational swing factor. The fiscal 2026 range has been cut from 440 to 455 Bcfe down to 420 to 430 Bcfe. Results near the low end would raise questions about whether the problems run deeper than management suggests. Management described the problems as noise rather than substance. Those problems were greater-than-expected frac interactions between offset lower Utica wells under the Gen 4 completion design, plus upper Utica wells that came in modestly below plan. Investors should look for evidence that these issues are contained before the record 30,000-foot-plus lateral pad comes online in early 2027. Each well on that pad is targeting roughly 40 MMcf/d. Any update on upstream capital, which already crept higher, and on the planned $100 million to $200 million Tioga County land spend will also help show where Seneca is headed.
The fiscal 2027 outlook is where the narrative gets tested. Management has already signaled that realized gas prices will be lower on a softer forward curve. It also expects unit costs to rise modestly and DD&A to normalize in the low to mid 80-cent range. On the other side of the ledger, the company expects about $30 million of new expansion revenue from Tioga Pathway and the shipping port lateral. Pending Supply Corporation and Pennsylvania rate cases and the Ohio utility should add more. The new 7% to 10% adjusted EPS growth target through 2029 gives investors a yardstick. A fiscal 2027 range that clearly supports that trajectory, despite higher interest costs and 4.4 million new shares, would validate the pivot toward regulated growth. A guide that leans on the low end would undercut it.
The market has not taken a strong view either way. The stock has gained 2.9% since the last report, slightly trailing the S&P 500's 4% advance. At $81.68, it sits below its 200-day moving average and in the middle of its post-earnings range of roughly $75 to $85. Sentiment remains only marginally positive and barely changed from last quarter. That points to a wait-and-see posture rather than elevated expectations. Ultimately, the report hinges on one question: can a stabilizing upstream business and a credible fiscal 2027 plan convince investors that the Ohio deal makes National Fuel a steadier compounder, rather than masking a weakening production engine?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-15 | |
| Oct-14 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Sep-17 | |
| Sep-17 | |
| Sep-10 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-09 | |
| Jun-22 | |
| Jun-11 |
