Niagen Bioscience Faces A Proof Test As Marketing Costs Swallow Profits In An Investment Year
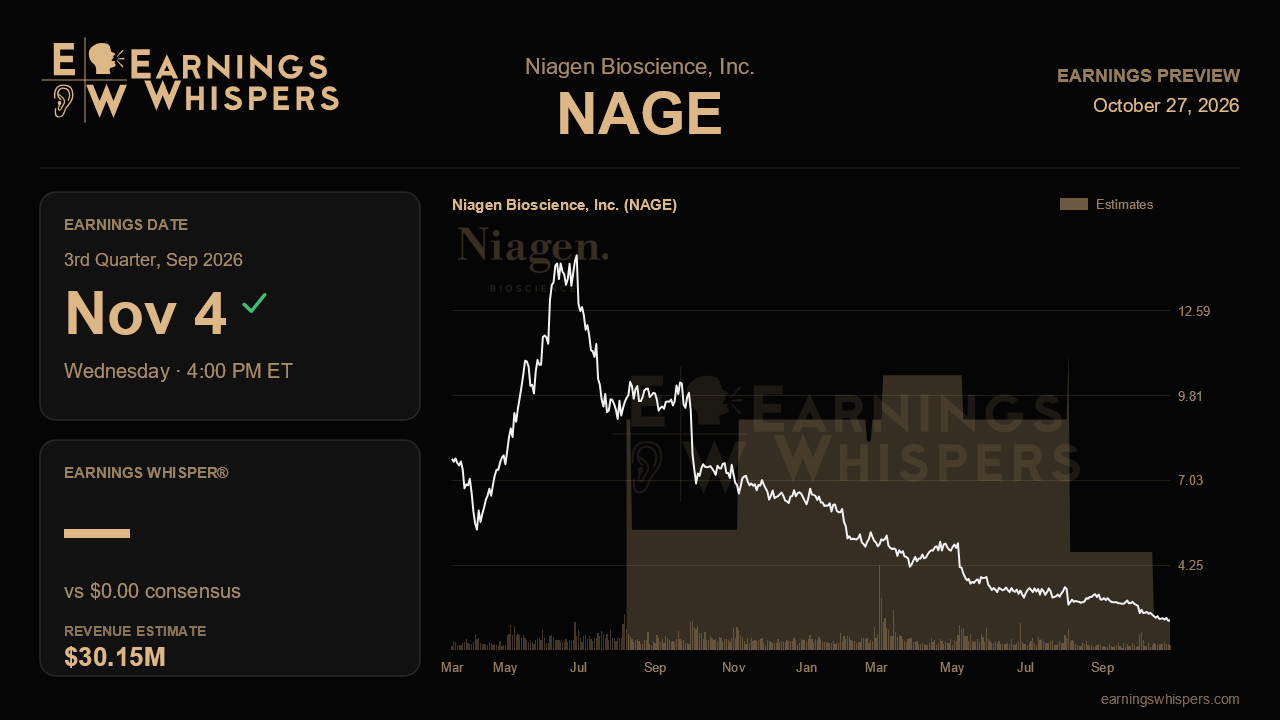
Niagen Bioscience heads into its third-quarter report asking shareholders to accept a trade: thinner earnings today in exchange for a 2027 built on pharmaceuticals, injections, skincare and China. The market has so far declined to take the other side. The shares have fallen 21.5% since the last report, trailing the S&P 500 by about 20 points, and at $2.44 they sit barely above the post-earnings low of $2.39 and far below the 200-day moving average near $4.01. The entire trading range since July lies beneath the prior quarter's floor of $3.12, which tells you how much confidence has drained out of the story.
The Street's bar is low. Consensus calls for roughly breakeven EPS on revenue of $30.2 million, down 11.3% from the $34.0 million posted a year ago, when the company earned $0.05 a share. Some of that decline reflects a demanding comparison, since the year-ago quarter grew 33%, and prior results have been framed on a basis that excludes a divestiture. Still, sequentially the forecast implies only a sliver of growth over the second quarter's $29.8 million, so analysts are essentially modeling a flat business carrying a heavier cost load.
The one explicit yardstick is management's reaffirmed target of 10% to 15% e-commerce growth for the full year, unchanged since late 2025. Second-quarter e-commerce rose just 10%, and management argued it would have been closer to 19% without a temporary Amazon listing problem in June. This quarter should settle whether that was a one-off glitch or a convenient explanation. A rebound into the mid-teens would support the guidance; another quarter near 10% would make the range look stale, especially with more than 300 NMN products crowding Amazon and pushing up keyword bidding costs. TrueNiagen growth, which slid from 44% to 6% over four quarters, is the cleanest gauge of whether the core brand is stabilizing.
Costs are the other swing factor. Sales and marketing climbed to 34% of net sales last quarter from roughly 26% a year earlier, and that jump, combined with new pharma R&D spending, cut net income to $1.0 million from $6.3 million in the first quarter. With a celebrity brand campaign and new retail placements at Sam's Club, GNC, Vitamin Shoppe and Sprouts slated for the fourth quarter, there is little reason to expect relief soon. What matters is whether that spending is starting to buy growth. Evidence of retail sell-through and improving customer acquisition efficiency would help; rising spend against flat revenue would deepen the concern. The ingredient business, now expected to finish below last year as Life Extension orders soften, offers little cushion.
The optionality pieces deserve progress reports rather than dollars. Management said a price cut to clinics using Niagen injections would come within two to three months through its second compounding pharmacy, Olympia, which puts that milestone squarely in this window. Updates on the telehealth companies exploring the at-home injection kit, the two global skincare majors evaluating the ingredient, the October and November skincare launch, China cross-border momentum and the NB4168 program for ataxia telangiectasia will shape how much credit investors give the 2027 thesis.
Sentiment has improved only marginally, to 30.2% bearish from 33.3%, so the mood remains skeptical. That cuts both ways: expectations are modest, but patience is thin. The central issue is whether the core supplement business can show reacceleration that justifies the spending surge. If e-commerce rebounds and the injection pricing fix lands on schedule, the investment-year framing holds together. If growth stays stuck while costs keep climbing, the platform narrative risks looking like a substitute for results rather than a bridge to them.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 42 min | |
| Oct-22 | |
| Oct-20 | |
| Oct-15 | |
| Oct-08 | |
| Oct-06 | |
| Oct-01 | |
| Sep-30 | |
| Sep-21 | |
| Sep-17 | |
| Sep-10 | |
| Sep-02 | |
| Aug-26 | |
| Aug-20 | |
| Aug-12 |
