Orion's Specialty Surge Faces Seasonal Test As Rubber Pricing Keeps Third-Quarter Profits Thin
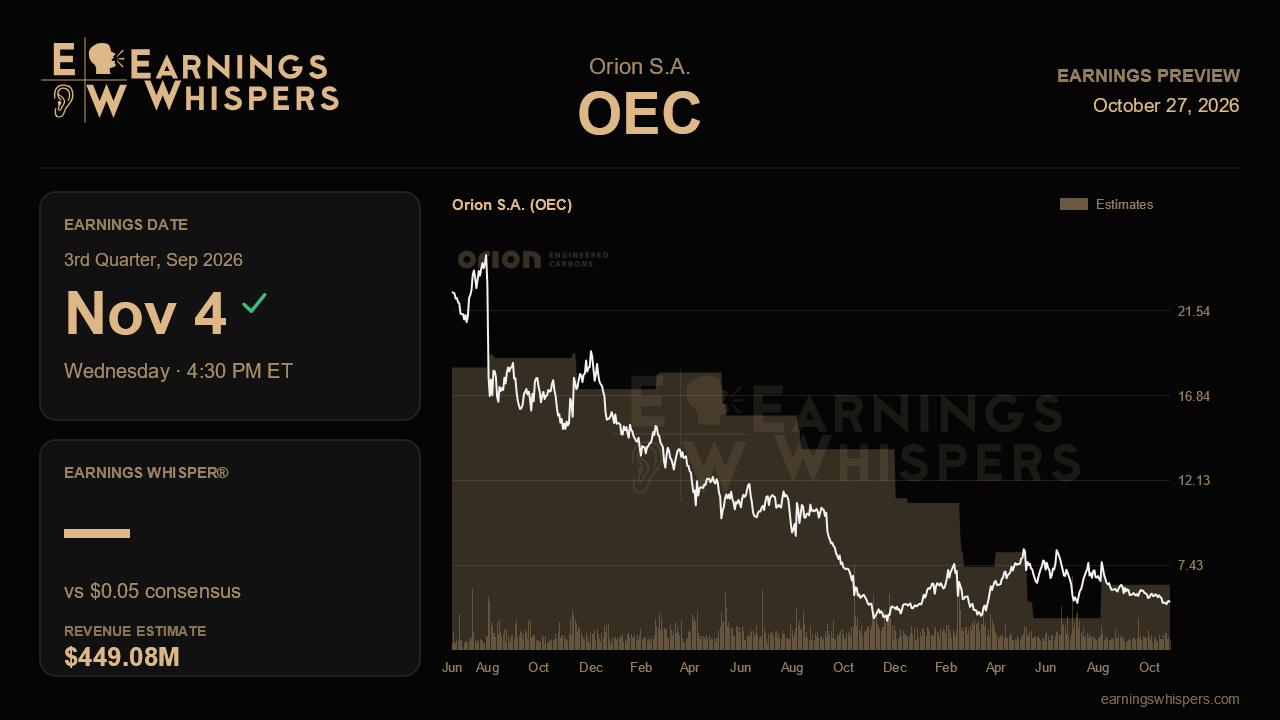
Orion S.A. heads into its third-quarter report with an awkward split personality. Last quarter, its specialty carbon black business posted its best earnings in four years, and management lifted its free cash flow outlook by roughly $43 million. Yet the stock has fallen about 26% since then while the S&P 500 barely moved. The November 4 release, due after the close, will show whether that selloff reflects a business losing momentum or a market that has stopped waiting for the rubber side to recover.
The Street is not asking for much. Consensus calls for earnings of $0.05 a share on revenue of $449.1 million. That would mean an 83% drop in profit from the $0.29 earned a year ago on essentially flat sales, and a sharp step down from the $0.14 and $500.9 million reported last quarter. Revenue stalling while earnings collapse is the signature of Orion's problem: the 2026 tire-contract pricing reset negotiated late last year is squeezing rubber margins regardless of volume.
Management's full-year adjusted EBITDA guidance of $170 million to $210 million, reaffirmed after being raised $10 million in the spring, frames the math. The first half produced about $104 million, so the second half needs roughly $66 million to $106 million, or an average of $33 million to $53 million a quarter. A thin per-share estimate suggests analysts are leaning toward the lower half of that range, which is consistent with management's own warning that specialty softens seasonally in the third quarter and that some second-quarter pricing and timing gains will not repeat. A third-quarter EBITDA figure in the mid-$40 million range would keep the guidance intact. Anything closer to the high $30s would put the low end in play and likely force a cut.
The most important question is how much of specialty's surge holds. Segment EBITDA of $39 million nearly doubled from a year earlier, driven by coatings, packaging, batteries and double-digit growth in wire and cable on new conductive grades. Management insisted these were real end-customer orders rather than restocking. A seasonal dip toward the low $30 millions would support that claim. A slide back to the $27 million level of the prior two quarters would suggest the second quarter was more timing than trend. On the rubber side, the segment earned $19 million in each of the first two quarters, and stability there would be acceptable. Any color on early 2027 contract talks, tight North American spot demand, and whether EU anti-dumping duties and falling Chinese imports are translating into better pricing leverage could matter more than the quarter itself.
Cash and debt are the other pressure points. Leverage climbed to 4.4 times from 3.7 times at the end of 2025, and the second quarter absorbed a roughly $60 million oil-driven working capital hit. The raised free cash flow target leans on extended supplier payment terms that management says it intends to keep. Evidence that leverage has stopped rising would ease a key concern.
Sentiment has turned noticeably more bearish than it was ahead of last quarter, and the stock at $5.37 sits well below its 200-day average of $6.40 and just above its post-earnings low of $5.07. That leaves a low bar but little tolerance for a guidance cut. Ultimately, the report hinges on whether specialty proves durable enough to carry Orion through a rubber trough that will not lift until 2027 pricing is set.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-22 | |
| Oct-15 | |
| Oct-13 | |
| Sep-17 | |
| Sep-16 | |
| Aug-19 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-27 | |
| Jul-15 | |
| Jun-25 | |
| Jun-04 | |
| May-28 |
