Blue Owl Capital's Dividend Cushion Faces Its First Test Without One-Time Gains
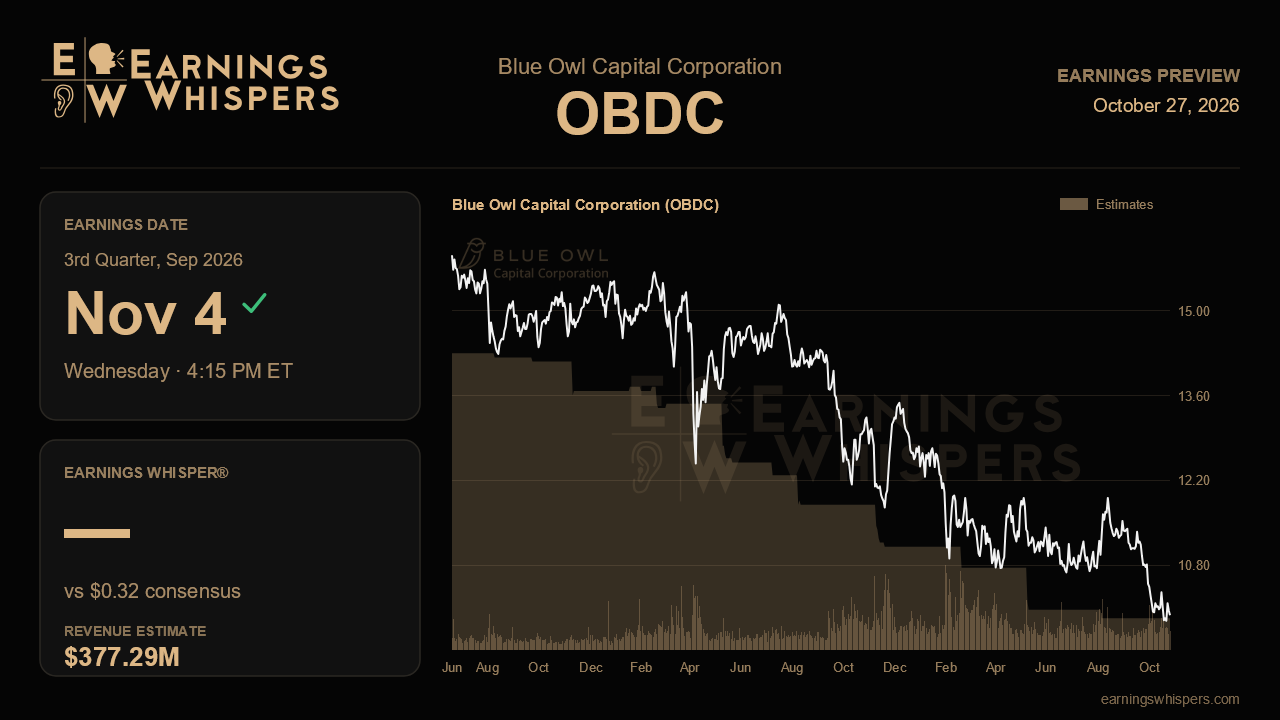
Last quarter, Blue Owl Capital Corporation gave income investors something they had not had in a while: proof that its reset 31-cent base dividend was comfortably covered. The catch is that a meaningful slice of that cushion came from one-off windfalls, chiefly the Mavis Tire preferred equity repayment and an outsized dividend from the LSI position. The report due after the close on November 4 is the first real look at what this middle-market lender earns when those tailwinds fade, and the market has not waited patiently for the answer.
The Street expects earnings of $0.32 per share on revenue of $377.3 million. That would be a step down from the $0.34 in adjusted net investment income reported last quarter and an 11.1% drop from the $0.36 earned a year ago, with revenue falling 16.7% from $453.1 million. In other words, analysts are modeling contraction, not recovery. Management offered no formal numeric outlook beyond reaffirming the 31-cent base dividend, but the consensus figure is telling. At 32 cents, coverage would slip from roughly 110% to just over 100%, leaving very little room for a supplemental payout and almost none for error. A print at or above consensus would suggest the earnings trough really is behind the company; anything below 31 cents would revive questions about whether the dividend reset went far enough.
The conference call laid out a more constructive story than the stock price implies. Management pointed to a forward rate curve roughly 100 basis points higher than at the start of the year, wider spreads on new loans, net leverage down to 1.11x, the lowest in more than two years, and fresh financing flexibility from about $800 million of unsecured bonds and an extended $4 billion revolver. Non-accruals improved to 0.8% of the portfolio at fair value. Validation this quarter would look like stable or rising recurring interest income, non-accruals holding near that level, and evidence that the lower leverage is being put to work at those better spreads.
That last point is where the narrative is most vulnerable. Fundings fell to $429 million last quarter against $747 million of repayments, and management cautioned that it saw no dramatic pickup in M&A or refinancing activity well into the current quarter. A shrinking book plus funding costs that are creeping higher as cheap legacy notes are refinanced is a recipe for margin squeeze, and it largely explains the decline in revenue expectations. Net asset value is the other pressure point. It has fallen three straight quarters to $14.26, most recently because of a credit-specific markdown on Loperex. A fourth decline, especially one tied to new problem loans or to the roughly 18% software exposure management flagged as an AI watch item, would undercut the claim that credit is fundamentally sound.
Investors have already voted with their feet. Shares have fallen 10.7% since the last report while the S&P 500 was roughly flat, and at $9.97 the stock sits below its 200-day moving average of $11.21 and just above its post-earnings low of $9.81. That price is around 70% of the last reported book value, a discount that signals deep skepticism about either the asset marks or the durability of earnings. Sentiment has soured as well, with bearish readings growing noticeably more pronounced than they were heading into the prior report. The bar, in short, is low, though a depressed stock is not the same as a cheap one if book value keeps eroding.
The central question is whether core earnings, stripped of last quarter's one-time gains, can hold above the 31-cent dividend while NAV finally stops sliding. If both happen, the improving tone from the summer call will look earned and the steep discount to book looks overdone. If either breaks, the market's pessimism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-09 | |
| Oct-01 | |
| Sep-30 | |
| Sep-07 | |
| Aug-31 | |
| Aug-13 | |
| Aug-05 | |
| Jul-24 | |
| Jul-02 | |
| Jul-01 | |
| May-13 |
The More You Know About This Private-Credit Fund, the Less You Understand
OBDC
The Wall Street Journal
|
| May-07 | |
| May-07 | |
| May-06 |
