Progyny's Summer Engagement Dip Faces Its Test As Selling Season Momentum Builds
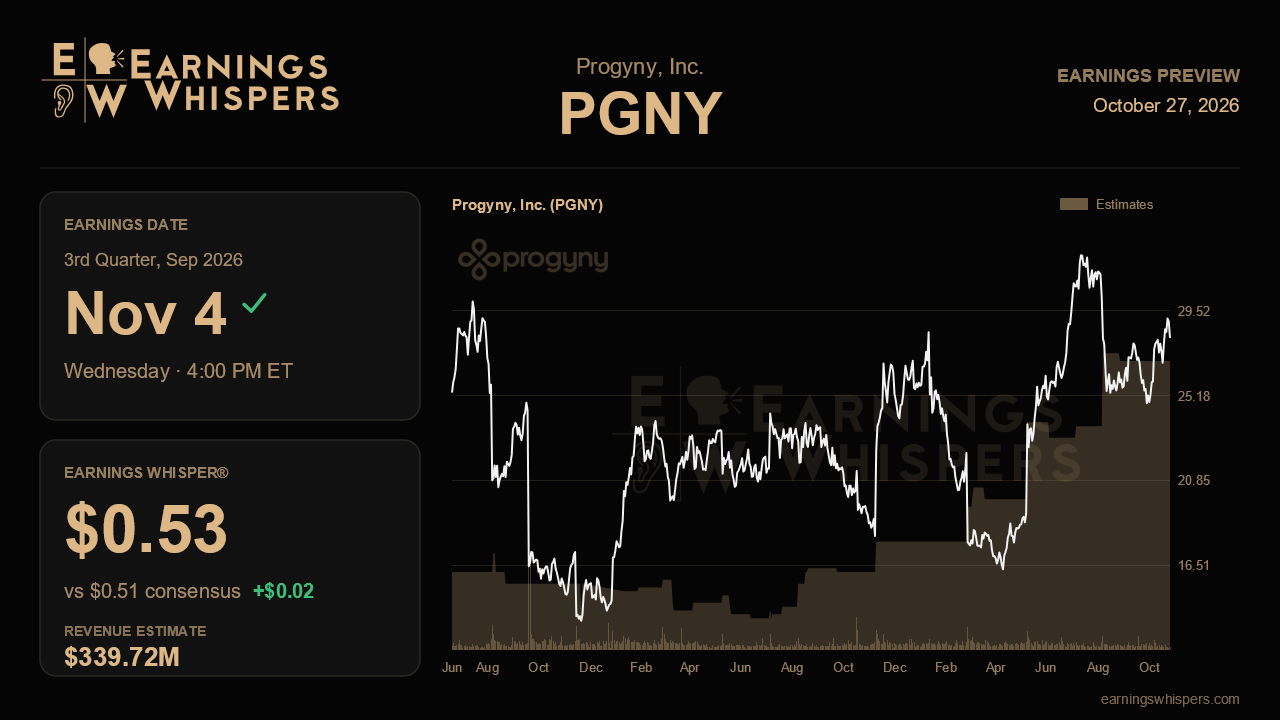
Progyny heads into its third-quarter report with a split narrative that this release should help resolve. On one side sits the most confident selling-season commentary management has offered in some time: early commitments from new clients running well ahead of last year, a brownfield pipeline fed by employers fleeing double-digit medical cost inflation, and 2027 retention described as largely locked down unusually early. On the other side sits the one soft spot from the summer call, a slightly deeper seasonal lull in fertility treatment activity that forced a trim to the top of the full-year revenue range. The September quarter is exactly where that seasonality lives, so this report is the first real check on whether the dip was transitory or the start of a pattern.
The Street is asking for earnings of $0.51 per share on revenue of about $339.7 million, roughly 8.4% above the $313.3 million posted a year ago. That is respectable but not spectacular growth, and the sequential step down from the second quarter's $350.5 million is baked in by design. Both figures sit squarely at the midpoint of management's guidance for $0.50 to $0.52 in earnings and $335 million to $345 million in revenue, meaning analysts have essentially adopted the company's own outlook without leaning in either direction. The Earnings Whisper of $0.53 sits a couple of cents above consensus and just past the top of the guided range, a modest signal that some investors expect Progyny's habit of steady margin gains and an aggressive buyback to squeeze out a bit more per share.
Engagement is the swing factor. Management conceded that neither of the first two quarters reached the high end of its engagement assumptions, and it lowered its midpoint expectation by roughly 1% while insisting the summer slowdown would normalize by September. A revenue print near or above the midpoint, along with commentary that cycle activity rebounded as the quarter closed, would validate that explanation and support the narrowed $1.36 billion to $1.385 billion full-year range. A third straight quarter of engagement landing toward the bottom of expectations would be harder to wave off as seasonality and could pressure the outlook just as the stock has regained its footing.
Profitability looks like the sturdier leg. Gross margin expanded by about 180 basis points year over year in each of the first two quarters, and the company nudged its adjusted EBITDA guidance to $233 million to $240 million. Continued margin expansion of that magnitude would show that earnings can hold up even if utilization stays merely average. The share count matters too: Progyny has retired roughly 12.5% of its shares since last November and added a $200 million authorization in May, which gives per-share results a tailwind independent of operating performance. Cash generation, which has topped $200 million on a trailing basis for six straight quarters, should remain a supporting detail.
The forward-looking commentary may matter more than the quarter itself. Investors will want confirmation that the target of more than 1 million new covered lives for 2027 is intact, color on how the brownfield wins and the prestigious university logo are converting, and evidence that the Cigna partnership keeps gaining productivity in its second year. The fully insured Progyny Select offering remains a longer-term story, and any suggestion otherwise would be a bonus rather than an expectation.
The market has already rewarded the selling-season message. Shares have climbed about 10% since the last report against a slightly negative S&P 500, trade comfortably above their 200-day moving average near $24, and sit a few percent below the post-earnings high of $29.25. Sentiment has improved from distinctly bearish to roughly neutral. That leaves less room for disappointment than three months ago. The verdict likely hinges on one question: did engagement bounce back as promised, allowing strong 2027 bookings to translate cleanly into revenue rather than being offset by softer utilization?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-15 | |
| Oct-07 | |
| Sep-11 | |
| Sep-03 | |
| Aug-24 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-23 |
