PureCycle Must Show Its Ramp Is Real As Street Expects Revenue To More Than Double
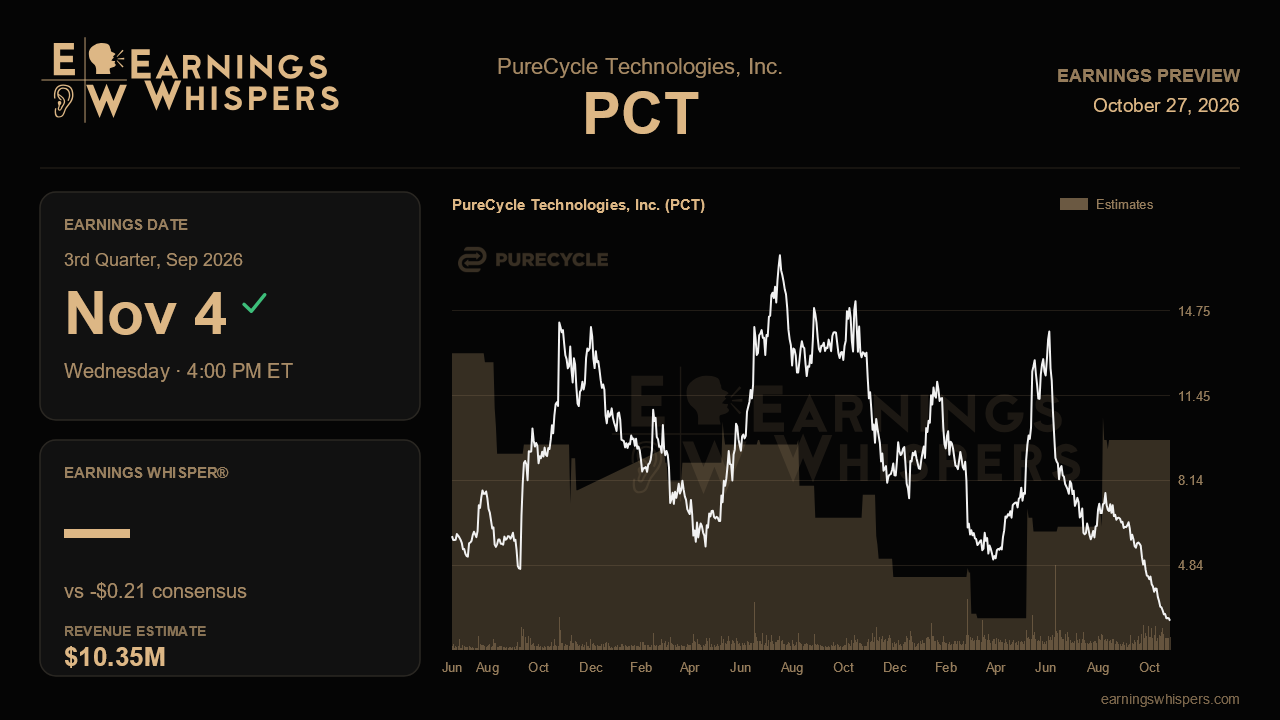
PureCycle Technologies heads into its September-quarter report with a striking disconnect. Last quarter, management said the two obstacles it had flagged all year had finally cleared: New Jersey's recognition of Pure5 as recycled content and reliable on-site compounding. The second-half ramp moved from hope toward execution. Since then the stock has lost about 60% of its value while the S&P 500 was essentially flat. When PureCycle reports after the close on November 4, it has to show that the narrative the market has abandoned is actually playing out in the numbers.
The bar is not low. Analysts expect revenue of roughly $10.4 million, up about 326% from $2.4 million a year ago. More telling, that is more than double the $4.5 million reported last quarter. Revenue has grown sequentially for six straight quarters, but always in small steps. A jump of this size would be a break from that pattern, the kind of step change management implied when it said Ironton could reach breakeven at 40% to 50% utilization in the second half. The consensus loss of $0.21 per share would compare with a $0.33 loss last quarter and $0.44 a year earlier. With no formal revenue guidance on the table, the Street's estimate is effectively standing in for management's ramp story.
Production is the first thing to check. Output fell to about 4.5 million pounds last quarter from 8.4 million during a planned, extended turnaround, and feedstock processed roughly halved. That dip was announced in advance, so a strong rebound should be the baseline expectation, not a bonus. Management has also said production chases commercial demand. Pounds made without pounds sold would therefore raise inventory questions rather than ease them. The cleaner validation would be shipments rising alongside output, plus confirmation that compounding moved from five days a week to round-the-clock operation as planned.
The customer pipeline is the second test. Procter & Gamble's Downy caps entered commercial production last quarter, with Tide caps slated next and child-resistant Vicks lids to follow. Evidence that Tide stayed on schedule would show the P&G relationship is broadening beyond a single application. The quick-service restaurant cold-cup opportunity matters even more for volume. PureCycle shipped to all three major converters in that market and estimated New Jersey QSR demand at about 20 million pounds a year. It has also pointed to 25 million to 50 million pounds of demand tied to the New Jersey approval. Investors should want to see qualifications turning into recurring orders. Progress on the conditional approval's remaining documentation would also help.
The cost side cuts the other way. Adjusted EBITDA was about negative $31.7 million last quarter, worse than a year earlier, and project spending for the year was raised to $45 million to $50 million as Antwerp and Thailand engineering advanced. Liquidity of nearly $237 million after the June financing provides runway. Even so, an update on binding Thailand project financing, which management targeted for year-end, would show whether expansion is being funded sensibly or simply accelerating cash burn.
Sentiment has softened its bearish tilt, moving from about 36% bearish before the last report to under 7% bearish now. The price action tells a harsher story. At $2.67, the shares sit just above their post-earnings low of $2.59 and far below the 200-day average near $7.46. That suggests the market is pricing in a failed or much delayed ramp. In the end the question is simple: did the pounds show up? A quarter near $10 million in revenue with clear utilization progress would reaffirm last quarter's inflection story. Another modest step-up would suggest customer adoption, one SKU at a time, is still slower than the plan requires.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Aug-12 | |
| Aug-06 | |
| Jul-23 | |
| Jul-16 | |
| Jul-15 | |
| Jun-24 | |
| Jun-23 | |
| Jun-17 | |
| Jun-16 | |
| Jun-15 | |
| Jun-11 | |
| Jun-11 | |
| Jun-10 |
