Pan American Silver Must Prove Its Gold Stumble Is Temporary As Shares Slide Toward Lows
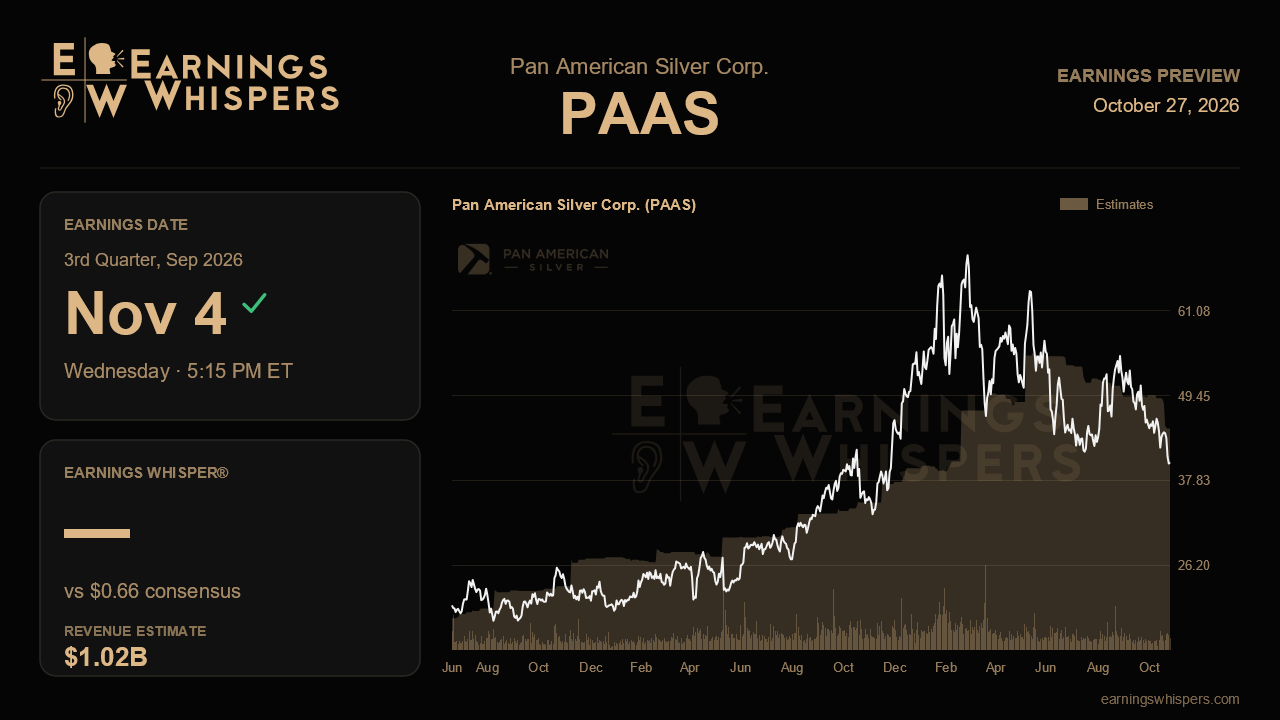
Pan American Silver heads into its third-quarter report with a story that is half reassuring and half unsettled. Silver output, cash generation and buybacks have rarely looked better, yet the company used its last call to warn that gold production would land at the bottom of its range, flagging seismic problems at Jacobina, disappointing ore continuity at El Penon and storm disruptions in South America. The market has sided with the worries. Shares have fallen 16% since that report, nearly 15 percentage points worse than the S&P 500, leaving the November 4 release as a test of whether the gold weakness is a speed bump or something deeper.
The numbers themselves still point to a strong year-over-year quarter. Analysts expect earnings of $0.66 per share on revenue of about $1.02 billion, up 37.5% and 19.4% respectively from a year ago. That is robust growth by any measure, though it also implies a step down from the prior quarter's $0.73 and $1.12 billion. In other words, the Street has already built in some softening, which lowers the bar somewhat but also signals that analysts are taking management's gold caution seriously.
Gold is the swing factor. Management guided third-quarter gold output to roughly 3,000 to 6,000 ounces below the low end of its 178,500 to 192,000 ounce quarterly range, and the second quarter's roughly 166,000 ounces had already missed the earlier outlook. Hitting that revised figure would validate management's framing that the shortfalls are deferred ounces rather than lost ones. Another miss would raise harder questions, particularly at Jacobina, where larger pillars and slower mining of high-grade zones could prove a lasting change in how the mine operates rather than a temporary resequencing. Commentary on the Jacobina plant trade-off study, which weighs upgrading the existing circuit against building a new facility, could also hint at how management views the asset's long-term economics. Gold all-in sustaining costs, which ran near $1,984 an ounce last quarter on lower volumes and labor and materials inflation, will show whether thinner production is squeezing margins.
Silver carries the bullish half of the argument. The company reaffirmed 25 million to 27 million ounces for the year after a second quarter at the high end of guidance, and first-half silver costs tracked below the low end of the annual range. The catch is that silver costs jumped sharply in the second quarter, to $17.80 an ounce from $6.63, on inventory drawdowns, higher La Colorada royalties, currency moves and labor. A quarter that pulls costs back toward the earlier run rate would reinforce the Juanicipio-driven cost story; another elevated print would suggest the second quarter was not a one-off. Progress on the La Colorada 588 decline toward the Skarn deposit and the Timmins reserve and resource update slated for September offer growth signals beyond the quarter.
Cash returns are the other pillar. Free cash flow attributable to the company was $344 million last quarter, and management reiterated plans to return up to $1 billion to shareholders in 2026 after a record $300 million payout. With taxes paid guidance raised to $585 million to $635 million, continued buyback pace would show that the higher tax bill is not crimping capital returns.
Sentiment has improved from bearish to modestly bullish since the last report, an interesting contrast with the stock's slide. Shares at $40.32 sit well below the 200-day moving average of $52.09, close to the post-earnings low of $39.28 and beneath the prior quarter's trough. That positioning means the stock is not priced for perfection. What will decide whether the narrative holds is simple: if gold lands where management said it would and silver costs settle, the second-quarter wobble looks contained. If gold slips again, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-09 | |
| Oct-07 | |
| Oct-07 | |
| Sep-28 | |
| Sep-24 | |
| Sep-22 | |
| Sep-17 | |
| Sep-16 | |
| Sep-16 | |
| Sep-05 | |
| Sep-05 | |
| Sep-02 | |
| Sep-01 | |
| Aug-31 |
