Sensata's Beat Leans On A One-Time EV Payment, But Data Center Wins And Deleveraging Keep The Story Intact As Auto Softens
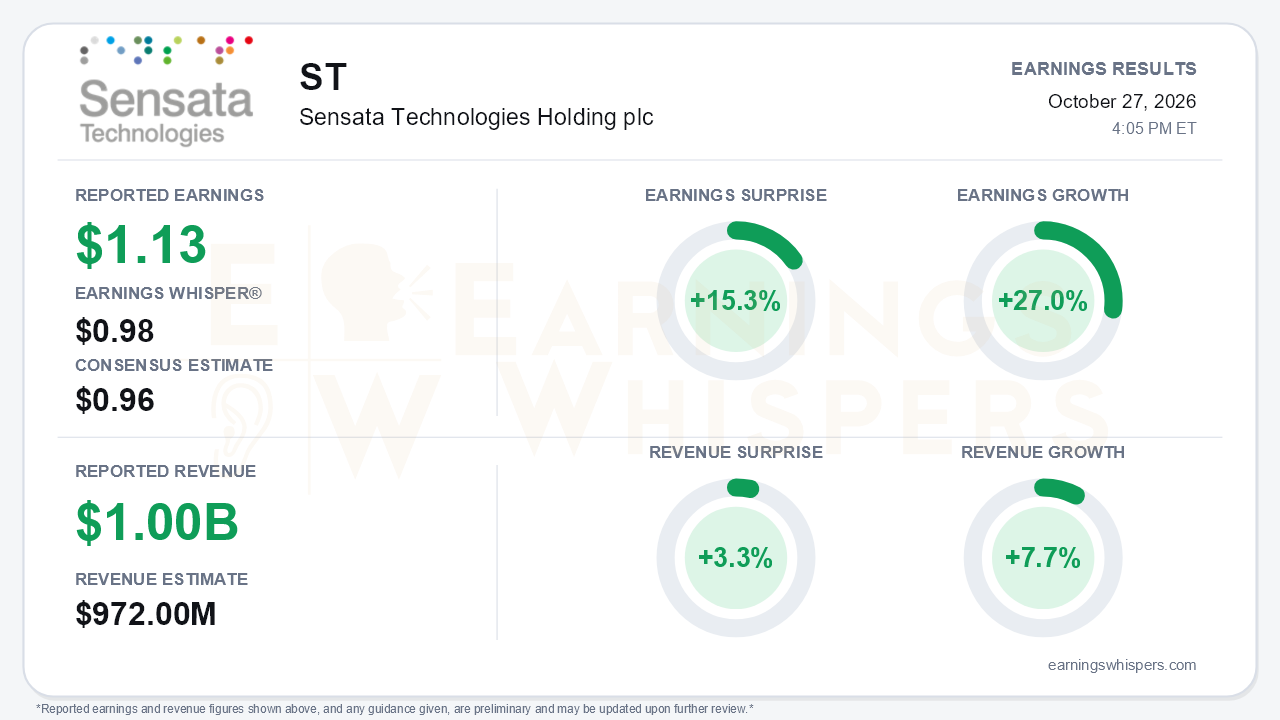
Sensata Technologies (NYSE: ST) posted third-quarter adjusted earnings of $1.13 per share, 15.3% above the $0.96 consensus and well ahead of the $0.98 Earnings Whisper number. Revenue of $1.004 billion beat the $972.0 million consensus by 3.3%. Adjusted EPS grew 27.0% year over year, and revenue rose 7.7%. The quality of the beat deserves scrutiny, however. A $24.0 million termination payment from a customer that cancelled an electric vehicle program accounted for roughly $0.16 of the EPS total. Excluding it, adjusted EPS would have been $0.97, just above consensus and a penny shy of the whisper. Revenue would have been $979.6 million. That is the central tension: the underlying quarter was solid and on plan, not the blowout the headline implies.
Beneath the payment, the trends are steadier than they are accelerating. Organic growth was 6.8% as reported, but the termination payment contributed 2.6 points of it. That leaves roughly 4% underlying growth, essentially in line with the 4.4% and 4% organic pace of the prior two quarters. Margins are where the improvement is more durable:
- **Operating margin:** Underlying adjusted operating margin was 19.5%, up 20 basis points year over year. It matched Q2 and improved from 18.6% in Q1. The call noted this was the fifth straight quarter of year-over-year expansion.
- **GAAP results:** The swing was dramatic, from a $1.12 loss to a $0.78 profit. That comparison mostly reflects last year's $225.7 million goodwill impairment rather than operating transformation.
- **Cash flow:** This was the cleanest part of the quarter. Free cash flow was $198.3 million, a 119% conversion rate, and year-to-date free cash flow of $489 million already matches all of 2025. Management now expects full-year conversion above 100%, versus a high-80s target earlier in the year.
- **Balance sheet:** Debt retirement pushed net leverage down to 2.1x from 2.7x at year-end.
The mix shift is the more interesting operating story. Industrials organic growth jumped to 12%, up from 4% in Q2 and 1% in Q1, with segment margin up 160 basis points to 28.8%. Aerospace, Defense, and Commercial Equipment grew 13%, helped by a North American Class 8 truck recovery that lifted production about 50%. That segment's margin did slip 70 basis points, though, and aerospace and defense grew only mid-single digits. Automotive is the weak link. Excluding the payment, the call put auto outgrowth at only about half a point, versus 4% in Q1 and 2% in Q2. China is deteriorating, with the domestic market excluding exports down roughly 25%, multinational OEMs losing share, and pricing pressure intensifying.
The call preserved a credible longer-term growth narrative around data centers. Management disclosed data center revenue rising from $27 million in 2025 to an expected $48 million in 2026. That figure excludes Dynapower and the hyperscaler programs. Hyperscaler design wins climbed to seven across six customers, up from five in Q2 and one at the start of the year. Management also launched an ultrasonic flow sensor for liquid cooling, with initial shipments expected in mid-2027. It is repositioning Dynapower toward data center power, which it framed as an "orders of magnitude larger" opportunity from mid-2027. Record motor and actuator wins in aerospace and drones add another leg. The catch is timing: these are 2027-and-beyond catalysts, while the auto drag is immediate.
Near-term guidance is where bears have legitimate ammunition. Q4 guidance of $942 million to $972 million in revenue and $0.95 to $0.99 in adjusted EPS is broadly in line. The guided EPS represents 8% to 13% growth. But the revenue range sits about 2% below Q3's underlying level, short of the flattish sequential trend management had signaled on the Q2 call. It assumes global light vehicle production falls about 4% in Q4. Management went further, saying Q1 2027 revenue will not rise sequentially and that consensus may not fully reflect Q1 margin seasonality. Inflation pressure has also migrated from precious metals to electronics and PCBs, ironically driven by the same data center demand Sensata is chasing.
The market entered the report already skeptical. Shares had fallen 17.5% since the open following the July report, to $40.69. That left them 2.6% below the 200-day moving average and just 2.7% above the inter-earnings low of $39.61, set on October 23. Price and AVWAP trend readings remain negative. Investor sentiment improved modestly, from -0.05 to roughly -0.01, moving from mildly negative to essentially neutral rather than signaling any real enthusiasm.
The bottom line is that Sensata delivered an underlying quarter at the high end of its plan, with expanding margins, strong cash generation, and rapid deleveraging. The headline beat was inflated by a one-time payment that will not recur. With auto softening, China deteriorating, and management guiding Q4 down sequentially and Q1 2027 no better, the data center and industrial momentum must carry the narrative. That burden falls on a stock that has spent the quarter near its lows.
Read our earnings preview for Sensata Technologies Holding plc: https://www.earningswhispers.com/article/ST/20799
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 26 min | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Oct-14 | |
| Oct-14 | |
| Sep-08 | |
| Sep-02 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-23 |
