PROCEPT's Third Quarter Tests Whether Legacy AquaBeam Weakness Has Bottomed After Two Procedure Cuts
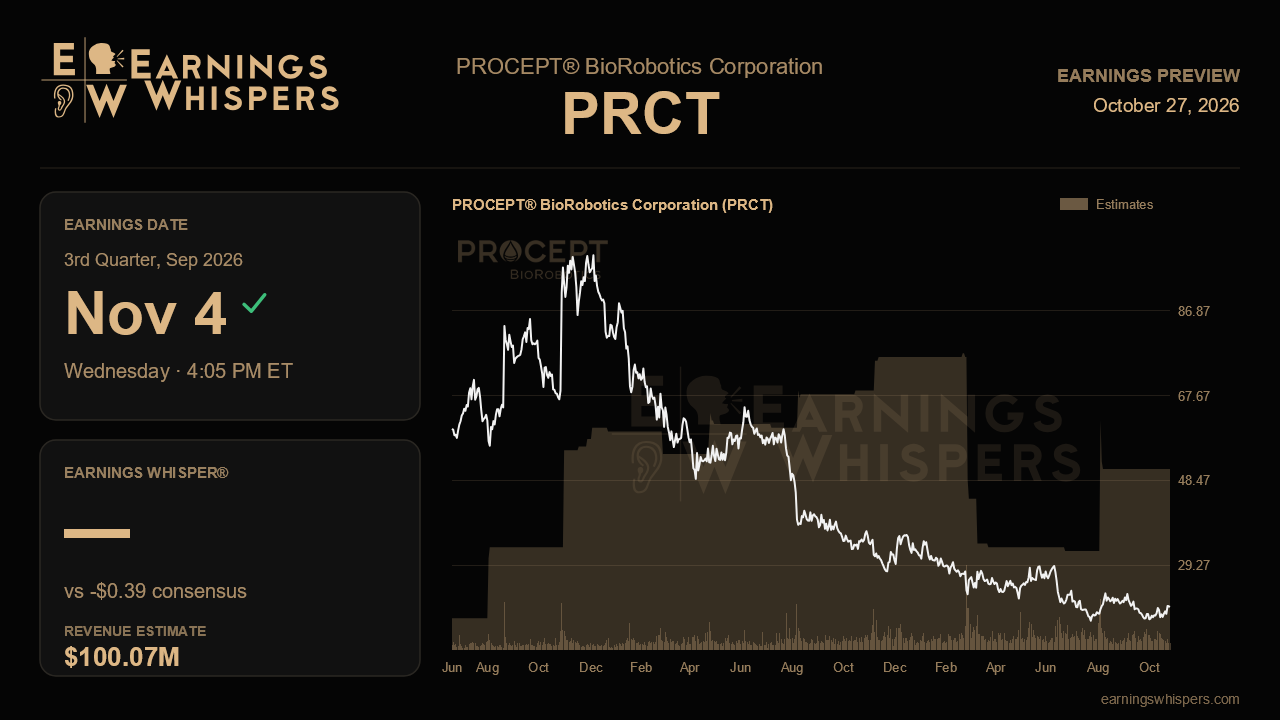
PROCEPT BioRobotics heads into its third-quarter report with a credibility problem that has nothing to do with its technology. The company has cut its procedure outlook in consecutive quarters, most recently slashing 2026 guidance to 54,000 to 56,000 procedures from 60,000 to 64,000, and management conceded it does not fully understand why its legacy AquaBeam accounts, roughly half the installed base, suddenly softened. Yet the stock has climbed about 13.6% since that report while the S&P 500 slipped 1.4%. The November 4 release, due after the close, needs to show whether that rebound reflects a business stabilizing or simply a market that had overshot to the downside.
The Street is looking for revenue of about $100.1 million, up roughly 20% from $83.3 million a year ago and a step up from the $94.5 million posted last quarter. The consensus loss of $0.39 per share is essentially flat with the year-ago $0.38, which fits management's decision to lift operating expense guidance to $355 million to $360 million to fund direct-to-patient advertising and commercial expansion. Full-year consensus of $396.4 million sits in the lower half of the reaffirmed $390 million to $410 million range. That positioning matters. Revenue guidance was first floated at $410 million to $430 million, reset lower, and has since only been held, so the market is already discounting the bottom of the range rather than the midpoint.
The most important number will be U.S. procedure growth, and specifically what is happening inside legacy AquaBeam accounts. Last quarter's 21% procedure growth was below plan, and the explanation was unsatisfying. A quarter in which legacy utilization stabilizes, or in which management can finally articulate a cause and a fix, would go a long way toward rebuilding trust. Another unexplained shortfall, or a third trim to the procedure range, would suggest the problem is structural rather than transitional and would undercut the thesis that Hydros can carry the installed base forward.
There are genuine offsets to weigh. Pricing has been remarkably firm, with U.S. Hydros system prices reaching roughly $495,000 and handpiece prices climbing to about $3,550, each a record. The replacement cycle also jumped from 2 units in the first quarter to 14 in the second, and management raised its full-year replacement target to about 40, implying around two dozen upgrades across the back half. Hitting that pace would show legacy customers are choosing to recommit to the platform, which is arguably the best possible answer to the utilization worry. The caveat is that replacements carry lower prices of $300,000 to $325,000 and cause short-term disruption, while greenfield placements are running roughly flat year over year. Progress on the dedicated launch team, which handled about 40% of placements last quarter on the way to a year-end goal of 100%, is another tell for whether new accounts ramp faster.
Profitability remains a secondary but real test. The adjusted EBITDA loss guide widened to $30 million to $35 million, so any further slippage would compound concerns that heavier marketing spend is arriving before demand responds, especially since management itself noted patient activation benefits are slowed by two-to-four-month hospital scheduling waitlists.
Sentiment has improved, with the bearish reading easing to roughly 25.5% from nearly 48% a quarter ago, but the chart still reflects caution. At $19.83 the shares trade well below their 200-day average near $23.61 and sit in the middle of a $16.74 to $22.93 post-earnings range, far beneath the prior quarter's $29.74 high. That leaves room for a relief move, but only if the core question gets answered: are legacy AquaBeam accounts stabilizing as Hydros upgrades and launch-team support take hold? Clinical catalysts like the Water4 readout are still a 2027 story. This quarter is about proving the procedure engine is no longer leaking.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-12 | |
| Oct-07 | |
| Sep-17 | |
| Sep-16 | |
| Sep-15 | |
| Aug-31 | |
| Aug-17 | |
| Aug-13 | |
| Aug-11 | |
| Aug-11 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 |
