Red Violet's Third Quarter Tests Whether Record Momentum Survives A Slower Street Forecast
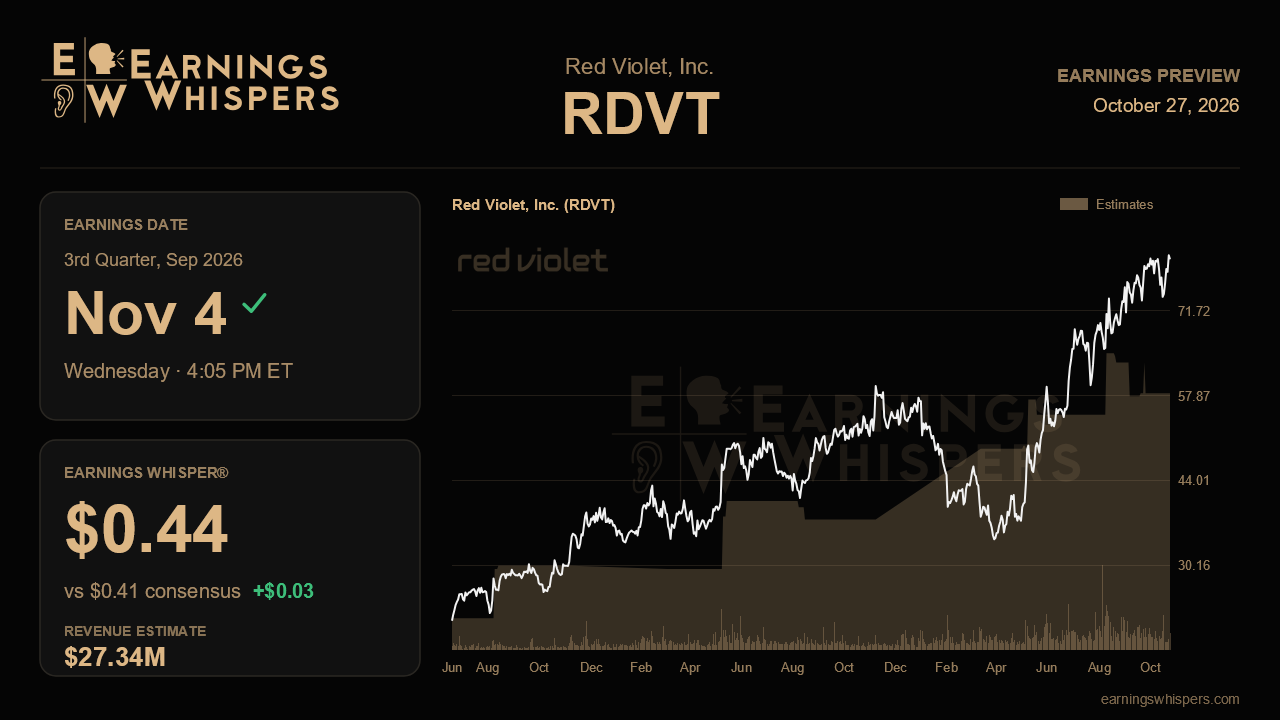
Red Violet heads into its third-quarter report with a curious mismatch between what management just delivered and what Wall Street is penciling in. The June quarter was the identity-intelligence provider's best on nearly every measure, with revenue growth accelerating to 23%, margins setting records and customer additions hitting a new high for the second straight quarter. Yet the consensus forecast for the September period implies growth cooling to roughly 18%. That gap is the story. Either analysts are being prudently conservative, or they see the second quarter as a high-water mark that will be hard to repeat.
The Street is looking for non-GAAP earnings of $0.41 a share on revenue of about $27.3 million, up 18.4% from $23.1 million a year ago and only modestly above the $26.7 million posted last quarter. The Earnings Whisper sits at $0.44, a few cents above consensus, suggesting the informal bar is somewhat higher than the published one. Per-share comparisons carry an extra wrinkle this time: the roughly $109 million equity offering completed during the summer enlarges the share count, so profit growth has to outrun dilution before it shows up cleanly in EPS. The company does not issue formal guidance, which leaves the prior call as the best map of what should come next.
That call laid out a broad-based case. Four of five verticals posted record revenue, with investigative work the fastest grower, collections expanding above 20% and background screening singled out as a standout. Customer adds climbed to 447 from 400, and the Forewarn real estate safety app reached 660 associations and more than 443,000 users. Validation this quarter would look like another quarter of customer additions in that 400-plus range, continued steady Forewarn user growth, and adjusted EBITDA margins holding near the record 42%. With adjusted gross margin already at 86%, there is limited room for further expansion, so stability rather than improvement may be the realistic benchmark for operating leverage.
The soft spots deserve equal attention. The core real estate business outside Forewarn slipped modestly last quarter after management had described it as stabilizing in the spring, and gross revenue retention eased to 95%, two points lower than a year earlier. A further decline in either would raise questions about churn just as the company leans on new-customer growth. Federal public-sector deals were also described as moving slower than hoped because of procurement and budget timing, so any sign of conversion there, alongside follow-through on the large law enforcement agency win that displaced a major incumbent, would strengthen the government narrative considerably.
Two newer catalysts will likely draw questions even if they do not yet move the numbers. Forewarn's push into home healthcare, a market of roughly 4 million aides and more than 12,000 certified agencies, is the product's largest expansion since its launch, and early adoption commentary will indicate whether it can become a second growth engine. Meanwhile, the offering proceeds and a newly articulated acquisition framework focused on unique data, enabling technology and vertical or international expansion mark a break from years of self-funded discipline. Any deal announcement, or clarity on timing and valuation discipline, will shape how investors weigh the dilution already absorbed.
The market has clearly bought the story so far. Shares have climbed 17% since the last report while the S&P 500 slipped about 1%, and bullish sentiment has risen noticeably from the prior quarter. At around $80, the stock trades far above its 200-day average near $56 and within about 3% of its post-earnings high of $82.19, effectively testing a breakout. That positioning raises the stakes. The central question is whether growth genuinely settles in the high teens as forecast or stays closer to last quarter's 23% pace; anything that confirms the acceleration was durable keeps the narrative intact, while a sharper slowdown paired with weaker retention would test a stock priced for continued strength.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Sep-09 | |
| Aug-27 | |
| Aug-25 | |
| Aug-13 | |
| Aug-11 | |
| Aug-10 | |
| Aug-07 | |
| Aug-05 | |
| Aug-05 | |
| Jul-28 |
