Root's Q3 Test: Can Margins Hold As Rate Cuts And A Direct-Channel Price War Bite?
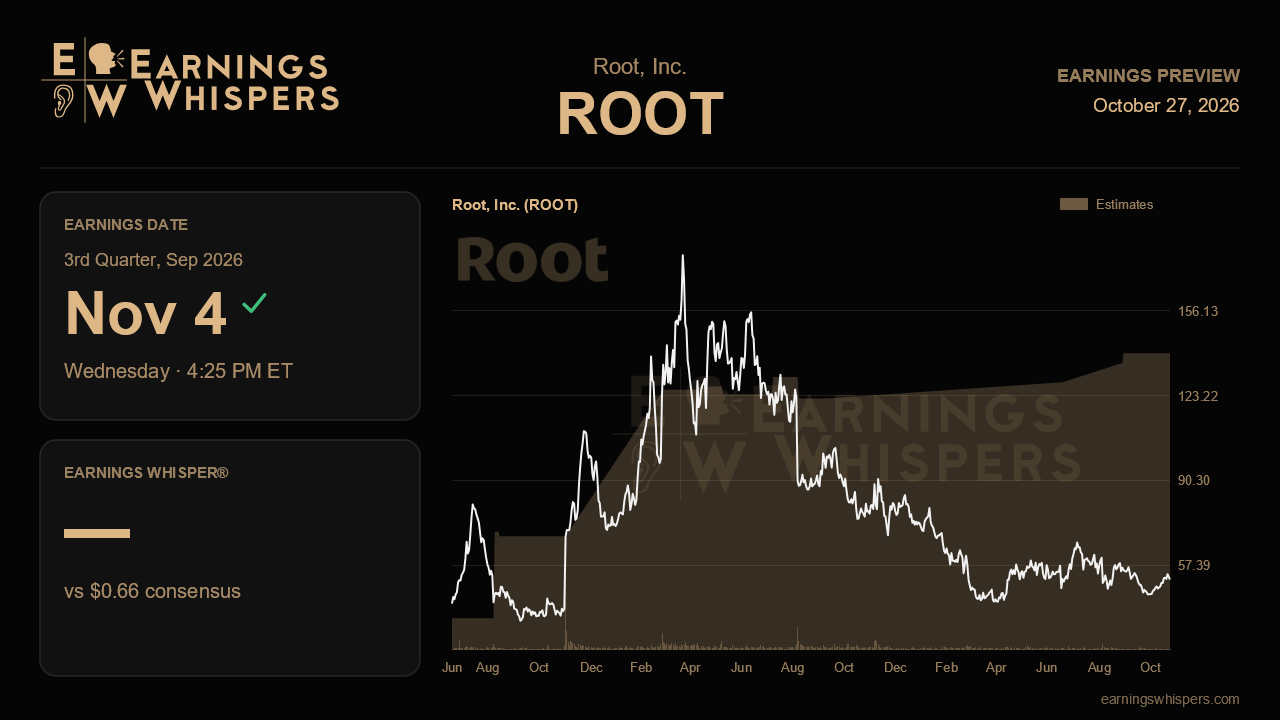
Root spent its last earnings call explaining why a company earning a 31% annualized return on equity was suddenly guiding for no growth in policies in force. When the insurer reports third-quarter results after the close on November 4, the question is whether that profitability-first retreat is protecting the franchise or simply delaying a harder reckoning on the top line.
The Street is looking for earnings of $0.66 a share. That would be a dramatic swing from the $0.35 loss of a year ago, an expected improvement of roughly 289%, but it is also less than half the $1.42 Root posted last quarter. That sequential step down is not a sign of pessimism so much as a reflection of what management flagged. Second-half loss ratios typically rise for seasonal reasons, and the renewal book's loss ratio had already climbed about five points to 54% in the second quarter. The 26% net expense ratio was flattered by lower performance-based equity compensation, and management suggested something closer to 29% is the normal run rate. Add those together and a combined ratio meaningfully above last quarter's 92.1% looks like the base case. If Root lands the quarter with underwriting margins only modestly worse, the profitability story holds. A sharper jump would raise doubts about whether recent rate cuts went too far.
Those rate cuts are the crux. Average premium fell about 8% year over year last quarter, and management indicated rates remained roughly 3% too high, implying further reductions. Revenue grew just 2% to $389.2 million, versus the 29% pace of 2025, and gross written premium shrank 2% after a 5% decline in the first quarter. Another quarter of negative premium growth would not be surprising, but it would sharpen the contrast with guidance from late 2025, when management was still promising accelerating policy growth. That outlook has since been walked back twice in spirit, first to lower full-year net income and then to roughly flat policies in force. Any further softening below flat would mark a third step in the wrong direction.
The offsetting evidence should come from distribution. Partnerships and independent agents made up about 51% of new writings last quarter, up from 44% a year earlier, and they kept growing even as competitors outspent Root on direct marketing while cutting price. The new Jerry partnership, the New Jersey launch that brings Root to 37 states, and existing relationships with Carvana, Freeway and Toyota's connected-vehicle telematics all need to show traction if the direct channel keeps shrinking. Management also earmarked about $10 million of second-half spending on new upper-funnel marketing channels, a cost that will weigh on expenses before it shows up in growth. Commentary on the next-generation pricing model slated for the fourth quarter, which management said shows striking segmentation gains, may matter more for the stock than the quarter's EPS.
The market has been forgiving so far. Shares are up about 10% since the last report while the S&P 500 slipped, yet at $51.83 the stock still sits below its 200-day moving average of $54.94 and in the middle of its post-earnings range of $45.04 to $58.84, well under the prior quarter's $67.49 peak. Sentiment has also cooled noticeably, with bearish readings rising to 48.7% from 26.5% heading into the previous report. That combination suggests investors have accepted the slower-growth framing but are not yet paying for a rebound.
Ultimately, this report hinges on whether Root can show that discipline is working: margins that absorb the seasonal and expense headwinds, policy counts holding near flat as promised, and partnership growth strong enough to offset a bruising direct market. Deliver that, and the pullback reads as cycle management. Miss on both margins and growth, and the market may conclude the price war is winning.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-07 | |
| Sep-03 | |
| Sep-01 | |
| Aug-27 | |
| Aug-12 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Jul-22 | |
| Jul-08 | |
| Jun-24 | |
| Jun-04 |
