Riley Permian's Promised Production Surge Faces Proof As Spending And Costs Climb
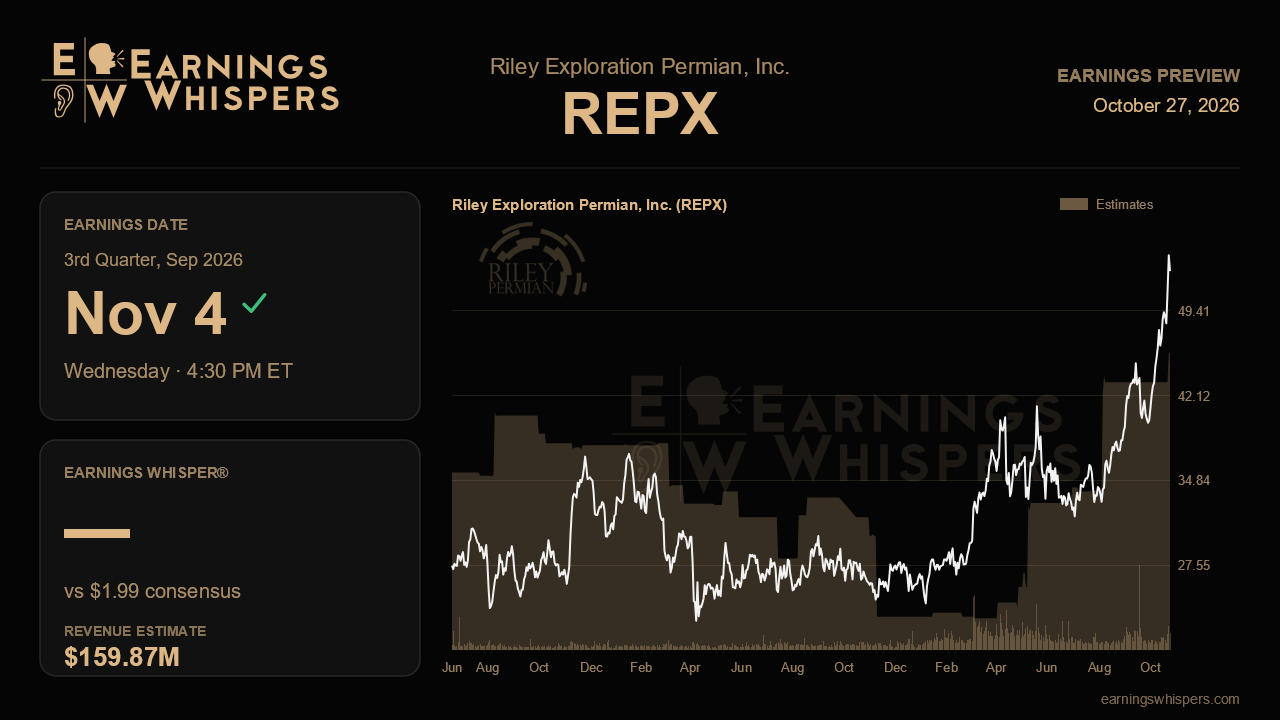
Riley Exploration Permian spent the summer telling investors that a heavier capital budget would buy a step change in oil volumes. The third-quarter report, due after the close on November 4, is the first full quarter in which that promise can be measured. Management guided to roughly 25.6 thousand barrels of oil per day at the midpoint, more than 20% above the second-quarter average. Whether the company hit that figure, and what it cost to get there, will largely decide whether the stock's powerful rally since the last report holds up.
The Street expects earnings of $1.99 per share on revenue of about $159.9 million. That works out to EPS growth of roughly 158% and revenue growth near 50% from a year ago, which is the kind of expansion few small-cap producers can claim. The sequential picture is more puzzling. Both figures sit below the $2.55 and $165.9 million posted last quarter, even though guided volumes are meaningfully higher. That gap suggests analysts are building in softer realized pricing, rising costs, or a normalization of items that flattered the second quarter. If Riley delivers its volume target and revenue still lands near consensus, the market will want a clear explanation of where the per-barrel economics went.
The production story has been moving in one direction. Full-year oil guidance has been raised at each of the last several reports, from a framing of better than 20% growth to a midpoint near 23.0 thousand barrels per day, or about 30% growth. The June exit rate of 24.4 thousand barrels per day gave that raise some credibility. Yet capital spending has climbed in lockstep, from $200 million to $210 million to $236 million, with much of the latest increase directed to saltwater disposal and oil gathering. A fourth consecutive volume raise would be welcome, but a fourth consecutive budget increase would reinforce the concern that growth is being purchased rather than earned through efficiency.
Cash flow is where that debate gets settled. Free cash flow shrank to about $6 million in the second quarter as cash capex more than doubled, and principal debt rose to $273 million. Management's argument is that the infrastructure spending is front-loaded and the payoff arrives as new wells come online. Evidence of that would include a rebound in free cash flow, stable or lower debt, and turn-in-lines that caught up after third-party delays caused a miss last quarter. Operating costs matter too. Lease operating expenses jumped by $5.4 million sequentially on higher water disposal, steel, diesel, power and service costs, reversing the improvement highlighted earlier in the year. New disposal fees tied to the WaterBridge agreement, whose commitment period began in September, add to that pressure, though management pointed to cheaper surface acid treatments as a meaningful offset.
The New Mexico timeline is the other swing factor. The Targa high-pressure gathering line slipped from a third-quarter cadence to early in the fourth quarter, and the company's development sequencing hinges on it. Confirmation that the line is in service, or firmly on schedule, would remove a key bottleneck after midstream constraints forced shut-ins of about 2,000 barrels per day in the spring. Any further slippage would hit both fourth-quarter volumes and the steady growth outlook management sketched for 2027.
Expectations have shifted sharply. The stock has gained about 55% since the last report while the S&P 500 was essentially flat, and at $52.82 it trades roughly 3% below its post-earnings high and far above its 200-day average near $35.54. Sentiment has swung from clearly bearish to slightly bullish. That combination means the market has already credited much of the volume ramp. The central question is whether Riley can show that its accelerated program is converting into cash rather than simply more barrels and more debt.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-14 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-31 | |
| Jul-23 | |
| Jul-15 | |
| Jul-08 | |
| May-21 | |
| May-08 | |
| May-06 | |
| Apr-15 | |
| Apr-13 | |
| Mar-19 |
