Revolution Medicines Faces A Spending Test As Daraxonrasib Nears Its Launch Window
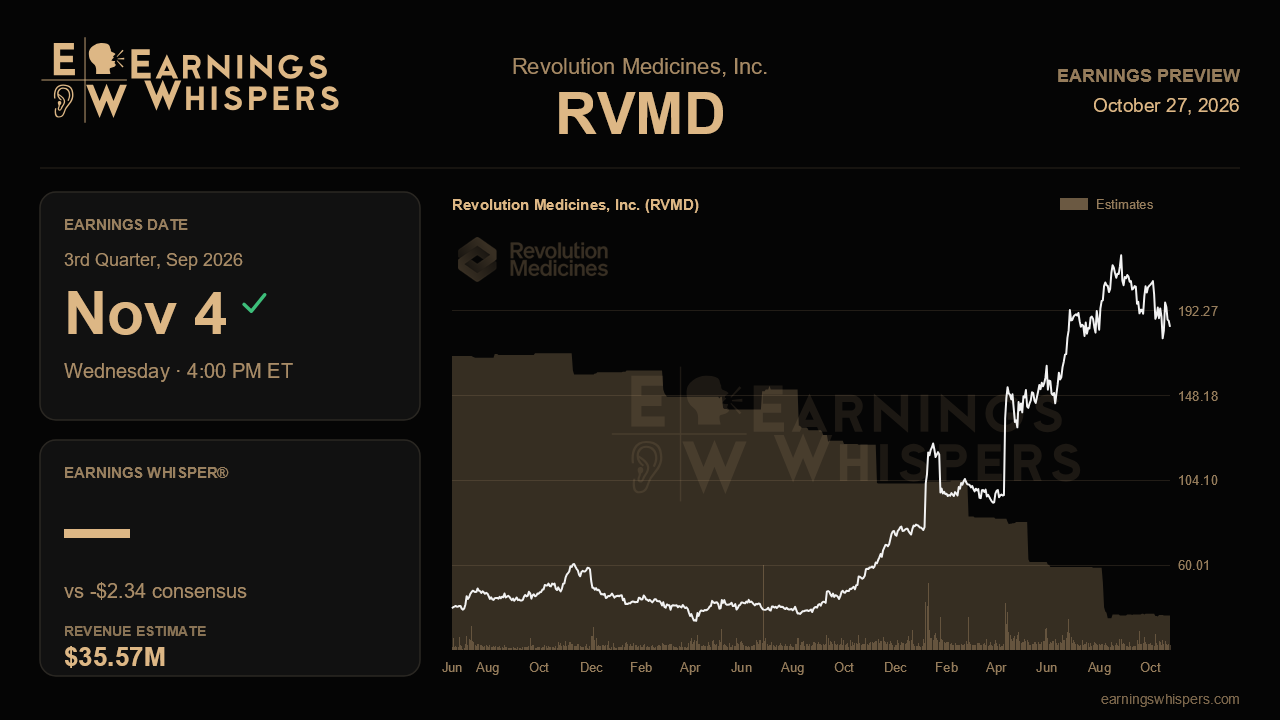
Revolution Medicines enters its third-quarter report with the scientific debate largely settled and a financial one taking its place. The pancreatic cancer trial that defined the company delivered a 60% reduction in the risk of death. The FDA has accepted the application for daraxonrasib, and Europe has begun a phased review. What remains open is whether a company that has raised its spending forecast three times this year can turn that investment into a disciplined launch without the losses getting ahead of the story.
Wall Street expects a loss of $2.34 per share when results arrive after the close on November 4. That matches the prior quarter's loss and is roughly 45% deeper than the $1.61 loss a year ago. For a clinical-stage biotech, a wider loss is not a red flag in itself. Management told investors to expect it, lifting full-year GAAP operating expense guidance from $1.6 billion to $1.7 billion at the low end, then to $2.1 billion to $2.2 billion last quarter. The consensus revenue figure of $35.6 million deserves a closer look. The company has had no product sales to anchor that estimate, so the source and size of any reported revenue will be a detail worth parsing rather than a headline driver.
The prior quarter's loss was inflated by a $151 million non-cash charge on warrants, whose value moves with the stock price. Because shares have slipped since the last report, that line could swing the reported number in either direction relative to consensus, depending on where the stock sat at quarter end. Matching expectations on the bottom line may say more about warrant accounting than about the business. The better gauge is operating spend. If spending runs at a pace consistent with the raised $2.1 billion to $2.2 billion range, management's framing of the increase as offensive investment in manufacturing, clinical breadth and an international build-out holds up. A fourth upward revision would make investors ask harder questions about where the spending curve flattens. The $3.9 billion cash cushion, plus access to up to $1.5 billion more, buys plenty of patience, but not unlimited patience.
The operational checklist is long. Investors should want an update on the FDA review timeline and on European progress. They should also look for evidence that the expanded access program, which had dosed more than 2,000 patients with an approval rate above 90%, is translating into prescriber familiarity that the roughly 60-person sales force can build on. In lung cancer, enrollment momentum in the registrational RASolve 308 trial and the start of RASolve 307 and RASOLUTE 309 would show that the breakthrough designation and strong frontline combination data are turning into execution. The colorectal update promised for the fourth quarter is another marker. Any slippage there, or new commentary about crossover pressure on survival endpoints as access broadens, would chip at the narrative.
Sentiment has swung sharply, with bullish readings jumping to about 75% from roughly 33% a quarter ago. The stock has not followed. Shares are down 7% since the last report, trailing the S&P 500 by more than six points. At $183.90 they sit near the bottom of the post-earnings range of $175.91 to $224.31, though still comfortably above the 200-day moving average near $154. That gap between optimistic sentiment and a fading share price suggests the market has priced in the clinical win and is now waiting to see the cost of commercialization.
The central question is whether Revolution can show that its sharply higher spending is buying a smooth path to approval and launch. Steady expense trends, clean regulatory updates and visible progress in lung cancer would keep the transformational-year narrative intact. Another jump in costs without matching milestones would test it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-25 |
ESMO26: Clinical progress shifts a historically difficult pancreatic cancer landscape
RVMD
Clinical Trials Arena
|
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 |
