Sunrun Must Prove Its Direct-Sales Pivot Can Halt A Slide In Unit Margins
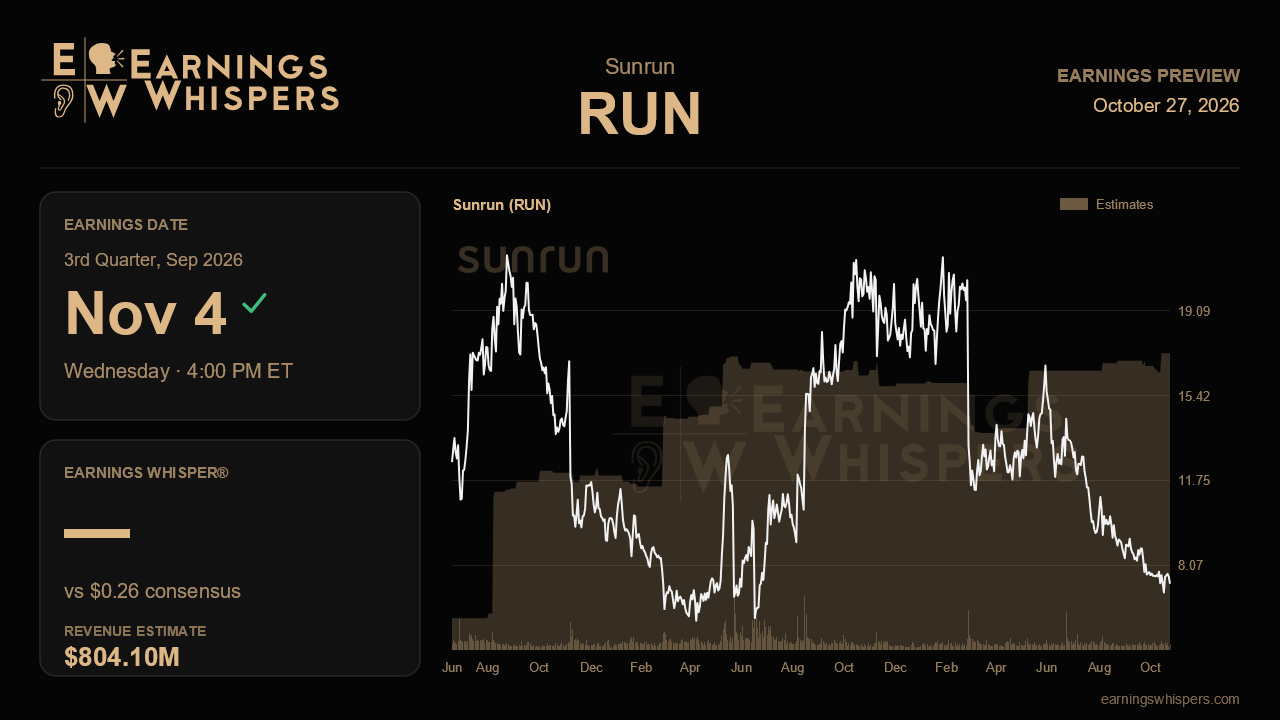
Sunrun heads into its third-quarter report with a credibility problem rather than a demand problem. Three months ago the residential solar and storage company cut its full-year cash generation and subscriber value targets for the first time this cycle. It asked investors to treat a sharp drop in unit economics as the temporary cost of shifting volume toward its own direct sales force and away from shaky installer affiliates. The stock has since fallen nearly 20% while the S&P 500 was roughly flat. That leaves the November 4 release, due after the close, as an early verdict on whether the second-half recovery management sketched is actually showing up.
On the headline numbers, Wall Street expects earnings of $0.26 per share on revenue of about $804 million. That would be an 11% revenue gain over the year-ago quarter and more than quadruple the $0.06 Sunrun earned then. The revenue figure is a step down from the $870 million reported last quarter, however, and the EPS estimate sits well below the prior quarter's $0.42. Analysts are effectively pricing in a softer sequential period consistent with the affiliate channel's retreat. Sunrun's GAAP earnings can swing on financing and accounting items, so the more telling figures will likely be the operating metrics underneath.
The most important of those is the direct business. Management said direct volume rose more than 20% sequentially in the second quarter, with monthly sales turning positive at about 10% year over year in June and July. It projected second-half direct installs growing more than 10%. That promise came alongside a markdown of full-year direct growth to low single digits, down from the high-single to low-double-digit pace pitched at the start of the year, with slower onboarding of new sales reps cited as the culprit. Evidence that the summer sales inflection converted into third-quarter installs would validate the pivot. A flat or lagging direct number would suggest the reset guidance still has room to fall. The affiliate side matters too. Sunrun now expects that channel to shrink by more than 60% this year after the bankruptcy of partner Freedom Forever, so any further deterioration there would compound the pressure.
Margins are the second test. Upfront net subscriber value collapsed to roughly $2,000, or about 4%, last quarter from more than $5,100, or about 9%, in the first quarter, a decline blamed on front-loaded transition costs and higher capital costs. If those costs were truly temporary, this quarter should show at least a partial rebound. Financing offers some support. Sunrun's latest asset-backed deal priced at 200 basis points over benchmarks, its tightest recent spread, though rising base rates have offset part of that benefit. Progress toward the trimmed $200 million to $375 million cash generation range will indicate whether the lower end is a floor or a target. Comparability is also weaker now that Sunrun dropped two non-GAAP value metrics after an SEC comment letter.
The bull case rests on storage and grid services. Battery attachment reached a record 74%, networked storage capacity hit 4.6 gigawatt-hours on the way to a goal of more than 10 by 2028, and the distributed power plant business is targeting about $40 million in revenue with more than $10 million of operating margin this year. Investors should also want concrete updates on the Tesla and Renew Home framework to supply more than 16 gigawatts of home energy resources to hyperscalers, the distributed AI compute pilot, and the Lighthouse service offering for non-Sunrun customers.
Sentiment remains bearish but noticeably less so than before the last report, and the stock trades near $7.27. That is far below its 200-day average of $12.72 and only about 7% above its post-earnings low. Expectations are low, but not low enough to forgive another cut. The report hinges on whether direct installs and unit margins begin recovering together. If they do, the guidance reset looks like a trough. If they do not, the storage and AI story will struggle to carry the stock alone.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-14 |
California Boosts Virtual Power Plants; These Clean Energy Players Benefit
RUN -6.35%
Investor's Business Daily
|
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-07 | |
| Oct-05 | |
| Oct-02 | |
| Sep-30 | |
| Sep-28 | |
| Sep-25 |
