Sunrun's GAAP Beat Masks A Third Guidance Cut As Unit Margins Recover And Direct Sales Return To Growth
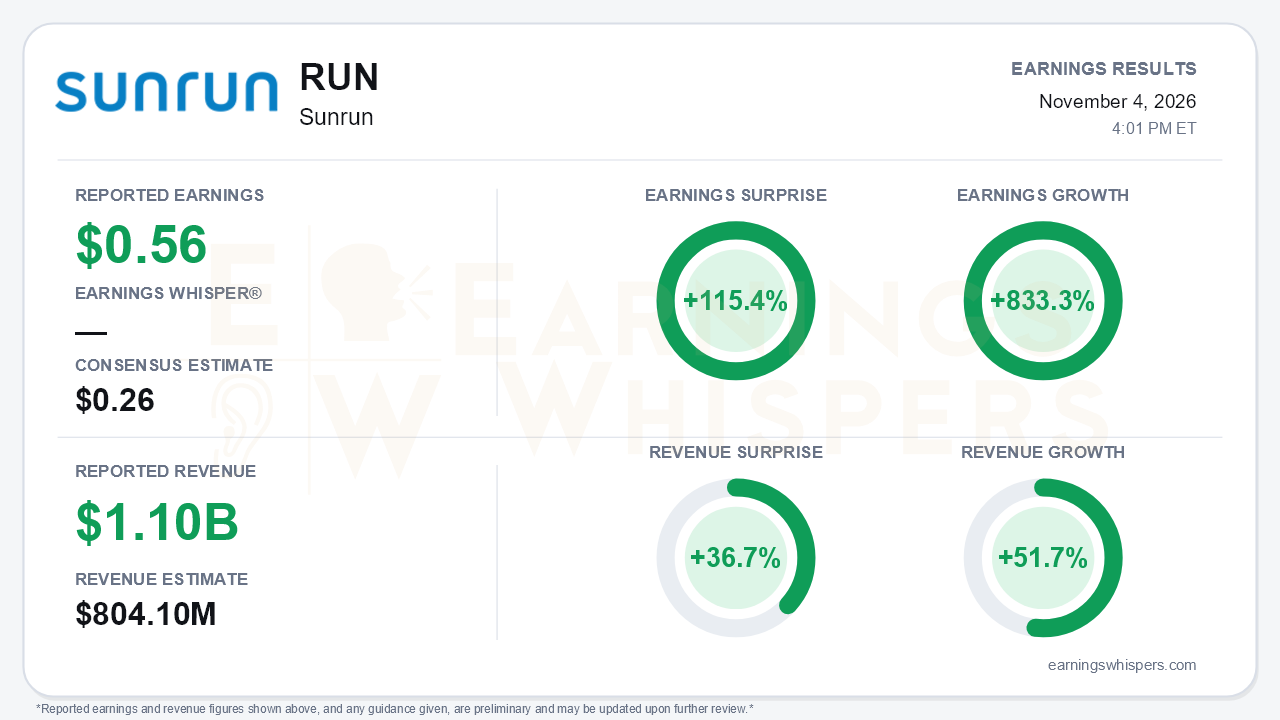
Sunrun (NASDAQ: RUN) delivered a headline quarter that looks far stronger than the business underneath it. Diluted GAAP earnings of $0.56 per share beat the $0.26 consensus by 115.4% and grew 833.3% from a year ago. Revenue of $1.099 billion topped the $804.1 million estimate by 36.7%, up 51.7% year over year. Yet the same release trimmed full-year 2026 guidance to the bottom of the prior range, the third consecutive reset. That is the central tension. The reported numbers point to acceleration, while the operating forecast keeps drifting lower.
The quality of the beat deserves scrutiny. Income from operations jumped to $153.5 million from $3.7 million. Pre-tax profit, however, depended on $164.3 million of other income, mostly a $152.9 million unrealized gain on derivatives. Net income attributable to common shareholders also benefited from a $45.2 million tax benefit and $66.3 million of losses allocated to noncontrolling interests. The revenue surge is similarly structural rather than organic. Energy systems and product sales rose 134% to $546.0 million, largely because Sunrun now sells certain newly originated systems to a third party. Customer agreements and incentives revenue grew a more modest 13%. Volume metrics tell a cooler story:
- Subscriber additions fell 24% year over year to 22,957.
- Aggregate Subscriber Value dropped 20% to roughly $1.3 billion.
- Net Subscriber Value declined 28% to $9,462.
The call did preserve a credible recovery narrative on unit economics and direct-channel demand. Upfront Net Subscriber Value rebounded to about $3,700, a 7.1% margin, from roughly $2,000 (3.7%) in the second quarter. That delivers the improvement management promised last quarter, though it only returns margins to the year-ago level of 7.3%. Other operating trends were constructive:
- Direct installs grew 17% sequentially and 9% year over year, after running roughly flat in the second quarter.
- Customer additions climbed to about 24,000 from 21,000 in the second quarter and 19,000 in the first.
- Storage attachment set a record at 75%.
- Monthly sales grew high single to low double digits from June through October.
- Illinois, Texas and New Jersey each expanded more than 25%.
The cracks sit in the details. Direct sales growth is running a few points below internal forecasts, and management softened its exit-rate framing from "over 10%" to high single to low double digits. Affiliate volume remained down 67%. Contracted Subscriber Value fell to $52,525 from $55,033 sequentially as the discount rate rose to 8.4% from 7.3% a year earlier.
The guidance cut is the most important forward-looking signal. Full-year Aggregate Subscriber Value is now about $4.6 billion, compared with $4.6-$4.9 billion previously and $4.8-$5.2 billion at the start of the year. Cash Generation, excluding safe-harbor investments, is now about $200 million, compared with $200-$375 million and originally $250-$450 million. Management said volume was the main driver, with rates secondary. Reported Cash Generation was just $6 million in the third quarter, or $56 million excluding $50 million of safe-harbor spending. Hitting the target therefore requires a heavily back-end-loaded fourth quarter.
Bears have legitimate ammunition for 2027 as well:
- ITC insurance costs are expected to shave 1-2 points from proceeds.
- A new California property tax applies to systems deployed from January 2027.
- Higher rates are expected to lift capital costs.
- Tax-equity runway edged down to about 980 MW.
- Unused warehouse capacity fell to $661 million from $840 million.
There are offsets. Management guided to 2027 installation growth and "meaningfully positive" Cash Generation, and expects all channels to grow year over year by the second quarter of 2027. Securitization spreads have tightened into the low-200s. The non-retained mix rose to 46%, and parent debt is down more than $100 million year to date. The distributed power plant story is also gaining substance:
- Sunrun contributed a record 434 MW in a single dispatch event.
- Networked storage capacity passed 5 GWh.
- Sunrun is part of a PG&E/Google proof-of-concept.
- Draft federal permitting language would mandate wholesale market access for behind-the-meter resources.
- Management says the likelihood of an ITC extension has grown.
Investor expectations were low heading in. Earnings Whispers sentiment remained negative but improved meaningfully, moving from -0.54 to -0.34. Shares closed at $8.68 before the report, down 4.0% from the open after the August release. That leaves the stock 30% below its $12.41 200-day moving average and 16.9% below the August 12 inter-earnings high of $10.45. The stock did rebound 28% from a 52-week low of $6.78 set October 20. The trend signals remain mostly negative, with price, momentum and AVWAP all weak, reflecting a stock that has been sold on each guidance reset.
The bottom line is that Sunrun's large GAAP beat says more about derivative gains, tax effects and a changed sales structure than about operating momentum. The real story is mixed. Unit margins recovered, direct volumes returned to growth and storage leadership deepened. At the same time, volume and cash targets were cut again, and 2027 faces new cost headwinds. Improved sentiment and a rebound off the lows suggest investors are willing to entertain the turnaround. Credibility now depends on delivering the fourth-quarter cash ramp and the promised 2027 growth without another reset.
Read our earnings preview for Sunrun: https://www.earningswhispers.com/article/RUN/21929
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 5 hours | |
| 8 hours | |
| 10 hours | |
| 12 hours |
First Solar Jumps 9% After Democratic Sweep, but Trumps Tariffs Already Favor It
RUN
Benzinga Prediction Markets
|
| 13 hours | |
| 13 hours | |
| 15 hours | |
| 15 hours | |
| Nov-03 | |
| Oct-28 | |
| Oct-27 | |
| Oct-14 |
California Boosts Virtual Power Plants; These Clean Energy Players Benefit
RUN -6.35%
Investor's Business Daily
|
| Oct-14 |
