Red Robin Faces Its Toughest Traffic Comparison As Re-Franchising Deals Reshape The Balance Sheet
Red Robin enters its third-quarter report with something it has not had in years: a positive same-store sales number to defend. The second quarter delivered a 1.3% comp gain and essentially flat traffic, the best showing since early 2023. The hard part starts now. The back half of the year laps the mid-2025 launch of the Big Yum value platform, which is why management held its full-year outlook rather than raising it. This report is the first real test of whether the turnaround can generate momentum on its own, or whether it was mostly borrowed from easy comparisons.
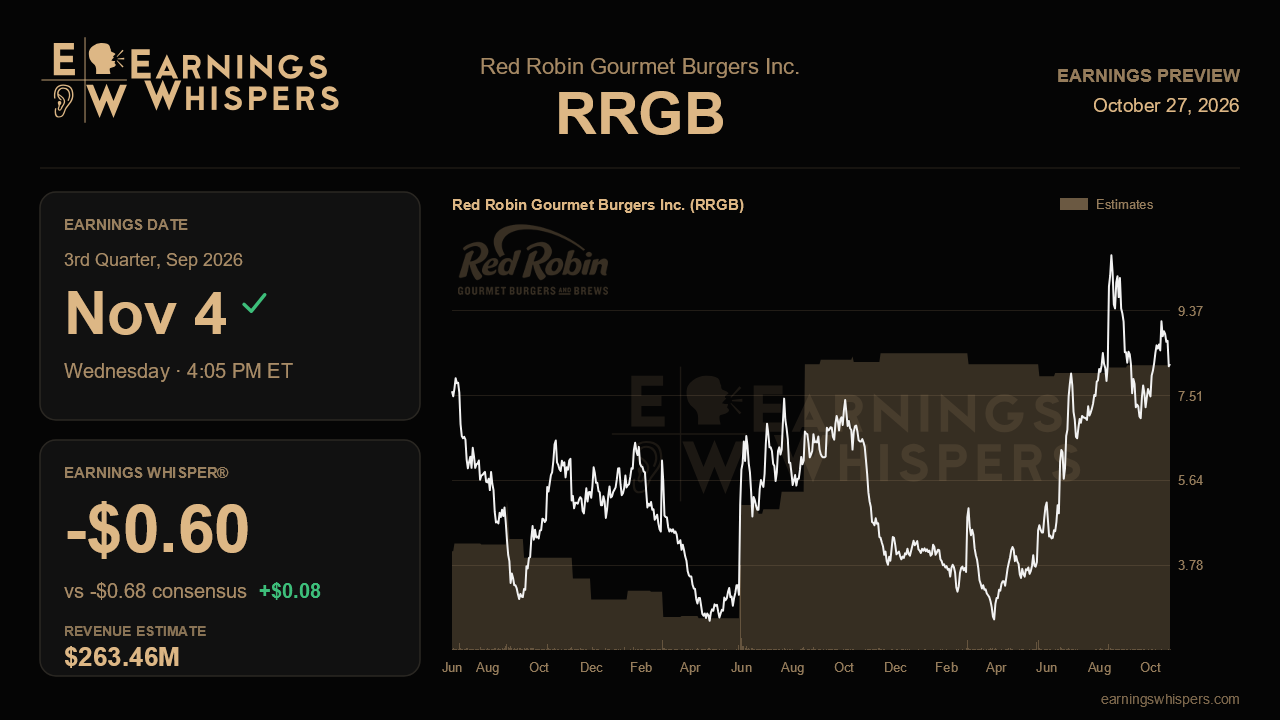
The Street expects a loss of $0.68 per share on revenue of $263.5 million. That is a slightly smaller loss than the $0.70 posted a year ago, with sales down about 0.6%, so the consensus describes a quarter that is close to flat. The third quarter is seasonally weak for this company, and a loss is normal for this period, unlike the $0.12 profit in the second quarter. The Earnings Whisper of a $0.60 loss is somewhat more optimistic than consensus. That suggests the people most engaged with the stock expect cost discipline and steady traffic to beat the published estimates, which raises the bar a little.
Management has kept the same targets since the fourth-quarter 2025 report: comps up 0.5% to 1.5%, restaurant-level margin around 13%, and adjusted EBITDA of $70 million to $73 million, most recently reaffirmed. Holding the same range through two improving quarters looks deliberate, since management said it was wary of reading too much into results within a quarter. Comps that stay positive, even modestly, while lapping Big Yum would support that range and make the conservatism look like a cushion. A slide back into negative traffic would suggest the second quarter was the peak and would put the low end of the EBITDA range under pressure.
Margins are the second swing factor. Restaurant-level margin reached 14.7% in the second quarter, a sharp recovery from 9.9% in the year-ago third quarter. Some normalization below that level is expected in a seasonally weaker period. Beef inflation is easing to a blended commodity increase of roughly 3% in the second half, compared with about 5% in the first half, which should help. The roughly $4 million increase in marketing spend that reduced second-quarter EBITDA also needs to show results. If heavier promotion of towering sliders, expanded wings, the dinner double feature and the nationwide Garage Beer launch does not hold traffic steady against a tougher comparison, that spending will look like a cost rather than an investment.
The balance sheet may matter as much as the operating results. The three re-franchising agreements, covering 116 restaurants and about $96 million in gross proceeds, were expected to close during this quarter. Confirmation that they closed and that the proceeds reduced debt would remove a major source of uncertainty. It would also change how revenue should be read from here, since company-operated sales give way to royalty income. Equally important is any update on refinancing the debt that comes due later this year. Management has suggested borrowing costs could fall from the mid-teens toward the high single digits, which would be a meaningful boost to earnings.
The market has cooled somewhat. Bullish sentiment has fallen to about 60% from 76% before the last report, and the stock has slipped 3.5% since then, trailing the S&P 500. Context matters, though. At $8.20 the stock is still well above its 200-day moving average of $5.71 and sits in the middle of a $6.72 to $10.95 range, far above the lows of the prior quarter. Investors already priced in much of the recovery and then paused. The central question for Wednesday is whether traffic holds up as the Big Yum comparisons begin. If it does, and the debt story moves from plan to completed deal, the reaffirmed guidance starts to look like a floor.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-23 | |
| Oct-22 | |
| Oct-15 | |
| Oct-14 | |
| Oct-05 | |
| Sep-28 | |
| Sep-02 | |
| Sep-01 | |
| Aug-25 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 |
