Rapid7's Margin Rally Meets Its First Real Test As ARR Keeps Shrinking
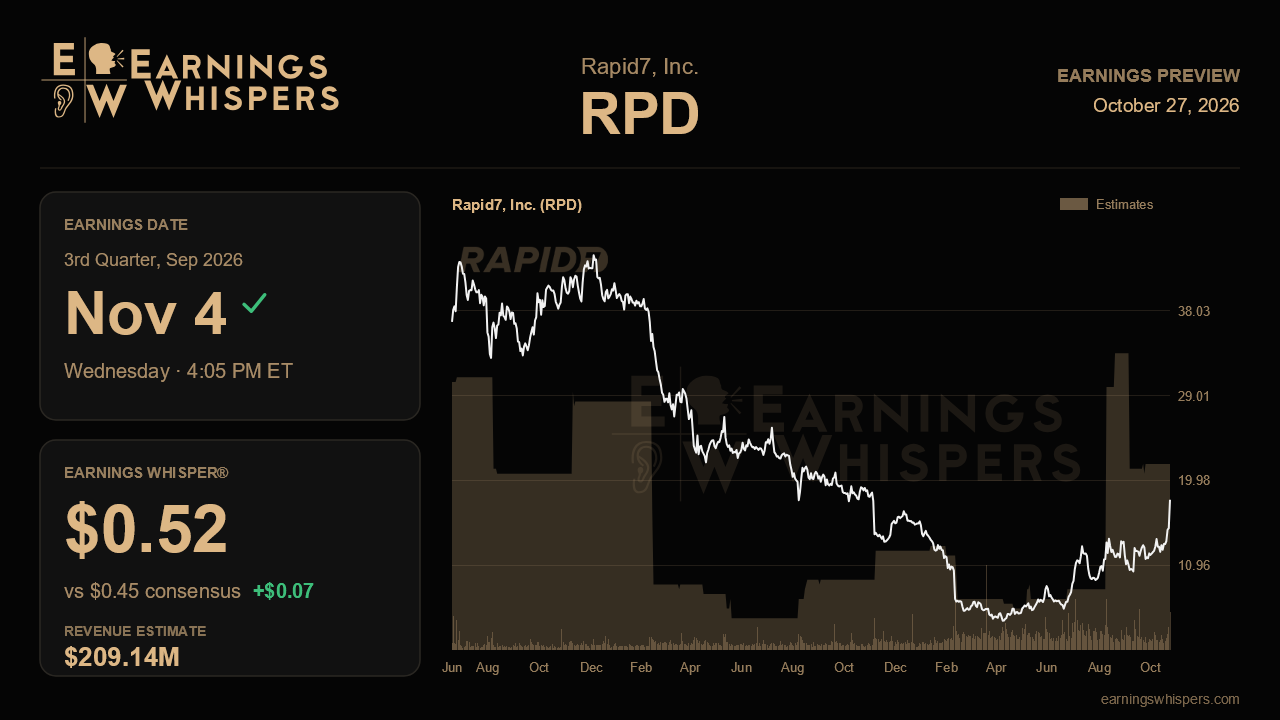
Rapid7 heads into its third-quarter report with a stock that has nearly doubled its 200-day moving average and a business that is still getting smaller. That tension defines the setup. Since the last report, new CEO Wael Mohamed has recast the company as a multi-quarter turnaround built on cost discipline, and the market has embraced the story, sending shares up about 40% while the S&P 500 slipped. The question now is whether the profit math can keep carrying a top line that management itself has described as not good enough.
On the numbers, Wall Street expects non-GAAP earnings of $0.45 per share on revenue of $209.1 million. Both sit squarely inside management's guidance of $0.44 to $0.47 and $208 million to $210 million, so the consensus is not asking for heroics. Revenue would be down about 4.1% from the $218.0 million reported a year ago, a genuine contraction rather than a pause. Earnings, by contrast, would roughly double from the year-ago $0.23, a gap that captures the whole thesis: profit growth engineered through restructuring rather than demand. The Earnings Whisper of $0.52 is meaningfully above both consensus and the top of guidance, suggesting the more aggressive money expects the cost cuts to land faster than management has signaled.
That expectation has some history behind it. Management raised its full-year operating income outlook in each of the last three quarters, most recently to $129 million to $133 million, lifting the implied margin midpoint to 15.6% from 13.3% at the start of the year. Full-year EPS guidance jumped to $1.78 to $1.83 from $1.52 to $1.60, and a new target of roughly 20% operating margin by the fourth quarter was introduced alongside a 12% workforce reduction. Third-quarter margins therefore need to show a clear step toward that exit rate. A result that lands only at the midpoint of guidance would technically be fine, but against a whisper this elevated it could read as the savings arriving slower than hoped.
The harder test is on the top line. Total ARR slid from $840 million to $824 million over the first half, and management guided it down again to about $812 million for the quarter. Detection and response, roughly 55% of ARR and the healthiest piece of the business, slowed to about 5% growth from 7%, while core platform growth decelerated to around 1%. Validation would look like ARR coming in at or above the $812 million marker, detection and response growth stabilizing rather than slipping further, and early signs that churn in the non-core products, which make up under 20% of ARR, is running its course. A challenge would be ARR falling short, evidence that endpoint vendors are encroaching on managed detection, or signs that the layoffs disrupted sales execution. Gross margin, which slipped to 71.7%, also deserves attention as a read on pricing and service mix.
Sentiment is cooler than the price action implies. Bearish readings deepened to 36.2% from 28.3% ahead of the prior report, even as the stock climbed. At $17.93, shares sit within about 1% of their post-earnings high of $18.11, effectively testing a breakout after trading in a far lower $6 to $14 band the quarter before. That leaves little cushion for disappointment.
Ultimately, this report must show that the cost story and the growth story are on converging paths. Another margin beat is largely expected. What would keep the turnaround narrative intact is evidence that ARR is nearing a floor, because a valuation rerating built on 20% margins becomes much harder to defend if the revenue base beneath them keeps eroding.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Oct-20 | |
| Oct-14 | |
| Oct-02 | |
| Sep-17 | |
| Sep-03 | |
| Aug-18 | |
| Aug-12 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Jul-28 | |
| Jul-14 | |
| Jun-15 |
