Sun Life's Third Quarter Tests Whether Stop-Loss Strength Can Outrun Hong Kong Margin Reset
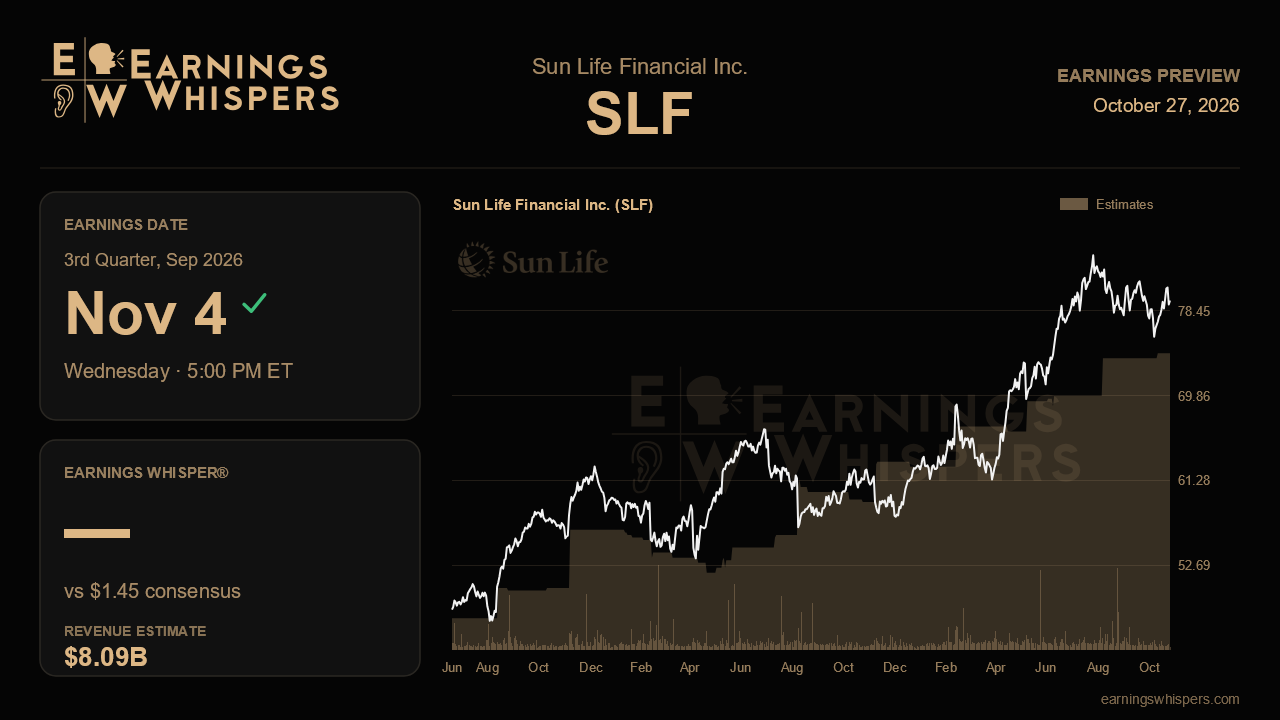
Sun Life heads into its third-quarter report with a story that improved last quarter while the stock went the other way. The insurer's second-quarter call was its most confident in a year. The US stop-loss scare that dominated last autumn had largely faded, Canada posted record earnings, and asset management finally looked like a growth engine rather than a drag. Yet the shares have slipped about 4% since that report, trailing the S&P 500 by more than three percentage points. This quarter has to show that the reacceleration was a trend and not a one-quarter rebound.
The Street is looking for earnings of $1.45 a share, up about 7.4% from $1.35 a year ago and essentially flat with the prior quarter's $1.46. That is respectable, single-digit growth, a notch below the 10%-plus pace management targets over the medium term. Consensus revenue of $8.09 billion implies a roughly 10% decline, but for a life insurer reported revenue swings with investment marks and is a poor guide to underlying profitability. Management did not lift its medium-term objectives last quarter, only reaffirmed them, so there is no fresh guidance for analysts to anchor against. The bar is modest, and the real test is in the segment detail.
Start with US stop-loss, the business that caused last year's anxiety. Sales growth accelerated to 86% in the second quarter, and loss ratios held in the mid-70s. Rapid growth in a hardening market is attractive, but a bigger book also means larger swings in claims experience, and management flagged a seasonal reserve build. If loss ratios stay near the mid-70s while volumes keep climbing, the turnaround narrative firms up considerably. A drift higher would revive the pricing questions investors thought were settled. Group disability earnings, which fell from a record level a year earlier, and the dental business, now a structurally smaller Medicaid book with government sales that dropped to zero, are unlikely to help. The question is whether they stop getting worse.
Asia carries the most important tension. Sales rose 20% last quarter, yet new business contractual service margin fell 7% because competition in Hong Kong forced lower pricing. Management signaled that these thinner margins are the new normal. That makes this quarter's new business CSM worth more attention than headline sales. Stable margins with growing volume would suggest Asia can still compound value. Another leg down would imply the Hong Kong reset is not finished. Total CSM of $15.3 billion, up 12%, is the broader gauge of future earnings to track.
On the asset management side, the quarter brings the first contribution from Bell Partners, the US multifamily manager acquired largely with stock in July, alongside follow-through on Crescent's record $10.8 billion direct-lending raise. Management reaffirmed a roughly 20% earnings growth target for its alternatives platform, with margins moving toward the mid-30s, and a clean first look at the combined unit would lend that target credibility. At MFS, persistent active-equity outflows remain the offset to fast-growing ETF inflows. Capital also matters. Organic capital generation of 41% topped guidance, and a LICAT ratio of 145% leaves room for buybacks.
Sentiment has cooled, with bullish readings roughly halving from the prior quarter. That fits the stock's underperformance. At about $79, the shares sit comfortably above their 200-day average near $73, but they are mid-range since the last report, about 4% below the post-earnings high of roughly $83. In short, the market is not pricing in perfection. What decides this report is whether stop-loss claims stay contained while Asian new business margins stop eroding. If both hold, return on equity can keep moving toward 20% and the second-quarter reacceleration starts to look durable. If either slips, the market will treat the last quarter as the exception.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Oct-15 | |
| Oct-08 | |
| Sep-30 | |
| Sep-29 | |
| Sep-25 | |
| Sep-21 | |
| Sep-21 | |
| Sep-17 | |
| Aug-31 | |
| Aug-26 |
