Texas Pacific Land Faces Its Data Center Credibility Test As Shares Sink Toward Lows
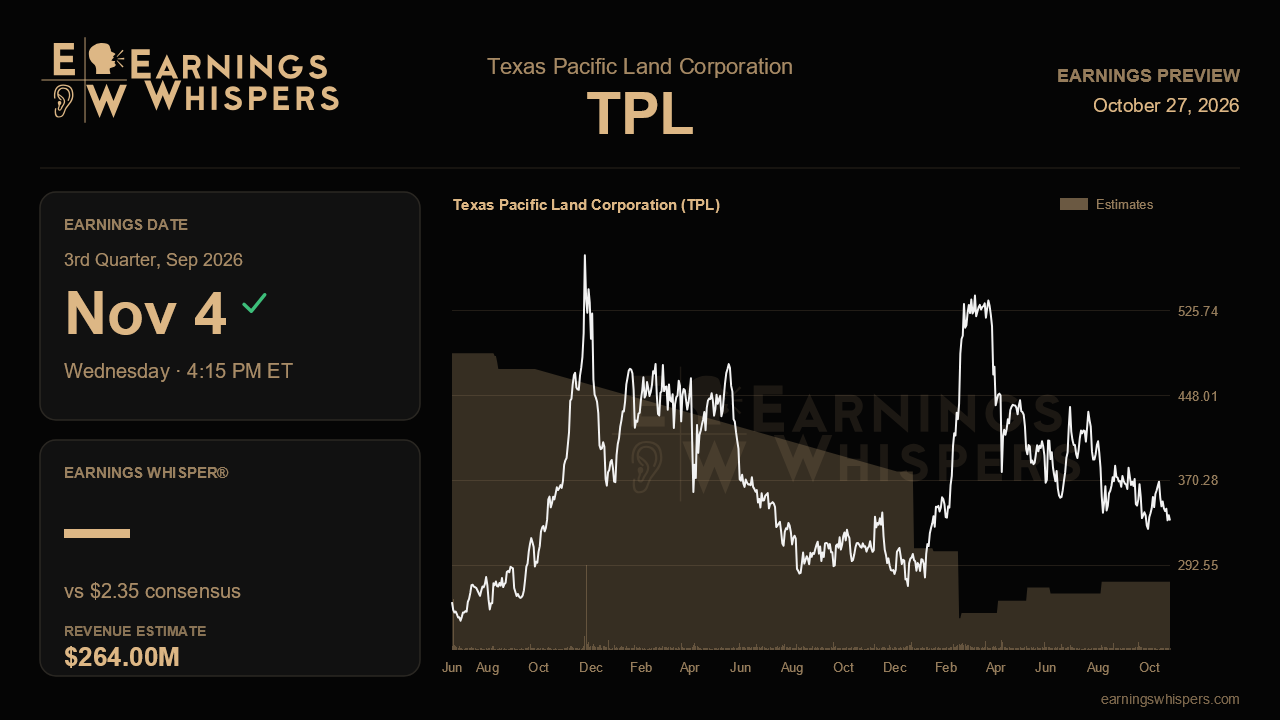
Texas Pacific Land enters its September-quarter report with an unusual disconnect. Last quarter's call was the most confident and specific in a year, as management finally put a name, Chevron's multi-gigawatt Project Kilby, on its data center ambitions. It also described advanced talks covering 25 gigawatts of projects and said it would be disappointed not to sign one or more definitive agreements soon. The stock has since fallen 15.4%, trailing the S&P 500 by nearly 15 percentage points. The market is effectively asking whether the company can show that this optionality is turning into contracts.
The Street expects revenue of about $264 million, up 30% from a year ago and roughly 7% above last quarter's record $246.1 million. Consensus EPS of $2.35 implies a 55% year-over-year decline. That figure is hard to square with 30% revenue growth at a business running adjusted EBITDA margins near 88%, so the year-ago comparison does not appear to be on a like-for-like basis. The cleaner benchmark is last quarter's $2.23, which makes the bar a modest sequential gain. The company has not issued formal earnings guidance. Its only standing target is full-year capital spending of $65 million to $75 million, which was reaffirmed rather than raised.
The legacy engine looks well positioned to clear that bar. Royalty production hit a record 39,700 barrels of oil equivalent per day last quarter, and produced water royalty volumes reached 4.9 million barrels per day. Because the company is unhedged, it keeps all of any price upside. Three swing factors matter most. The first is oil cut, which slipped to the mid-30% range. The CFO blamed acquisition accounting and gas-heavy drilling and expects a return toward 40% or more. A rebound would lift revenue per barrel even if volumes plateau. The second is water sales, which fell 19% sequentially as weak in-basin gas prices pushed drilling away from the Delaware. Management tied the recovery to new pipeline capacity arriving over coming quarters, so another sequential drop would test that timeline. The third is line-of-sight net wells, which eased to 18.4 as the basin worked down its backlog of drilled but uncompleted wells. Stabilization there would ease worries about 2027 volumes.
The bigger story is the next-generation pipeline. Kilby was disclosed, but no new hyperscaler or power agreement has been signed. This report is the first real checkpoint on management's near-term deal language. A signed contract, or concrete economics on the roughly $100 million Shackelford and Jones county land purchase, would validate the narrative. Progress on the Orla Phase 2B desalination plant and its chip-cooling studies would also help. Another quarter of advanced conversations without a signature would not break the thesis. It would, however, sharpen questions about timing, especially with buybacks paused so cash can build for acquisitions.
Sentiment has swung from mildly bearish before the last report to clearly bullish now, even as the share price moved the other way. At $333.46, the stock sits well below its 200-day moving average of about $401. It is also less than 3% above its post-earnings low of $324.80. The whole post-report range has traded beneath the prior quarter's band, which reached as high as $454.84. Optimistic chatter meeting a technically weak chart suggests holders want proof, not promises.
The royalty and water franchise will probably deliver numbers near or above consensus. That alone may not be enough. The central question is whether management can show that its data center and power strategy is moving from conversations to contracts. If it can, the recent selloff looks like an opportunity. If the deal timeline keeps slipping, the market may keep valuing Texas Pacific Land as a strong royalty company with an expensive story attached.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-13 | |
| Oct-08 | |
| Aug-11 | |
| Aug-11 | |
| Aug-09 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-15 | |
| Jun-23 | |
| Jun-03 | |
| May-15 | |
| May-15 | |
| May-06 |
