Vertex Heads Into Q3 Needing Cloud And E-Invoicing Proof After 25% Rally
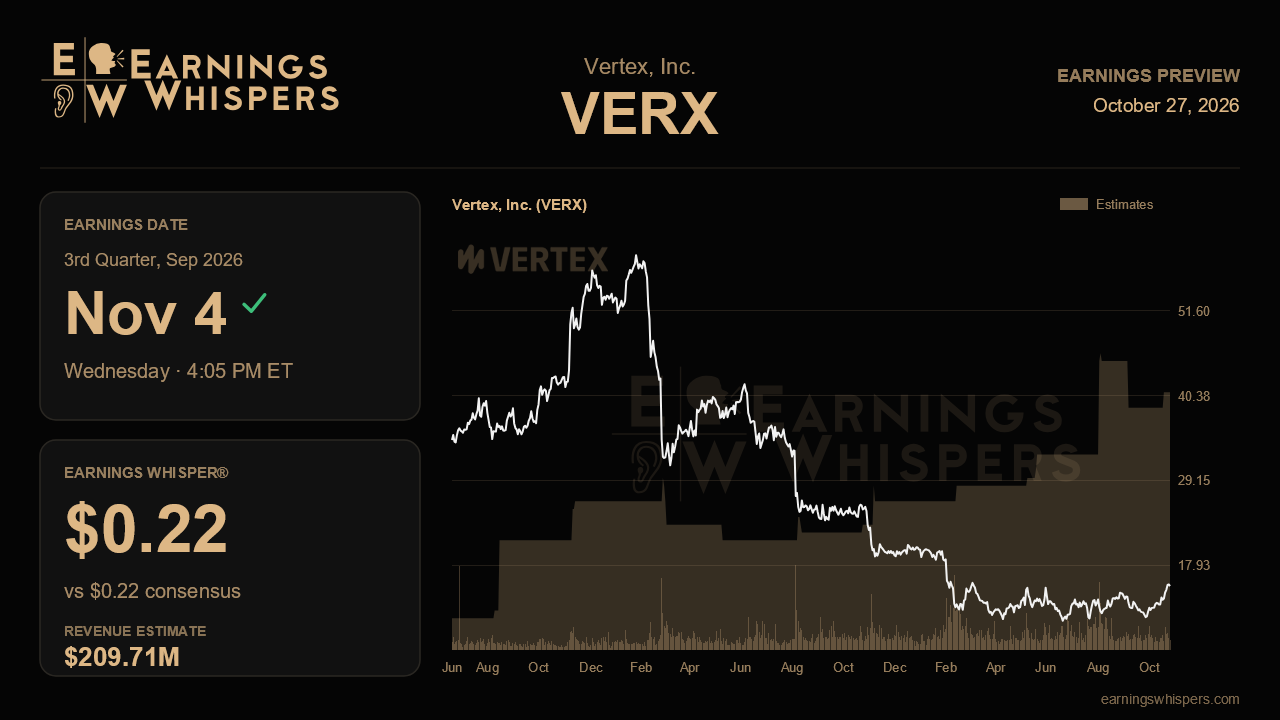
Vertex enters its third-quarter report with a stock that has already priced in a good deal of forgiveness. Since its last update, when management sliced its full-year cloud growth target from 25% to 18% while raising its profit outlook yet again, shares have climbed about 25% against a roughly flat S&P 500. The market evidently decided the margin story outweighed the growth reset. The report due after the close on November 4 will show whether that judgment holds, or whether the top line is still drifting.
The Street is looking for non-GAAP earnings of $0.22 per share, double the $0.11 earned a year ago, on revenue of about $209.7 million. The Earnings Whisper matches consensus at $0.22, so there is no hidden expectation for a blowout. The revenue estimate sits almost exactly at the midpoint of management's $208 million to $211 million guidance, and it implies growth of roughly 9.2%. That is a step down from the 10.5% Vertex posted in the second quarter and lands at the bottom edge of the low-double-digit growth framework management asked investors to underwrite earlier this year. A clean beat would mean pushing toward the top of the range, as Vertex has done for three straight quarters. A print merely at the midpoint would technically be in line but would confirm deceleration.
The most important number may not be total revenue but cloud growth. Cloud expanded 17.9% in the second quarter, down from 20.7% in the first, as conversions of on-premise customers ran slower than planned. Management characterized this as timing, with revenue moving from one pocket to another rather than disappearing. If cloud growth holds near the new 18% target or ticks higher, that explanation gains credibility. Another slide would suggest the cut was not the floor, and would raise uncomfortable questions about the full-year revenue range, which was narrowed to $825 million to $830 million rather than raised.
E-invoicing is the catalyst carrying the bull case. France's mandate took effect in September, inside this quarter, and Germany follows in January 2027. Last quarter Vertex cited several six-figure enterprise wins, including a mid-six-figure France and Finland deal, plus emerging cross-sell into its installed base. This report should offer the first read on whether a live mandate translates into accelerating bookings and onboarding, and whether the German pipeline is filling as fast as management suggested. Closely related is the seven-figure new-logo deal that slipped from June into July; confirmation that it closed would help ease concerns about elongating sales cycles. Scaled customer growth, which slowed to 8% from 12%, and net revenue retention, stuck at 105% for two quarters, are the metrics that will reveal whether expansion is finally improving or still lagging internal targets.
On profitability, the bar is higher than it looks. Management lifted its adjusted EBITDA outlook twice this year, most recently to $206 million to $210 million, helped by an April restructuring that cut roughly 9% of staff. Investors now expect margins near the 25% reached last quarter to persist, and another raise would be welcome, though an unchanged range would hardly be alarming given the cost savings are slated to fully arrive in 2027.
Sentiment has softened from deeply negative, moving from 55.2% bearish before the last report to 27.5% bearish now. The stock trades at $15.17, comfortably above its 200-day average of $13.42 and within about 2% of its post-earnings high of $15.52, effectively testing a breakout. That leaves less room for ambiguity. The narrative that Vertex can trade growth for margin while its revenue stabilizes remains intact only if cloud growth stops sliding and e-invoicing demand shows up in the numbers. Profit upside alone may not be enough to carry the stock through its recent highs.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Oct-15 | |
| Oct-15 | |
| Oct-09 | |
| Oct-01 | |
| Sep-03 | |
| Aug-13 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-30 | |
| Jul-16 |
