TWFG's Florida Windfall Meets Its First Tough Comparison As Q3 Tests Raised Guidance
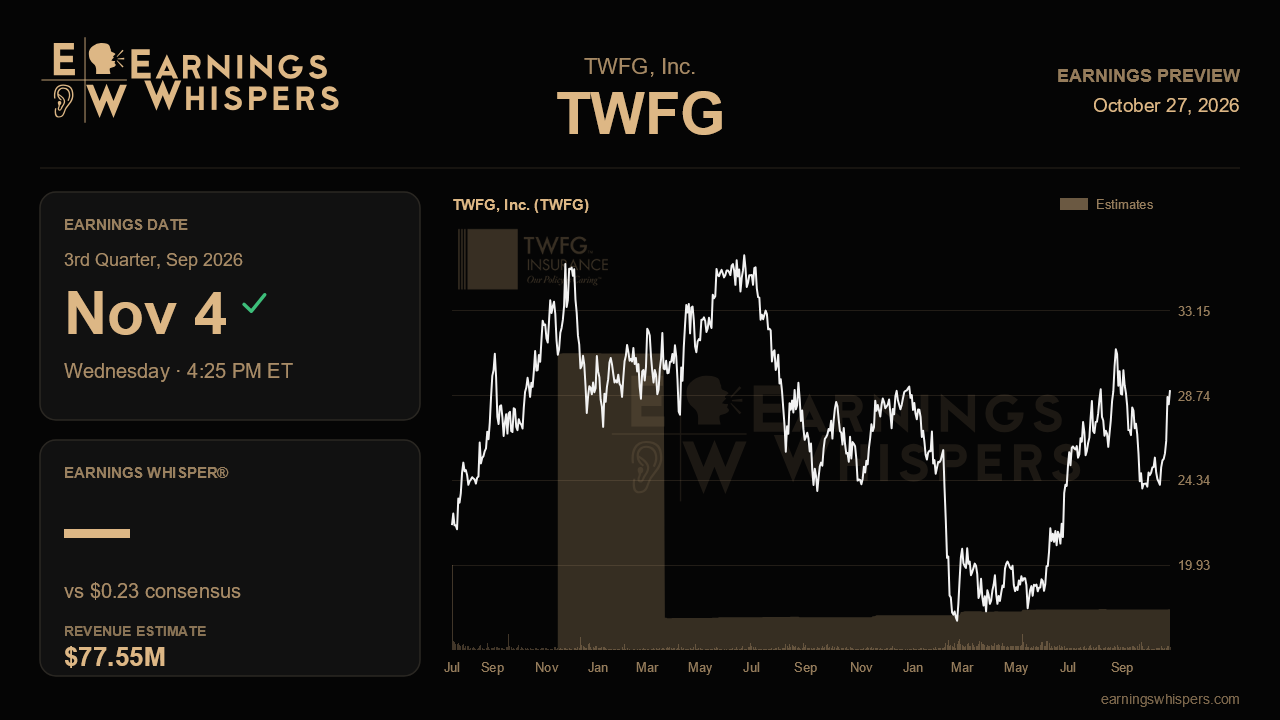
TWFG heads into its third-quarter report having just delivered what management called its best quarter yet, and that is exactly what makes this one tricky. The second quarter's 37% reported organic growth and 30.4% adjusted EBITDA margin were inflated by Florida takeout policies at its managing general agency, business that earned commissions without matching commission expense during runoff. Management said plainly that this tailwind would fade and that prior-year takeout volume, concentrated in the third and fourth quarters of 2025, would not repeat. The September quarter is where that normalization starts to show up in the numbers, and the question is how gracefully.
The Street expects earnings of $0.23 per share on revenue of $77.6 million, up roughly 28% and 21% from a year ago, respectively. That is still strong growth for an insurance distributor, but it implies a clear step down from the second quarter's $87.5 million in revenue and $0.31 in EPS. Consensus appears to have absorbed management's warning rather than extrapolated the spring surge. Against full-year guidance of $300 million to $320 million in revenue, 13% to 17% organic growth and a 23% to 27% adjusted EBITDA margin, a quarter in line with estimates keeps the company comfortably on track. The buyback, which retired about 15% of Class A shares at roughly $19, also gives per-share earnings a cushion that revenue alone does not.
The more revealing evidence lies beneath the headline figures. Management argued that the MGA's growth is becoming structural rather than episodic, pointing to a Florida voluntary homeowners program that stands apart from Citizens takeouts, along with other MGA platforms. If MGA commission income holds a meaningful share of revenue even as takeout economics normalize, that claim gains credibility. Ex-Florida core organic growth, which ran in the high teens last quarter, is the cleanest gauge of the underlying franchise. Retention, which hit a record 93%, matters too, because a softening rate environment, with personal auto premiums declining in the mid-single digits and homeowners flat, means policy count growth must do more of the work. Any slippage in retention would challenge the bullish narrative more than a modest revenue miss.
There are also two upside levers management flagged but did not bake into guidance. Contingent commissions were held flat at $2.2 million on a deliberately cautious assumption that carrier loss ratios would deteriorate, something that had not yet happened. With third-quarter results locked in, management promised an update, and a better-than-feared loss picture could lift the full-year view. Additional acquisitions beyond the completed Fortress deal in Iowa would be the second lever. Whether management raises guidance again or simply reaffirms will say a lot about its confidence heading into a fourth quarter it expects to show roughly flat organic growth.
The market's mood has cooled even as the stock held up. Sentiment has grown more bearish than it was before the last report, yet shares are up about 2% since then while the S&P 500 slipped, and at $29.03 the stock trades well above its 200-day moving average of $23.13. It sits about 7% below its post-earnings high of $31.30, so this is not a breakout setup, but the range has shifted decisively higher than last quarter's. An investor day on November 12, where management plans to lay out a medium-term financial framework, adds weight to any commentary this quarter.
Ultimately, this report hinges on whether TWFG can show that its accelerated growth survives the fading of the Florida takeout windfall. Solid core organic growth, steady retention and margins landing comfortably within the raised range would validate management's confident turn. A sharper-than-expected margin reset or softening ex-Florida momentum would suggest last quarter was more peak than platform.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Aug-13 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-30 | |
| Jul-29 | |
| Jun-08 | |
| May-27 | |
| May-12 | |
| May-07 | |
| May-06 |
