Titan America Must Prove Florida's Margin Squeeze Was Temporary As Keystone Lifts Sales
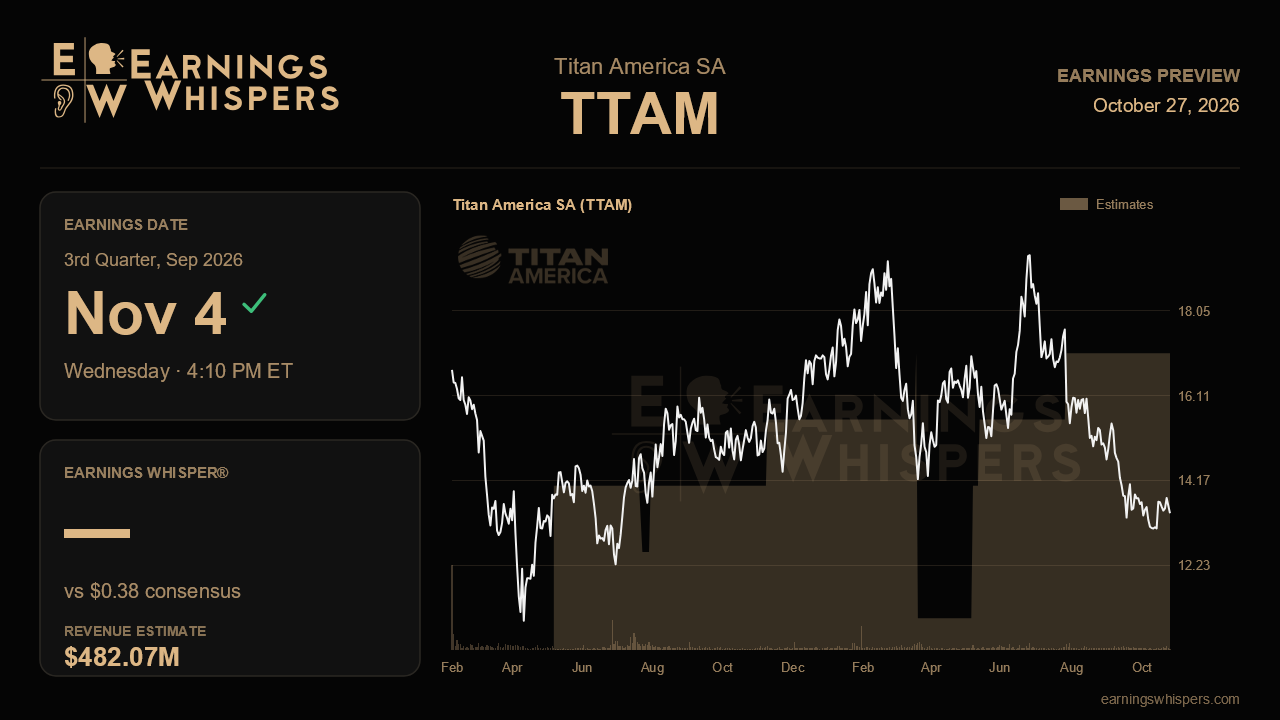
Titan America heads into its third-quarter report with a stock that has already priced in plenty of bad news. Shares have dropped 23% since the last report, while the S&P 500 gained 3.4%. The reason is not hard to find. Last quarter management raised its revenue outlook but cut its margin outlook for the first time in this cycle. The coming release should show whether that cut was a one-time stumble tied to Florida or the start of a longer slide in profitability.
The Street expects earnings of $0.38 per share on revenue of $482.1 million. That would mean EPS growth of about 23% and sales growth of roughly 10% from a year ago. On the surface, those are strong numbers. The revenue gain, however, largely reflects the first full quarter of the Keystone Cement acquisition, which added about $20 million in its partial debut. Management was clear that the higher full-year revenue target is about consolidation, not organic growth. The company now expects 2026 revenue of about $1.79 billion, up from about $1.71 billion. Notably, the full-year consensus of $1.76 billion sits below that new figure. Analysts appear to be giving the company only partial credit for its own forecast.
The earnings bar is the more demanding one. EPS has to climb from $0.23 last quarter to $0.38, at a time when Keystone weighs on margins. Keystone started with an EBITDA margin of roughly 10%, which is why management now guides to a full-year margin decline of about 25 to 50 basis points rather than the modest expansion it had promised for several quarters. To reach consensus, Florida likely has to recover meaningfully. In the second quarter, the extended Pensuco maintenance outage and Mediterranean import disruptions cost about $7 million combined. They pushed Florida's segment margin down to 19.7% from 23.8%. Management framed both problems as transitory and described the second half as improving. This report is the first real test of that claim. A rebound in Florida margins toward prior-year levels would support it. Continued weakness, especially if higher sea freight costs on uncontracted imports show up, would suggest the margin reset runs deeper.
Pricing is the other swing factor. Cement prices slipped 1.5% from a year earlier last quarter, after holding flat in the first quarter, because of softness in Florida. Further erosion would be a troubling sign in an industry where pricing discipline usually drives earnings. Ready-mix pricing, by contrast, rose 4.4%. The Mid-Atlantic remains the strongest part of the story: revenue jumped 27% on data-center and nonresidential demand, and segment margins edged higher. Management says the company is supplying 77 of the 148 data centers under construction in Virginia. Steady growth there would show that the best part of the portfolio is still strong while Florida recovers. Early signs of progress on Keystone integration toward the target of at least $30 million in synergies by 2029 would also help. So would steady cash generation, since leverage jumped to 1.37 times after the deal.
Sentiment has swung sharply, from a mildly bullish reading before the last report to clearly bearish now. The chart tells the same story. At $13.42, the stock trades well below its 200-day moving average of $16.10 and sits near the bottom of its post-earnings range, about 4% above the $12.88 low. That pessimism lowers the bar for a relief rally. It also means a second disappointing margin print could break support.
In the end, the quarter will turn on whether the margin outlook cut last quarter holds or slips again. If Florida margins rebound and the 25 to 50 basis point decline still looks realistic, the bearish view will look overdone. If the company has to widen that range, the higher revenue forecast will offer little comfort.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Oct-01 | |
| Sep-08 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-14 | |
| Jun-22 | |
| May-27 | |
| May-05 | |
| May-05 | |
| May-05 |
