NRC Health Matches EPS View As Revenue Accelerates, But Slowing TRCV And A CFO Exit Cloud The Setup
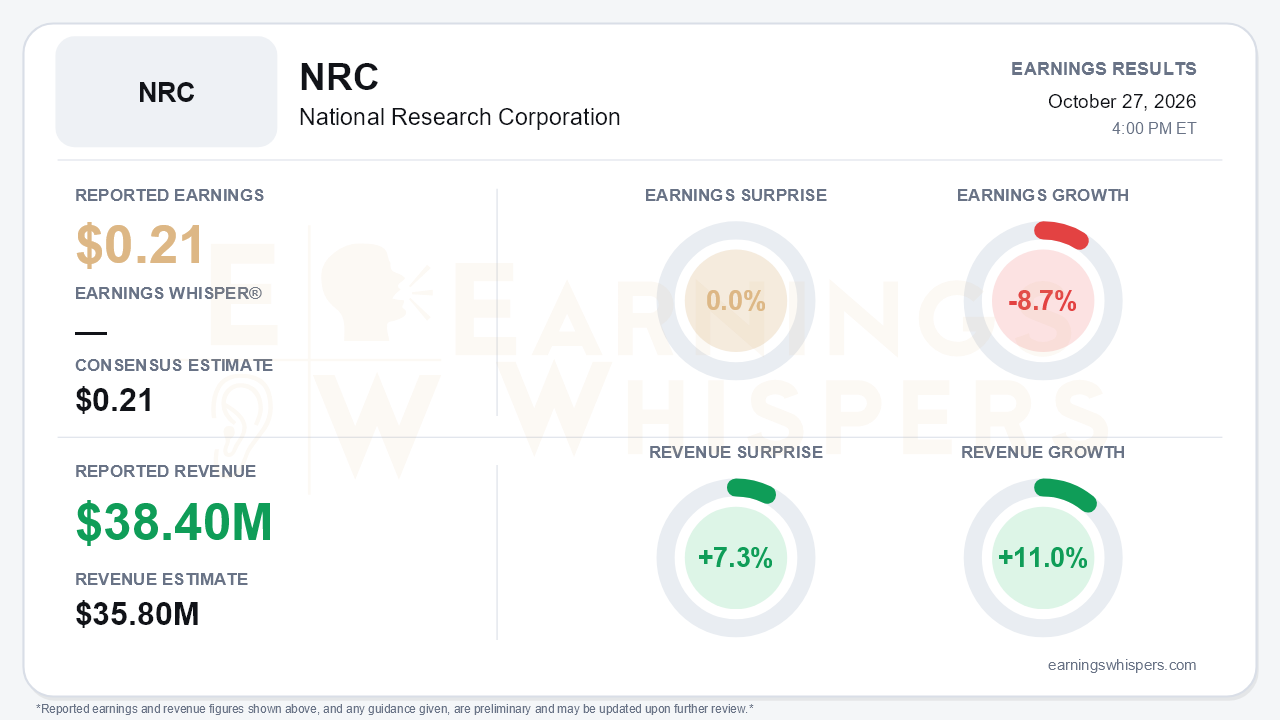
National Research Corporation (NRC Health) delivered the revenue acceleration bulls were waiting for, but the quarter's forward-looking indicators moved the other way. The company reported third-quarter earnings of $0.21 per share, in line with the $0.21 consensus estimate, on revenue of $38.4 million, which topped the $35.8 million consensus by 7.3%. Revenue grew 11.0% year over year, a clear step up from 4% growth in the first quarter and a 5% decline in the fourth quarter of 2025. Earnings still fell 8.7% from a year ago. That is the central tension: the top line is improving, but the contract base that should feed future revenue is decelerating, and margins have not yet caught up.
The quality of the quarter deserves scrutiny. GAAP diluted EPS rose to $0.21 from $0.18, but much of that gain reflects a $134,000 stock-compensation benefit, compared with a $925,000 expense a year ago. On an adjusted basis, which strips out stock compensation, EPS slipped to $0.21 from $0.23. Adjusted EBITDA was essentially flat at $10.9 million, and its margin fell to 28% from 31% as direct costs rose to $15.4 million from $12.4 million. Cash generation also softened. Operating cash flow dropped to $8.0 million from $13.8 million, largely because of a $6.0 million receivables build. Free cash flow of $7.0 million trailed the prior year's $10.2 million despite a sharp cut in capital spending.
The conference call offered a credible explanation for the margin pressure. Management said moving the HUB conference into the third quarter cost about 4 points of margin. Even with that drag, adjusted EBITDA margin improved sequentially from 27%, delivering on the earlier promise that margins would expand starting in the third quarter. Management also expects further sequential margin improvement in the fourth quarter. The large multi-solution customer went live on schedule in July and contributed a full quarter of revenue. Notably, management said that implementation drove less than half of the year-over-year growth, with the rest coming from broader demand. Supporting that claim:
- Market Insights posted its strongest sales quarter since before the pandemic.
- The Governance Institute is tracking toward its best sales year in more than a decade.
- Several long-standing customers converted from annual to multi-year agreements.
Bears have legitimate ammunition, however. Total Recurring Contract Value, which management treats as a leading indicator of revenue, grew 9% to $154.1 million. That is down from 13% growth in the first quarter and means only about $2 million was added over two quarters. Management acknowledged fewer experience-management RFPs in the market this year. The CEO also described phase 2 (rounding) revenue from the landmark deal as a "much smaller" base than phase 1. That conflicts with earlier framing of roughly half the annualized revenue each, and phase 2 revenue may lag its third-quarter 2027 go-live. Adding to the uncertainty, CFO Shane Harrison has departed about a year after joining, and management layered on caveats that progress will not be linear and that fourth-quarter seasonality should not be treated as a run rate.
Capital allocation is becoming a bigger part of the story. NRC repurchased about 790,000 shares for roughly $16.0 million in the quarter and paid $3.5 million in dividends. Those outlays exceeded free cash flow and were supported by $15 million of new term borrowing. Long-term notes payable climbed to $98.1 million from $75.0 million at year-end. Cash stood at just $3.6 million, and shareholders' equity has turned negative at $9.1 million. The board maintained the $0.16 quarterly dividend. That leaves less room for error if TRCV growth keeps fading.
The market setup is more complicated than the in-line print implies. Investor sentiment entering the report was negative at about -0.30, suggesting skepticism despite the revenue recovery. The shares closed at $22.45 before the release, essentially unchanged (-0.6%) from the $22.58 open after the July report. The post-July session was extraordinarily volatile, with the stock trading as low as $17.88 and as high as a 52-week high of $23.68 that same day. Shares have since held near the upper end of that range, 5.2% below the high and about 17% above the 200-day moving average. The Earnings Whispers trend readings lean constructive, with sequential growth and AVWAP positive while price trend is neutral.
The bottom line is that NRC Health showed real revenue acceleration and a credible path to sequential margin gains, but the leading indicators softened. Decelerating TRCV, a smaller-than-expected phase 2 opportunity, thinner RFP activity and a CFO vacancy all weigh against the improvement, and a debt-funded buyback narrows the margin for disappointment. Until contract value growth reaccelerates, the revenue beat looks more like a strong implementation quarter than proof of a durable growth inflection.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-15 | |
| Sep-25 | |
| Sep-21 | |
| Sep-02 | |
| Sep-01 | |
| Sep-01 | |
| Jul-30 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| May-28 | |
| May-19 |
