Chiron's Seniors Housing Pivot Faces Its Earnings Valley As Consensus Braces For Steep Drop
Chiron Real Estate has spent the past few months proving it can close deals. The quarter it reports after the bell on November 4 is the first real test of how much those deals cost the income statement in the meantime. The former Global Medical REIT is selling stabilized outpatient medical buildings and recycling the proceeds into luxury seniors housing. Management has openly acknowledged that this swap creates a dilutive valley before the new communities stabilize in 2027 or 2028. The question now is how deep that valley gets, and whether the market has already priced in the worst of it.
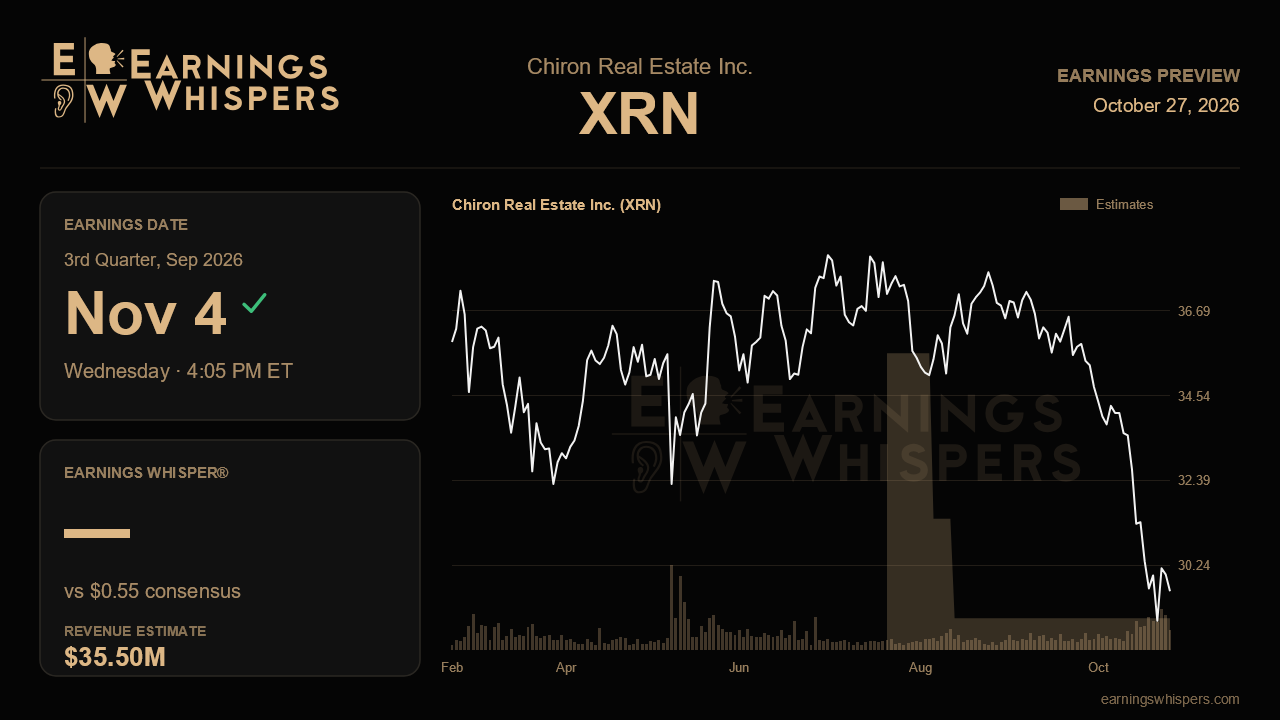
The Street is bracing for a sharp step down. Consensus calls for $0.55 a share on revenue of about $35.5 million. Last quarter the company posted $0.88 on $39.7 million. That implies a sequential revenue decline of roughly 11% and a per-share drop of more than a third. Much of that reflects the closing of the inpatient rehabilitation joint venture at $217 million and a 7.3% exit cap, along with the pending $49 million sale of the Beaumont surgical hospital. Both remove rent-paying assets, while the seniors communities that replace them are still leasing up. There is no formal guidepost to measure against. The full-year core FFO range of $4.30 to $4.45 set early in the cycle was pulled in the first quarter and was not restored last time. That leaves analysts modeling a business mid-transformation without management's numbers to anchor them.
The prior call gave investors a clear checklist. On the positive side, the company closed its first two seniors communities, The Landing and The Riviera, with 292 homes, along with the $100 million MayWin convertible preferred. It also reported $421 million of seniors investment activity and cut net debt to EBITDA to 6.0x from 6.6x. Validation this quarter would mean early occupancy progress at those communities and at Pinnacle, which welcomed its first residents in June. It would also mean the Beaumont sale closing on terms and some visibility on the broader outpatient portfolio that a broker is now marketing. The challenge is in the core numbers. Core FFO has slipped from $1.16 to $1.11 to $1.04 over three quarters. Same-store cash NOI growth has faded from 5.4% to 3.2% to just 0.8% reported. A further slide toward flat or negative same-store growth would suggest the legacy portfolio is weakening on its own, beyond the shrinkage from planned sales. That is a different and more worrying story than intentional dilution. Higher G&A from the expanded seniors leadership team and the lingering White Rock tenant bankruptcy are additional swing factors.
Governance deserves attention too. Chief investment officer Alfonso Leon left the week of the last call, just as a new bench including Matthew Whitlock, Bobby Zeiler and Aaron Roseth arrived. Any additional turnover, or vagueness about who owns the acquisition pipeline, would undercut management's insistence that this phase is about execution rather than aspiration.
The market has not been patient. Shares have fallen about 17% since the last report while the S&P 500 was roughly flat. At $29.58, the stock sits well below its 200-day moving average near $35.39 and within about 3% of its post-earnings low of $28.63. Sentiment is mildly bearish and barely changed from last quarter, so skepticism looks entrenched rather than newly formed. A depressed price and a low per-share bar give Chiron some room to surprise. They also mean a disappointing occupancy update could push the stock through support.
Ultimately, this report hinges on whether the decline in earnings looks like a controlled, temporary trough or an open-ended erosion. If seniors lease-up is tracking, asset sales are closing at the cap rates promised, and same-store results in the remaining medical portfolio stabilize, the pivot thesis holds. If those signals blur while guidance stays withdrawn, investors may keep demanding a steeper discount for the wait.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-19 | |
| Oct-07 | |
| Sep-21 | |
| Aug-26 | |
| Aug-18 | |
| Aug-05 | |
| Aug-05 | |
| Aug-03 | |
| Aug-03 | |
| Jul-16 | |
| Jul-14 | |
| Jun-30 | |
| Jun-01 | |
| Jun-01 |
