Ultragenyx Faces A Credibility Test As Catalyst Season Collides With A 43% Selloff
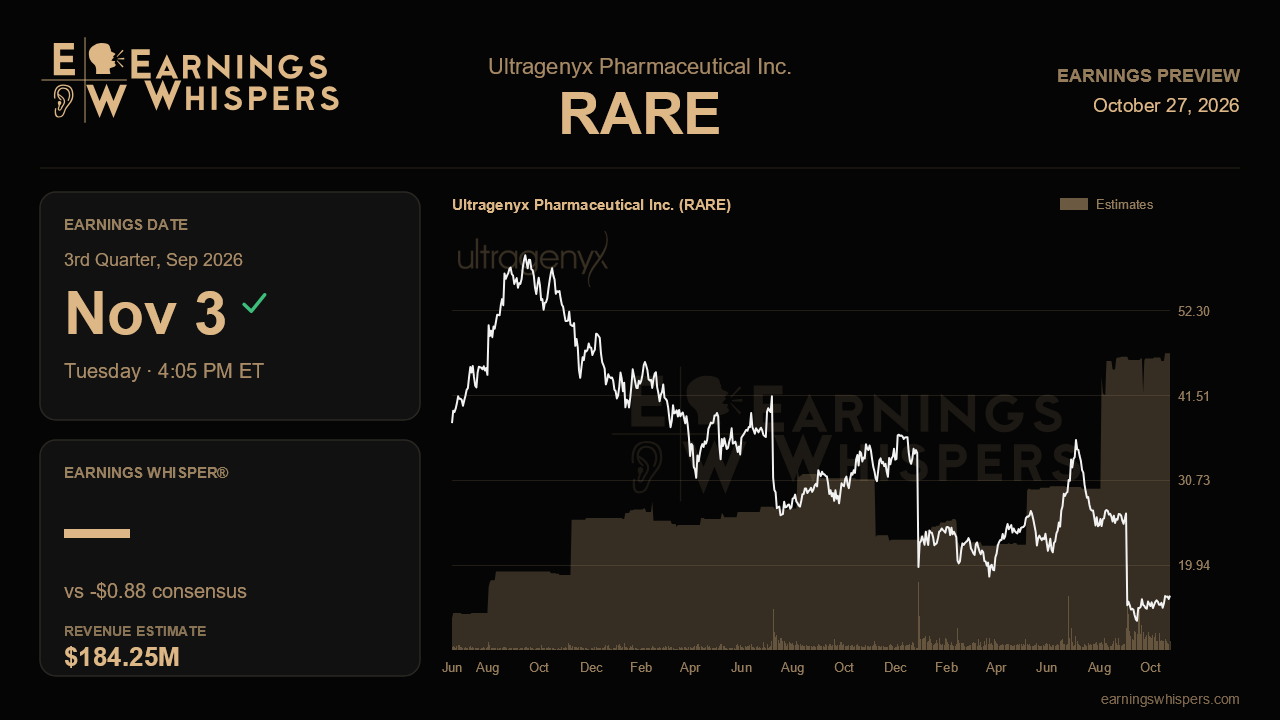
Three months ago, Ultragenyx management described the second half of 2026 as the most consequential stretch in the company's history. They pointed to two gene therapy approval decisions and a pivotal Angelman syndrome readout, all scheduled ahead of this report. The market has since rendered a harsh verdict. Shares have fallen 43.5% since the last report while the S&P 500 slipped just 1.4%. When Ultragenyx reports third-quarter results after the close on November 3, the quarterly numbers will matter less than whether management can show its 2027 profitability plan still holds together.
The Street expects a loss of $0.88 per share, a sharp improvement from the $1.81 loss a year ago and roughly in line with last quarter's $0.90 loss. Revenue is projected at $184.3 million, up 15.2% from a year earlier. That is solid but not spectacular growth, and it would mark a step down from the record $214 million posted in the second quarter. The sequential dip should not alarm anyone familiar with the company's Crispita ordering pattern, which swung from $93 million in the first quarter to $156 million in the second. Still, the size of the third-quarter number matters for the full-year math. Management has reaffirmed 2026 revenue guidance of $730 million to $760 million, and consensus of about $746.7 million sits in the upper half of that range. With $350 million booked in the first half, a third quarter near consensus would leave the company needing roughly $212 million in the fourth quarter. That is achievable but leaves little cushion if Crispita timing slips.
The operating details to examine are the ones management highlighted last time. Evkiza grew 50% year over year to $21 million in the second quarter, and continued growth near that pace would support the case that the base business is broadening. Latin American Crispita patients reached 1,000. Further gains there, along with early signs from the Japan launch and expansion into the Middle East, would confirm that demand is still building. A stall in either product would undercut the main argument for owning the stock while the pipeline remains in doubt.
The balance sheet may be the most important line in the release. Cash fell to $436 million at the end of June from $738 million at the end of 2025. Management's path to profitability depends on successful gene therapy launches and on selling priority review vouchers, each potentially worth $100 million or more, which are awarded upon approval. Investors need a clear account of where the DTX401 and UX111 decisions landed, whether any voucher sale is in hand or in progress, and how payer contracting has gone. Management cited more than 200 payer engagements last quarter. Operating cash burn of $97 million in the second quarter was a meaningful improvement. Another quarter near that level would ease funding concerns, while a return toward the first quarter's $197 million would sharpen them. Updates on the stalled citruzumab program, which may require a new randomized trial, will also shape views of future spending.
Sentiment has turned modestly bullish, moving from a clearly bearish reading before the last report. This suggests some investors see value after the drawdown. The chart is less encouraging. At $16.08, the stock trades well below its 200-day moving average of $23.09 and sits in the lower third of its post-earnings range of $12.73 to $28.50, a range that sits entirely beneath the prior quarter's.
Ultimately, this report is about whether the 2027 profitability story survived catalyst season. If management can pair steady commercial growth and full-year guidance with a credible funding plan, the selloff may look excessive. If cash needs appear larger or launch timelines appear longer, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-14 | |
| Oct-09 | |
| Oct-07 | |
| Oct-07 | |
| Oct-07 | |
| Oct-07 | |
| Oct-02 | |
| Sep-22 | |
| Sep-18 | |
| Sep-18 | |
| Sep-17 | |
| Sep-17 | |
| Sep-17 |
