Zevia's Third Quarter Tests Whether Margin Squeeze Stays Contained As New CEO Resets Strategy
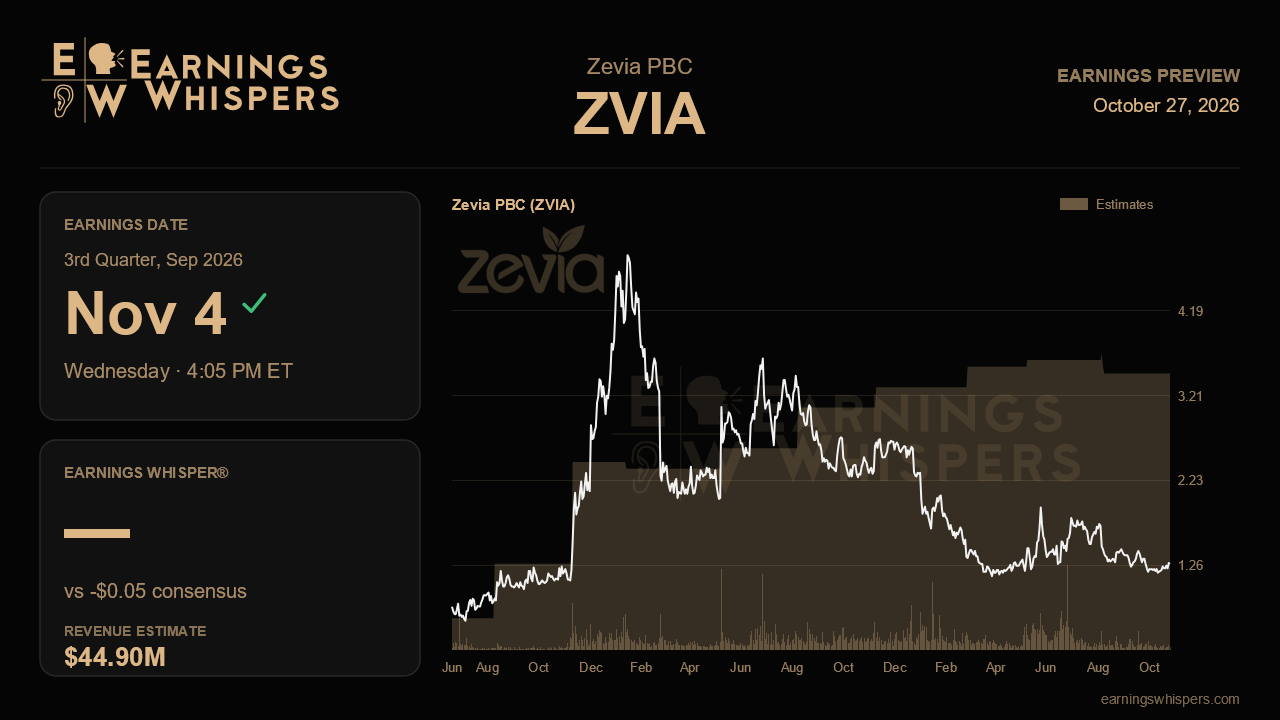
Zevia heads into its third-quarter report with an unusual setup: management has already told investors this will be a rough quarter for profitability, and the stock has been marked down hard anyway. The real question on November 4 is not whether the zero-sugar soda maker loses money. It almost certainly will. The question is whether the damage lands where new CEO Alexandre Ruberti said it would, and whether he offers enough of a roadmap to make investors look past it toward 2027.
The Street expects a loss of 5 cents a share, wider than the 4-cent loss a year ago, on revenue of about $44.9 million. That top line would be up roughly 10% from $40.8 million, a healthy rebound from the near-stall of the second quarter, when sales rose just 1.1% after a 21% jump in the first quarter. Consensus sits almost exactly at the midpoint of management's $44 million to $46 million guidance, so the revenue bar is neither demanding nor sandbagged. A print near the top of the range would suggest the second-quarter slowdown really was about lapping Walgreens and Albertsons load-ins and shipment timing. A result near the bottom would revive concerns that underlying demand is cooling, particularly with the discontinued tea line already shaving about 1.5 points off full-year growth.
Profitability is where the quarter gets uncomfortable. Management guided gross margin down to roughly 46% from 48.9% in the second quarter, citing elevated aluminum costs, deeper promotions and channel mix, and called for an adjusted EBITDA loss of $3.0 million to $3.5 million after two straight quarters of small positive EBITDA. The roughly $11 million full-year fuel and aluminum headwind was always weighted to the back half, and this is where it shows up. Meeting those targets would validate that the company has its cost picture under control. Any slippage beyond the guided range, or signs that promotional spending is rising to defend shelf space, would challenge the idea that the $20 million of cost cuts already made, plus another $3 million to $5 million beginning next year, can offset commodity pressure.
The full-year outlook also deserves scrutiny. With first-half sales of $91.1 million, the reaffirmed $170 million to $175 million range implies a flat-to-down fourth quarter. Holding that guide would be steadying. Trimming it would undercut the new leadership team before its plan is even public. Ruberti promised a strategic plan with measurable milestones in the coming months, and any detail on the go-to-market overhaul, the mix of direct store delivery, brokers and broadliners, and the push into singles, where Zevia holds essentially no share against an opportunity sized at about $80 million, would give investors something concrete. Early read-throughs on retailer interest in the Cardi B signature product slated for January would help show whether the campaign's enormous social reach is translating into commercial traction.
The market has not been patient. Shares have fallen about 22% since the last report while the S&P 500 was roughly flat, and at $1.27 the stock sits below its 200-day moving average of $1.44 and not far above the $1.15 floor that has held through both this quarter and the last. Curiously, sentiment has swung from mildly bearish ahead of the prior report to moderately bullish now, suggesting some investors view the selloff as having priced in the guided weakness. A cash balance of $28.5 million, up for two straight quarters, gives the company room to execute without immediate balance-sheet anxiety.
Ultimately, this report hinges on credibility. Ruberti candidly said in-store execution needs work and that growth initiatives will take time. If the quarter lands within guidance, the annual outlook holds, and the 2027 plan begins to take shape, the narrative of a deliberate reset stays intact. If margins erode further or revenue drifts low, the market may conclude the reset is a longer and costlier road than promised.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Aug-19 | |
| Aug-17 | |
| Aug-14 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-22 | |
| Jul-21 | |
| Jun-16 |
