Intapp Beats And Raises As Celeste Bookings Surge, But Slowing ARR And RPO Temper A Crowded Rally
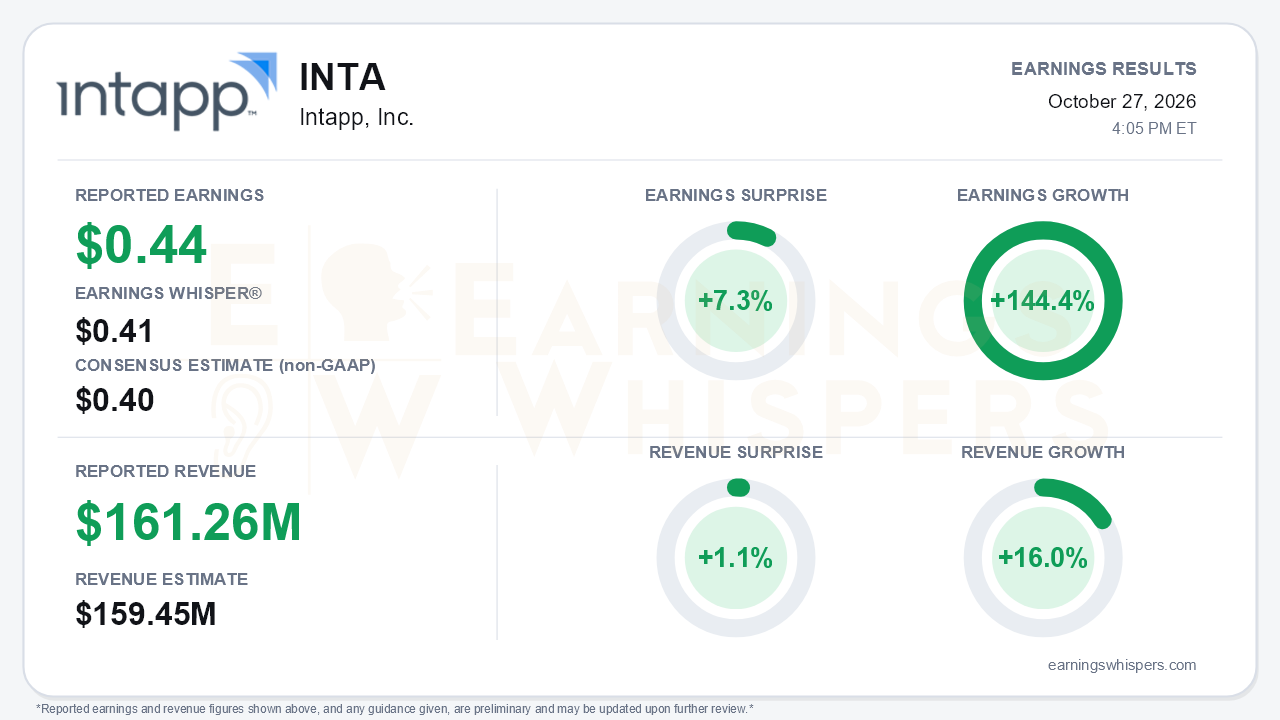
Intapp delivered a clean beat-and-raise for its fiscal first quarter, but the AI story is running ahead of the recurring-revenue metrics that will eventually have to validate it. Non-GAAP EPS of $0.44 topped the $0.40 consensus and the $0.41 Earnings Whisper by 7.3% and grew 144.4% year over year. Revenue of $161.26 million beat the $159.45 million consensus by 1.1% and grew 16.0%. Subscription revenue rose 29% to $125.5 million, accelerating from 27% in the fourth quarter. Management raised full-year guidance across the board, although the increase was in line with estimates. The central tension: Firm AI is quickly becoming the dominant source of new business, while cloud ARR, total ARR and remaining performance obligations continue to decelerate.
The profit improvement is real, but its quality needs some context. Non-GAAP gross margin expanded to 80.4% from 77.7% a year ago and 79.4% last quarter. Non-GAAP operating income reached $35.4 million, roughly a 22% margin, up from $20.9 million. On a GAAP basis, the operating loss narrowed to just $1.1 million from $14.5 million, and the net loss per share shrank to $0.02 from $0.18. Free cash flow more than doubled to $28.1 million. However, two factors flatter the per-share growth. First, the diluted non-GAAP share count fell to 78.7 million from 84.4 million after aggressive buybacks. Second, stock-based compensation rose to $33.1 million from $27.3 million and is guided at $138.1 million for the year. The repurchases have also been costly. Cash has fallen to $147.7 million from more than $313 million at the start of the prior fiscal year, and only $50 million of repurchase authorization remains.
The operating narrative on the call was decidedly more confident. Celeste became generally available in July, followed by Compliance with Celeste and Time with Celeste in August. AI products accounted for more than 40% of net new bookings, up from more than 20% in the fourth quarter and about 15% the quarter before. The Celeste pipeline rose about 2.5x sequentially, and roughly 200 enterprise firms are running the product ahead of subscribing. Intapp also closed one of the largest deals in its history, a cloud migration plus Celeste at a top-10 global law firm. Cloud net revenue retention held at 123%. The ecosystem also widened through:
- the Legora partnership;
- general availability of the Harvey integration;
- selection by OpenAI for Astra for Law;
- connectors in Anthropic's Claude.
Bears still have legitimate ammunition. Cloud ARR growth slowed to 28% ($515.3 million) from 29% in the fourth quarter and 31% before that. Total ARR growth eased to 20% from 22%. According to the call analysis, net new ARR was down about 11% year over year. RPO fell sequentially to $799.4 million, and its growth slowed to 12% from 16% in the prior quarter and 27% the quarter before. Clients with more than $100,000 of ARR rose by only 11 to 908. License revenue dropped 21%, and second-quarter total revenue guidance of $158.8 million to $159.8 million sits below the first-quarter result. Management acknowledged that demand is outrunning its capacity for proofs of concept and deployments, and it has formed a firm-deployed engineering group to address the bottleneck. That framing supports the bull view of a backlog waiting to convert. It also means Celeste's monetization is gated by execution, not just interest.
The guidance raise looks largely like a flow-through of the first-quarter beat rather than a reset of second-half assumptions. Full-year subscription revenue guidance moved up about $1.8 million at the midpoint and total revenue about $1.7 million. Non-GAAP EPS guidance rose to $1.64-$1.68 from $1.58-$1.62. Second-quarter EPS guidance of $0.37-$0.39 implies a sequential step down.
That matters because expectations had shifted sharply before the report. Investor sentiment swung from a negative -0.47 after the prior report to a modestly positive 0.11, one of the more substantial reversals the scale allows. Shares were at $47.15 on the eve of the release, up 29.2% from the opening price after the August report. The stock sat 56.5% above its 200-day moving average and just 2.2% below the 52-week high of $48.19 set on October 23. Notably, it rallied 37% from a September 29 low of $34.41 in under a month. The Earnings Whispers trend signals are uniformly positive, reflecting that momentum. The stock was positioned for good news, not priced for skepticism.
The bottom line is that Intapp delivered the AI evidence turnaround skeptics were not positioned for: accelerating subscription revenue, wider margins, stronger cash flow and Celeste taking a rapidly rising share of bookings. Still, ARR, net new ARR and RPO are all moving the wrong way. Meanwhile, a raise that roughly matched the beat leaves limited cushion for a stock trading near its highs. The next few quarters need to show the AI pipeline converting into reaccelerating ARR, not just a larger share of a slowing bookings base.
Read our earnings preview for Intapp, Inc.: https://www.earningswhispers.com/article/INTA/20766
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-23 | |
| Oct-20 | |
| Oct-13 | |
| Oct-12 | |
| Sep-22 | |
| Sep-17 | |
| Sep-10 | |
| Sep-01 | |
| Aug-19 | |
| Aug-05 | |
| Aug-04 |
