NOA's Raised Revenue Outlook Faces Its First Test As Margins And Debt Draw Scrutiny
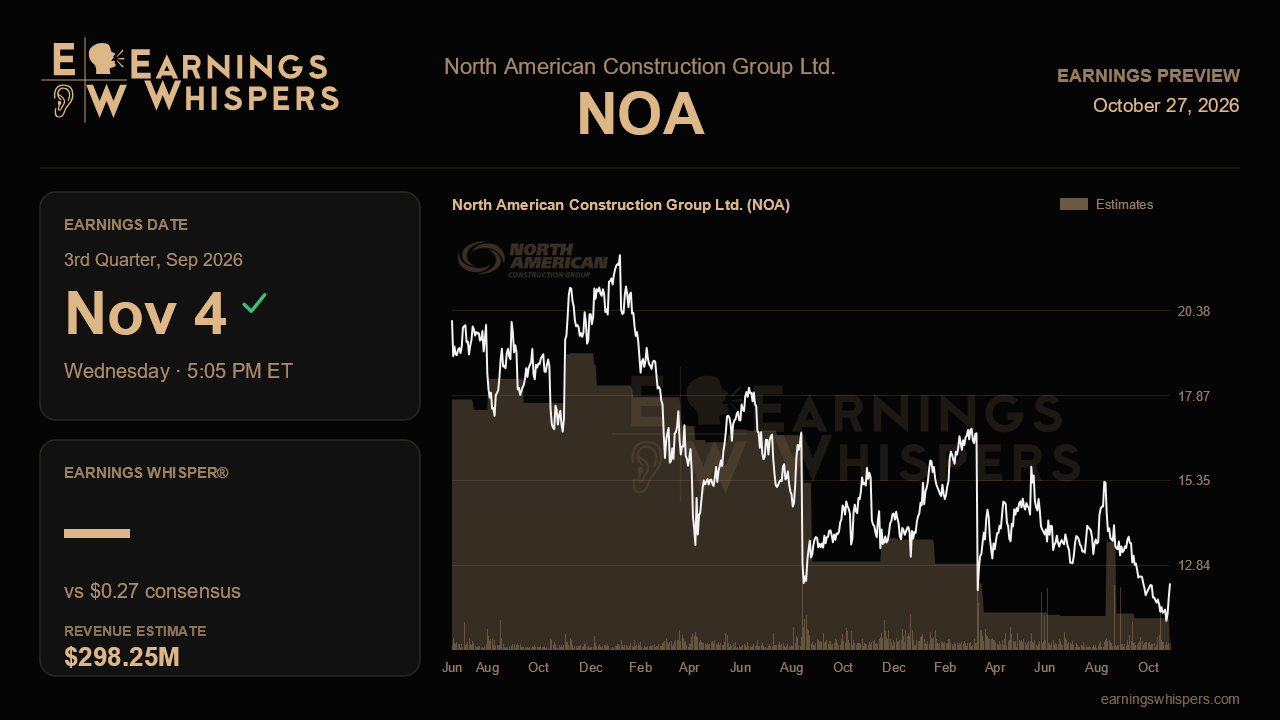
North American Construction Group heads into its third-quarter report with an odd mismatch. Management delivered its first real guidance raise of this cycle last quarter, describing oil sands demand as having turned decisively for the better. Yet the stock has fallen almost 26% since then, while the S&P 500 slipped about 1%. The market appears to have looked past the bigger revenue number and focused on what did not move: earnings power, cash flow and the balance sheet. This quarter is the first chance to show which reading was right.
The Street expects revenue of about $298.3 million, up roughly 29.5% from a year ago and slightly ahead of the $289.6 million posted last quarter. Earnings are expected to move the other way. Consensus calls for $0.27 a share, down about 45% from $0.49 a year earlier. That gap between strong sales growth and shrinking per-share profit is the core of the story. Much of the new revenue comes from the Australian expansion, including the IMC acquisition, and from pass-through work that adds volume without adding much margin. Meanwhile, interest costs have climbed with the debt used to fund that growth. Management now guides to full-year revenue of $1.15 billion to $1.29 billion, up from $1.09 billion to $1.24 billion. Full-year consensus of about $1.01 billion sits below even the low end of that range. Either analysts doubt the second-half run rate, or estimates have not caught up with the raise.
The operational checklist comes straight from last quarter's call. Management said the oil sands had shifted from a right-sizing story to one of full activity. Longer haul distances require more trucks, and new scopes are being priced at returns above 40% with gross margins near 15%. Evidence of that should show up as firmer Canadian equipment use and margin. Australia matters just as much. Gross margin there fell to 13.6% last quarter from 16.7% in the first quarter and 19.6% a year earlier. Management blamed seasonality and the lower unit rates on IMC work. A rebound would support that explanation. Another decline would suggest the mix shift is structural. The Nunavut fleet expansion was due to arrive this quarter, with about 20% site-level growth expected and a larger lift in the fourth quarter. Early signs of that ramp, along with any progress on the two or three fuel services contracts similar to the $135 million July win, would show new revenue that needs little capital.
The balance sheet may be the deciding factor. Net debt jumped by $191 million to about $1.1 billion last quarter, and reported leverage rose to 2.9 times. Management said leverage was 2.6 times on a second-half run-rate basis and that it intends to bring it down. Sustaining capital spending is now tracking above $200 million. Since EBITDA guidance of $380 million to $420 million was left unchanged despite the revenue raise, debt reduction depends on cash conversion rather than margin expansion. Visible deleveraging in this report would answer the bears directly. The bid pipeline also slipped from about $14.5 billion to just over $12 billion after two Australian losses, so new awards would help. Investors will also want an update on the CEO search, which management said would conclude soon.
Sentiment has swung sharply, from bearish ahead of last quarter to strongly bullish now. Meanwhile, the stock trades at $11.88, well below its 200-day moving average of $14.02 and closer to its post-earnings low of $10.85 than its $16.19 high. Price action, in other words, has priced in far more doubt than the sentiment reading implies. Ultimately, the report must show that the larger revenue base can produce cash that pays down debt. If revenue grows while margins and leverage stand still, the guidance raise will look like volume without value.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Sep-10 | |
| Aug-15 | |
| Aug-12 | |
| Aug-12 | |
| Jul-21 | |
| Jul-20 | |
| Jul-08 | |
| Jun-16 | |
| Jun-10 | |
| May-21 | |
| May-14 | |
| May-13 | |
| May-13 |
