Beta Bionics Tops Revenue Estimates But Misses The Whisper As Mint Launch Pressures Near-Term Guidance
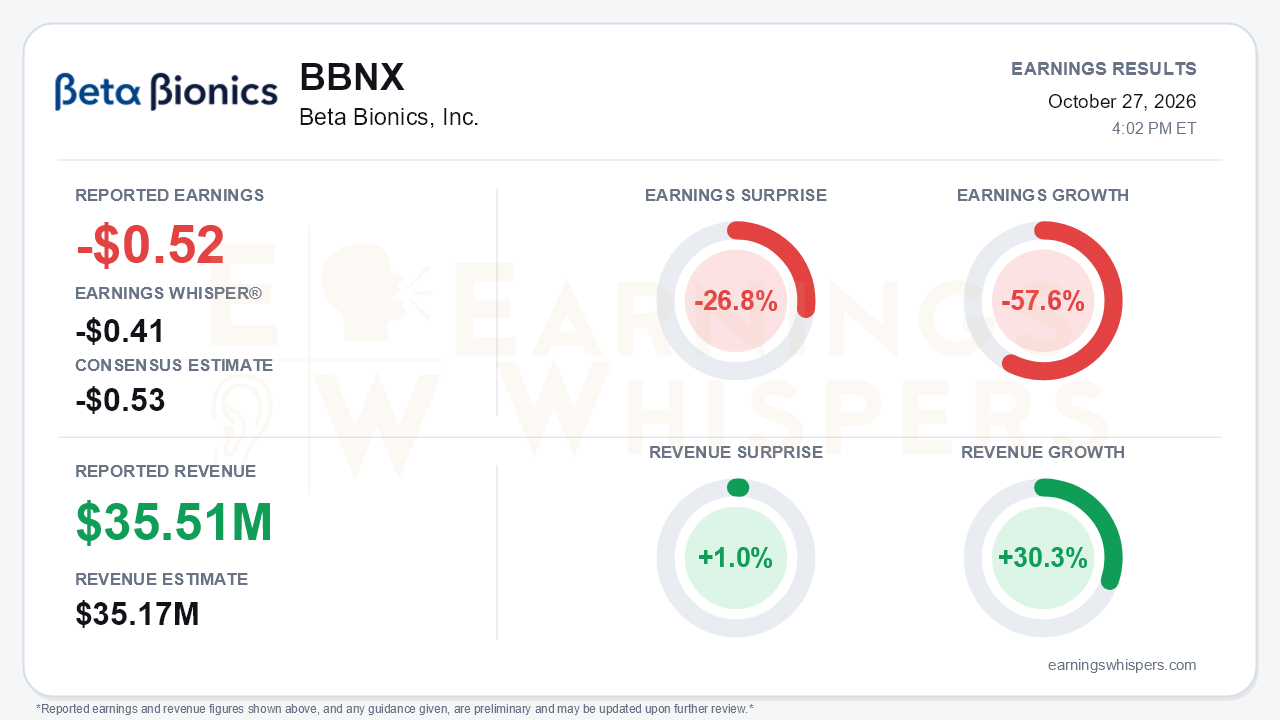
Beta Bionics (NASDAQ: BBNX) posted a third quarter that looked fine against consensus but fell short of what investors were actually looking for. The company lost $0.52 per share, a penny better than the -$0.53 consensus but well short of the -$0.41 Earnings Whisper number, a 26.8% miss against the whisper. The loss widened 57.6% from -$0.33 a year ago. Revenue of $35.51 million rose 30.3% and beat consensus by 1.0%. The central tension is timing. FDA clearance of the Mint patch pump and an accelerated Q1 2027 launch strengthen the long-term story, but the same launch is now weighing on the near-term numbers. Full-year revenue guidance has fallen below where it stood just one quarter ago.
The quality of the beat deserves scrutiny. Revenue growth has decelerated for three straight quarters, from 57% in Q1 to 38% in Q2 and about 30% now. The channel mix shows where growth is coming from. Pharmacy Benefit Plan sales jumped 118% to $13.6 million. DME channel sales rose only 4% to $21.9 million. DME iLet hardware revenue fell to $11.6 million from $14.2 million, which means single-use supplies from the installed base are carrying the growth while new-pump revenue shrinks. Gross margin improved 179 basis points from a year ago to 57.3%. On a sequential basis, however, it fell from 59.0% in Q2 and 59.5% in Q1, which management attributed to DME distributor destocking and supplies mix. Spending is outrunning sales. Operating expenses rose 46% to $46.9 million, and the operating loss widened to 75% of sales from 63% a year ago.
Guidance is where the report turns negative. The company set 2026 revenue at $124 million to $126 million. That raises the low end of the interim $121 million to $126 million range issued at Mint clearance, because expected deferrals are tracking below the roughly $10 million management had feared. Against the $131 million to $136 million range reaffirmed on the Q2 call, though, it is a clear cut. The new range implies Q4 revenue of only about $29 million to $31 million. Management also guided Q4 new patient starts down roughly 20% sequentially as prospective users wait for Mint. That follows only mid-single-digit sequential growth in Q3, compared with 10% to 20% in Q2. The company expects to recapture up to $8.5 million of deferred revenue in 2027. Investors will have to take that on faith until Mint is shipping.
The catalyst slate is substantial. Mint is cleared, with planned capacity of at least 1.5 million units in 2027. Pharmacy coverage is expected at about 40% of U.S. lives at launch, rising to about 50% by year-end. Management estimates Mint revenue per patient at roughly six times that of a DME iLet supply patient. Other milestones include the following:
- The type 2 pivotal trial is fully enrolled, targeting a label expansion around mid-2027.
- A fully closed-loop pivotal trial is due to start this quarter.
- Eversense 365 integration is slated for Q4.
Bears have legitimate ammunition too. The 3D Intelligence 510(k) was withdrawn over simulator-validation questions. The release still allows for a first-half 2027 launch and possibly Q4 2026, but the call framed mid-2027 as the realistic target and Q4 as only an outside possibility. Management also conceded that Mint will dilute gross margin in 2027 and that the launch begins on a single, capacity-constrained line. The full-year margin guide of 58.5% to 59.5% now depends on a Q4 rebound. Warning-letter remediation remains open.
The balance sheet removes the most immediate worry. A $161.3 million net equity raise lifted cash and investments to $373.6 million, up from about $225 million at the end of Q2. That funding came at the cost of dilution: shares outstanding rose to 54.4 million from 44.4 million at year-end.
Investor sentiment improved sharply heading into the report, climbing from -0.31 to roughly neutral at -0.01. That shift likely reflects enthusiasm around Mint. It also helps explain why a consensus-level result fell short of a more demanding whisper. The 200-day moving average sits at $14.84, compared with the $15.97 open after the July report. Price and AVWAP trends read positive, while sequential growth and momentum are neutral, consistent with a market leaning toward the Mint story rather than the current-quarter numbers.
The bottom line is that Beta Bionics delivered a respectable top line but a soft quarter for the near-term trajectory. Growth is decelerating, margins slipped sequentially, guidance sits below the Q2 level, and Q4 will be a deliberate air pocket. The bull case now rests almost entirely on a clean Mint ramp and the 3D Intelligence resubmission in 2027. The company has the cash to get there, but investors will need patience.
Read our earnings preview for Beta Bionics, Inc.: https://www.earningswhispers.com/article/BBNX/20740
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-20 | |
| Oct-19 | |
| Oct-14 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-05 | |
| Sep-29 | |
| Sep-25 | |
| Sep-22 | |
| Sep-18 | |
| Sep-17 |
