Equinor Misses On EPS As FX Hits The Bottom Line, But Raised Production And Cash-Flow Outlook Keep The Story Intact
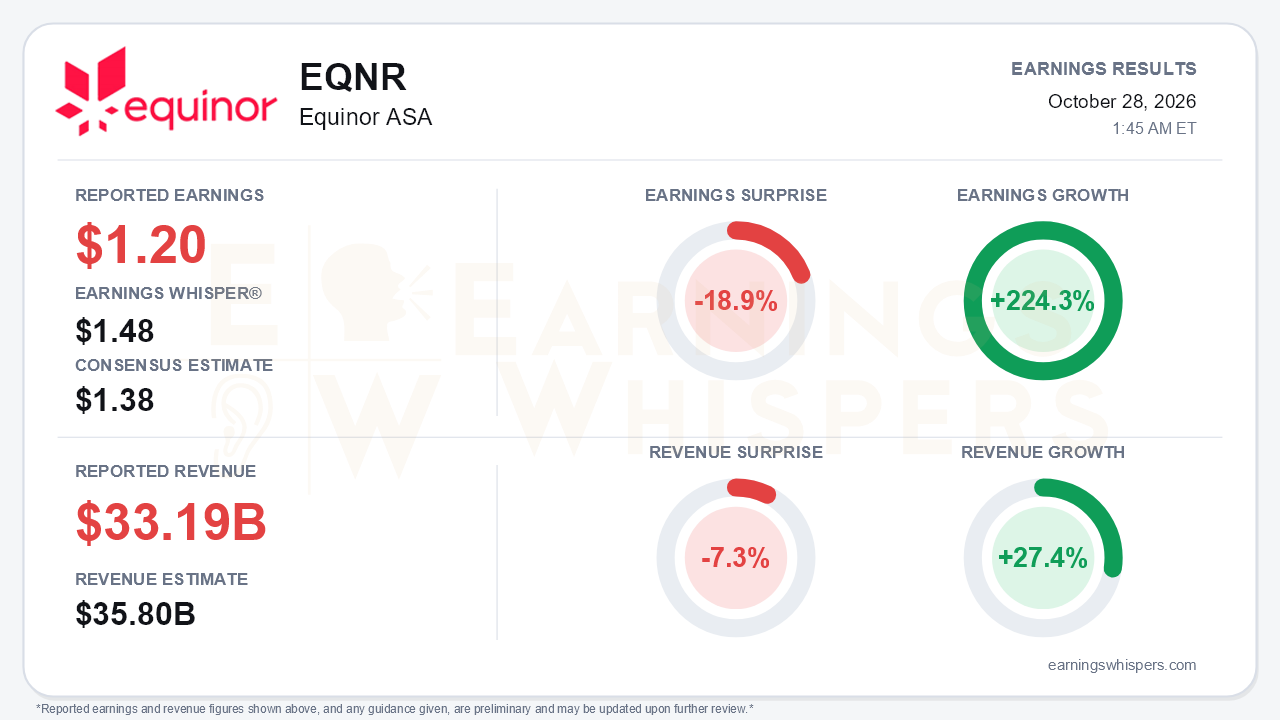
Equinor (NYSE: EQNR) delivered a clear headline miss for the third quarter of 2026. Adjusted earnings of $1.20 per share fell 18.9% short of the $1.38 consensus and well below the $1.48 Earnings Whisper. Revenue of $33.19 billion missed the $35.80 billion consensus by 7.3%. Even so, earnings grew 224.3% year over year and revenue rose 27.4%. The central tension is that the per-share line moved in the wrong direction while nearly every operating and cash-flow metric moved the right way. Adjusted EPS has now declined for two straight quarters, from $1.48 in Q1 to $1.33 in Q2 to $1.20. Over the same stretch, adjusted operating income climbed from $9.8 billion to $11.5 billion to $12.35 billion. On the call, management attributed the EPS slippage to currency effects in net financials, not to operational weakness.
The quality of the miss deserves a closer look rather than a reflexive reading. Operating results were strong. Reported net operating income more than doubled to $11.95 billion from $5.27 billion a year earlier, on a realized European gas price of $20.0 per mmbtu and liquids at $92.3 per barrel. Marketing, Midstream and Processing earned $893 million, driven by record results at the Mongstad refinery and LNG trading. That was the fourth consecutive quarter well above the roughly $400 million quarterly guide. Two drags sat below the operating line, however. International liftings trailed Equinor's share of production, which lowered sales volumes and likely contributed to the revenue shortfall. GAAP net income of $2.54 billion also trailed adjusted net income of $2.86 billion, as the call cited $485 million in net impairments at Stord and Statfjord and a $105 million Titan asset-retirement charge.
The raised outlooks on the call matter more than the miss. Management lifted 2026 production growth guidance to about 4% from the 3% it had held all year, with year-to-date growth near 5%. Projected 2026 cash flow from operations rose to roughly $29 billion at forward prices, up from $25 billion at June's Capital Markets Day and a $16 billion base case in February. The net debt ratio dropped to 3.8% from 10.4% last quarter and is heading toward about 0% by year end. Johan Sverdrup's decline has run around 11%, at the low end of the 10%–20% range guided in February. Renewable generation rose 26% on Dogger Bank and a new Brazilian onshore asset.
The forward picture carries real offsets, and bears have legitimate ammunition:
- **Slowing growth.** Year-over-year production growth decelerated to 2% from 3% in Q2 and 9% in Q1.
- **A 2027 step-down.** Management guided 2027 production below 2026, with Sverdrup's decline expected to steepen beyond this year's pace.
- **Empire Wind delay.** First power slipped to the first half of 2027 because turbine installation ran late, although capex and investment tax credit timing were unchanged.
- **Cost target slippage.** The 10% underlying cost-reduction goal, on track earlier in the year, is now behind plan due to FX and energy costs.
- **Tax lag.** First-half 2027 tax payments will exceed second-half 2026 payments, putting the tax-adjusted net debt ratio closer to 10% or more.
- **Buyback limits.** Distributions above $80 Brent and $11 gas will not scale linearly as management prioritizes the balance sheet.
- **Other issues.** Safety incidents are rising, and Rosebank still awaits UK approval.
The new 2027 capital framework of $2 billion to $4 billion in buybacks at $60–$80 Brent, plus dividend growth above 5% a year, gives investors a clearer floor. It also signals discipline rather than open-ended upside.
Strategically, the quarter added several options:
- A stake in the Lackawanna gas-fired plant, which ties Equinor's US gas position to PJM power and data-center demand.
- Shell farming into Bay du Nord, with a final investment decision still targeted for early 2027.
- Entry into Namibia alongside Chevron, with a well to spud in Q4.
- Two discoveries in Angola.
- An NCS exploration alliance with Aker BP and Vår Energi to test up to 25 standalone prospects.
Management also cited growing customer appetite for long-term Norwegian gas contracts. For 2027, Bacalhau at plateau, Rosebank, Jackdaw and Yggdrasil are the volume supports against Sverdrup decline.
The market setup is more complicated than the surprise implies. The stock had already run hard into the report. At $47.06, shares were up 19.4% since the open after the July report and 26.6% above the 200-day moving average of $37.17. That price sat just 4.1% below the $49.08 52-week high set on October 23, near the top of the inter-earnings range. Investor sentiment edged up only modestly, from 0.071 to 0.082, staying mildly positive rather than enthusiastic. The Earnings Whispers trend signals are broadly positive, consistent with the stock's strength. With shares priced near highs, however, an EPS miss and a guided 2027 production decline give the market reason to pause.
The bottom line is that Equinor's miss was a below-the-line and volume-timing problem layered on top of an operationally strong, cash-rich quarter. Raised production guidance, a sharply higher cash-flow outlook and a near-zero net debt ratio preserve a credible story for 2026. The decelerating growth rate, the sequential EPS decline, the Empire Wind delay and the expected 2027 production step-down cap how far that story can stretch, especially for a stock already trading near its highs.
Read our earnings preview for Equinor ASA: https://www.earningswhispers.com/article/EQNR/20841
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 5 hours | |
| 16 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-23 | |
| Oct-21 | |
| Oct-19 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 |
