ICON Misses The Whisper By A Penny, But Record Bookings And Rising Margins Show Its Recovery Is Reaching The P&L
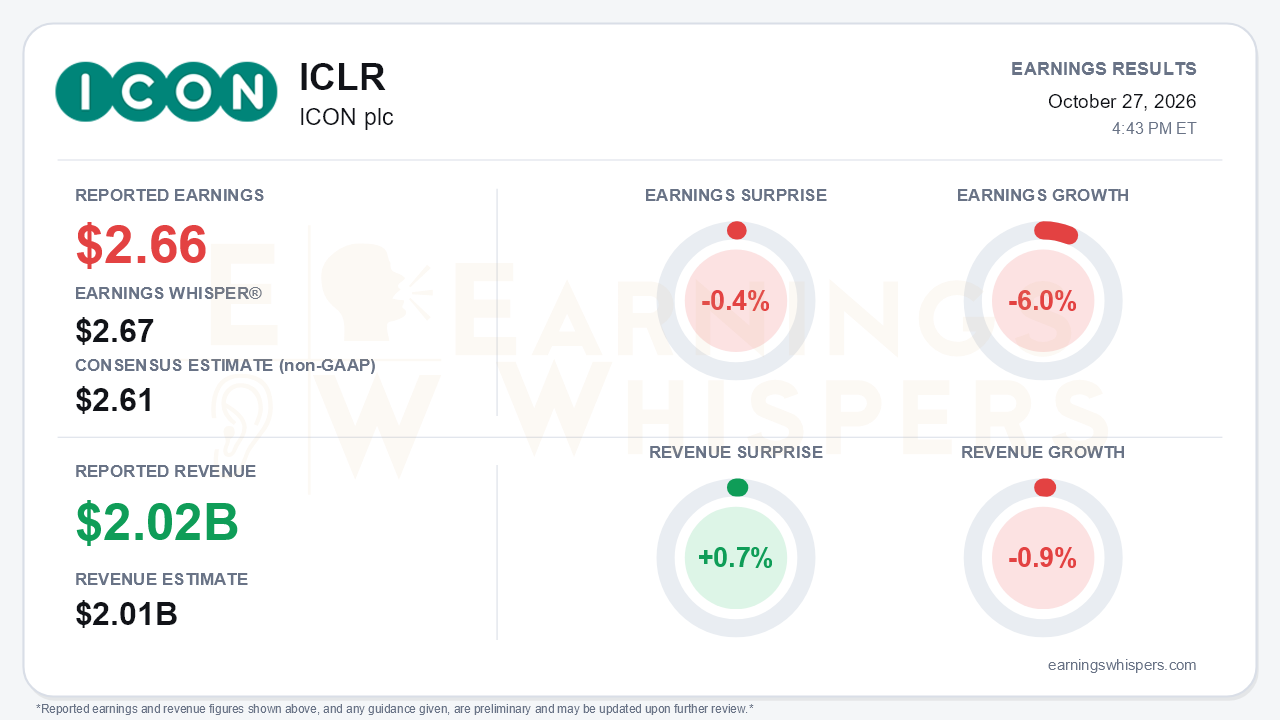
ICON plc reported third-quarter adjusted earnings of $2.66 per share on revenue of $2.025 billion. EPS cleared the $2.61 consensus but fell a penny short of the $2.67 Earnings Whisper number, a 0.4% miss against the bar that mattered. Revenue beat consensus by 0.7%. On Earnings Whispers' normalized basis, earnings fell 6.0% year over year and revenue declined 0.9%. The company's own comparisons are harsher: it reported revenue down 2.9% (2.5% in constant currency) and adjusted EPS down from $3.20 a year ago, with the May divestiture of Symphony Health weighing on the reported top line. Whichever lens investors use, the headline is a business still shrinking year over year. That is the central tension: the trailing numbers remain soft, while nearly every leading indicator and sequential trend is improving.
The quality of the quarter is better than the year-over-year optics suggest. Adjusted EPS has climbed sequentially from $2.50 in Q1 to $2.56 in Q2 and now $2.66. Adjusted EBITDA rose 3% sequentially to $336.9 million, and the margin expanded to 16.6% from 15.9% in Q2 and 15.6% in Q1. Adjusted gross margin improved 90 basis points to 24.7%. Free cash flow of $302.4 million extended a steep progression from $136 million in Q1 and $239 million in Q2. The GAAP picture swung from a $3.67 loss a year ago, when the company took $465 million of Data Solutions impairments, to a $1.58 profit. However, the gap between GAAP and adjusted earnings remains wide, driven by amortization, investigation and litigation costs, restructuring, and $17 million of financing charges tied to the August refinancing.
The call made the case that the long-promised inflection is finally starting to appear in reported results. Net business wins hit a record $3.15 billion, a 1.56x book-to-bill and the fourth straight quarter above 1.3x. Gross wins rose 27% year over year, and backlog grew 4.8% sequentially to $24.5 billion. Direct-fee revenue returned to modest sequential growth, which management flagged as a milestone. New biotech preferred partnerships, including a four-year sole-provider deal, and quantified AI productivity gains gave the story more texture. Management's tone shifted noticeably, from "navigating headwinds" earlier in the year to describing a clear step forward.
Bears still have legitimate ammunition. The full-year revenue guide moved up to $8.1 to $8.2 billion, the top of the prior $7.85 to $8.15 billion range, but management attributed the increase to higher pass-through activity. Pass-throughs now make up roughly one-third of revenue, which dilutes reported margins. EPS guidance was only narrowed, to $10.35 to $10.65, leaving the roughly $10.50 midpoint unchanged. The full-year EBITDA margin guide of 16% to 16.5% sits below what was implied earlier in the year. Other caution flags:
- **Weaker disclosure:** Management stopped reporting quarterly direct-fee book-to-bill and now gives only a trailing figure. That figure is 1.3x, compared with 1.2x in Q2 alone.
- **Elevated cancellations:** At $639 million, cancellations ran at the upper end of the expected range.
- **Near-term headwinds:** FX is a bigger drag than at May guidance, and Q4 SG&A is set to step up.
- **Pricing pressure:** Price remains a leading reason for lost bids.
Capital allocation was assertive. ICON repurchased $400 million of stock at an average of $170 and approved a new $750 million authorization. It also completed a $2.15 billion investment-grade bond deal that cleaned up its term loan, bridge facility, and May 2027 notes. The cost is leverage, which rose to 2.0x from 1.8x, with net debt of $2.6 billion. Looking ahead, management floated an informal 2027 framework of mid-single-digit revenue growth and EPS potentially near $11.50, roughly 10% above the 2026 midpoint. That framework is the real catalyst, though it is an expectation, not a commitment.
The market has already been leaning toward the recovery narrative. Shares are up 10.4% since the open following the July report, to $182.98, and sit about 26% above the 200-day moving average of $145.52. That leaves the stock above the price ICON paid for its buybacks. Earnings Whispers' price and AVWAP trend readings are both positive. Investor sentiment remains negative but improved modestly, from -0.17 to -0.12, consistent with skepticism thawing rather than enthusiasm taking hold. With the stock extended, a penny miss against the whisper and an unchanged EPS midpoint offer little room for a fresh rerating.
The bottom line is that ICON delivered a quarter where the forward indicators clearly outshone the backward-looking figures. Record bookings, expanding margins, accelerating cash flow, and a credible 2027 earnings framework support the turnaround thesis. Meanwhile, shrinking revenue, a pass-through-driven guidance raise, and reduced disclosure explain why sentiment remains below neutral. The setup now depends on direct-fee growth accelerating enough to turn that backlog into the earnings progression management is promising.
Read our earnings preview for ICON plc: https://www.earningswhispers.com/article/ICLR/20765
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-08 | |
| Aug-20 | |
| Aug-14 | |
| Aug-06 | |
| Aug-04 | |
| Jul-31 | |
| Jul-30 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-22 | |
| Jun-24 | |
| Jun-23 |
