Extreme Networks Beats And Raises As Platform ONE Lifts ARR, But Recurring Revenue Slows In A Transition Year
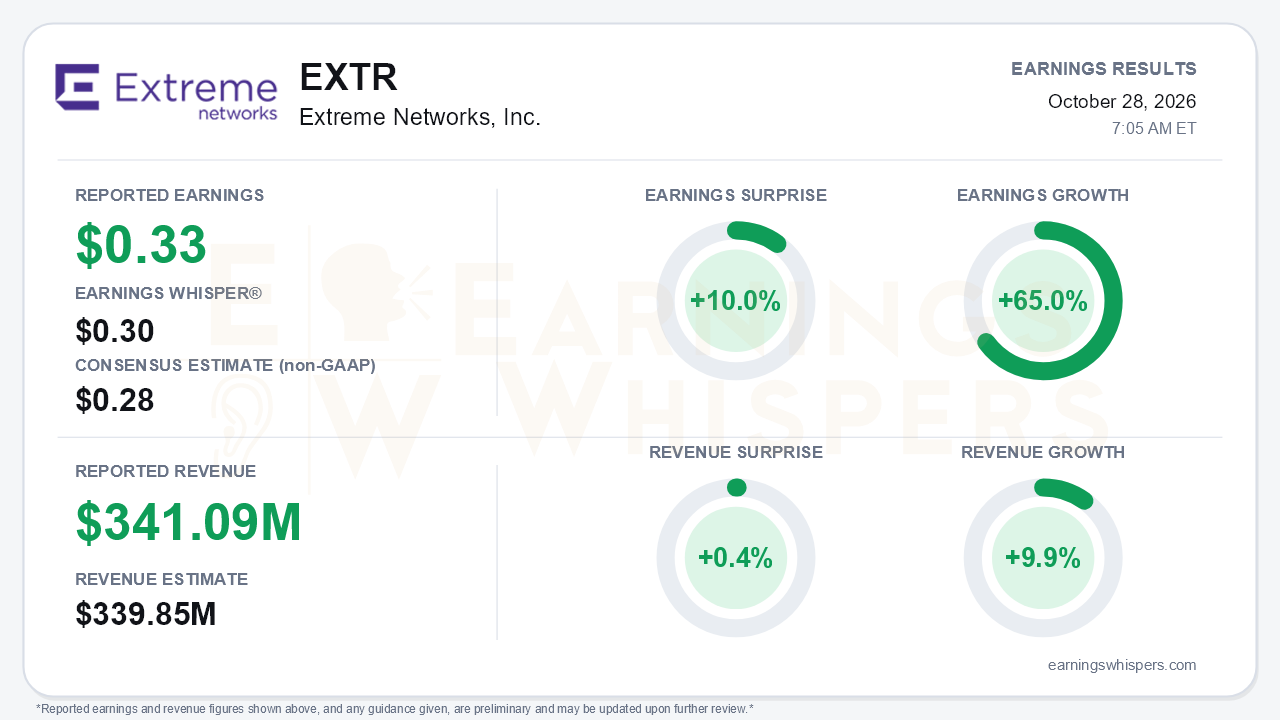
Extreme Networks opened fiscal 2027 with the kind of beat-and-raise that turnaround skeptics were not positioned for. Non-GAAP earnings of $0.33 per share topped the $0.28 consensus by 10.0% and cleared the $0.30 Earnings Whisper number. Revenue of $341.09 million edged past the $339.85 million consensus by 0.4% and grew 9.9% year over year, the company's seventh straight double-digit quarter on its own rounding. Earnings grew 65.0% year over year on Earnings Whispers' normalized basis. Management cited 50% non-GAAP EPS growth, from $0.22 to $0.33, so the two growth figures rest on different prior-year baselines. Either way, the more important development was the guidance. Full-year revenue moved to $1.402-$1.412 billion, roughly 10% growth, up from $1.38-$1.40 billion. Non-GAAP EPS guidance rose to $1.35-$1.39 from $1.28-$1.33.
The quality of the beat holds up better than the narrow revenue surprise implies. Product revenue rose 12% to $218.3 million and did most of the work. Non-GAAP gross margin expanded 130 basis points to 62.6% even as memory and component costs climbed industry-wide. Non-GAAP operating margin jumped to 17.4% from 13.3% a year ago and 15.7% last quarter, and adjusted EBITDA grew 47%. GAAP results were thinner but still strong: EPS of $0.12 versus $0.04, despite $7.4 million of restructuring charges, $3.7 million of other non-recurring costs and a $2.1 million debt refinancing write-off. Free cash flow of $38.6 million reversed a $20.9 million outflow a year earlier. However, it fell short of the $65 million generated in the fiscal fourth quarter. Inventory jumped from $70 million to $100 million, including about $36 million of memory the company bought ahead of shortages.
That inventory build ties into the quarter's central tension. Extreme is deliberately trading near-term cash and recurring-revenue optics for strategic position.
- **Supply strategy.** Management says components are secured through calendar 2027 while rivals quote extended lead times. That lets Extreme take more measured pricing actions than larger competitors.
- **Revenue mix shift.** Platform ONE now accounts for more than half of subscription bookings, up from 30% for fiscal 2026. SaaS ARR reaccelerated to 22% growth ($264.7 million) from 18% last quarter, with management guiding to more than 20% for the rest of the year.
- **The cost of that shift.** Recurring revenue grew only 7%, down from 13% in the third quarter of fiscal 2026 and 12% in the second. Legacy support contracts are being folded into Platform ONE. Management frames fiscal 2027 as a transition year and expects a sharp recurring-revenue reacceleration in fiscal 2028. That outcome is a forecast, not a result. Investors watching only the subscription and support line, up about 6%, will see a business that looks slower than the ARR headline suggests.
The demand indicators from the call were consistently firmer:
- **Large deals.** Growth in the $1 million-plus deal funnel accelerated to above 20% from mid-teens, and $1 million-plus customers in the quarter rose to 44 from 36.
- **Managed service providers.** Active MSPs increased to 85 from 74.
- **Competitive wins.** Displacements included a $10 million, 21-hospital California health network, a 70-branch Austrian bank and Phoenix Raceway.
- **AI products.** Agent ONE Coworker drew roughly 10x the engagement of the first-generation AI agent in its first month. Token-based monetization and on-prem Exchange Zones are targeted for the first half of calendar 2027, so the revenue opportunity sits on the roadmap rather than in the numbers.
Bears still have legitimate ammunition:
- **Regional softness.** APAC revenue declined on tough comparisons.
- **Cost and pricing pressure.** Component inflation is embedded in gross margin, and industry pricing remains fluid.
- **Near-term margin dip.** Second-quarter guidance calls for a seasonal non-GAAP operating margin of 16.4%-17.4% and EPS of $0.32-$0.34, which offers no sequential earnings step-up.
The market setup is more complicated than the surprise implies. Shares closed at $23.85 before the report, down 11.1% from the $26.83 opening after the August release. That leaves the stock 14.8% below the inter-earnings high of $27.99 set on that post-report day, so the prior quarter's spike was fully given back. The stock bottomed at $20.76 on September 29, then recovered about 15% and moved back to roughly 9% above its $21.91 200-day moving average. Investor sentiment improved modestly, from 0.37 to 0.42, which is still positive but hardly euphoric. Apart from a negative price trend, the Earnings Whispers trend readings lean positive, consistent with improving sequential growth rather than a crowded trade.
The bottom line is that Extreme delivered a credible beat-and-raise. Margin expansion, accelerating ARR and a funnel of large deals all support the higher 10% growth target. The headline, however, masks a recurring-revenue slowdown and a cash build into inventory that management asks investors to look through until fiscal 2028. With the stock having already surrendered its last post-earnings rally, execution on that transition, not the size of this beat, is what matters most from here.
Read our earnings preview for Extreme Networks, Inc.: https://www.earningswhispers.com/article/EXTR/20844
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-21 | |
| Oct-21 | |
| Oct-09 | |
| Oct-06 | |
| Oct-05 | |
| Sep-30 | |
| Sep-29 | |
| Sep-29 | |
| Sep-24 | |
| Sep-22 | |
| Sep-18 | |
| Sep-15 |
