Evercore Crushes A Low Bar With Record Backlog, But A 20% Slide Shows The Market Is Pricing Deceleration
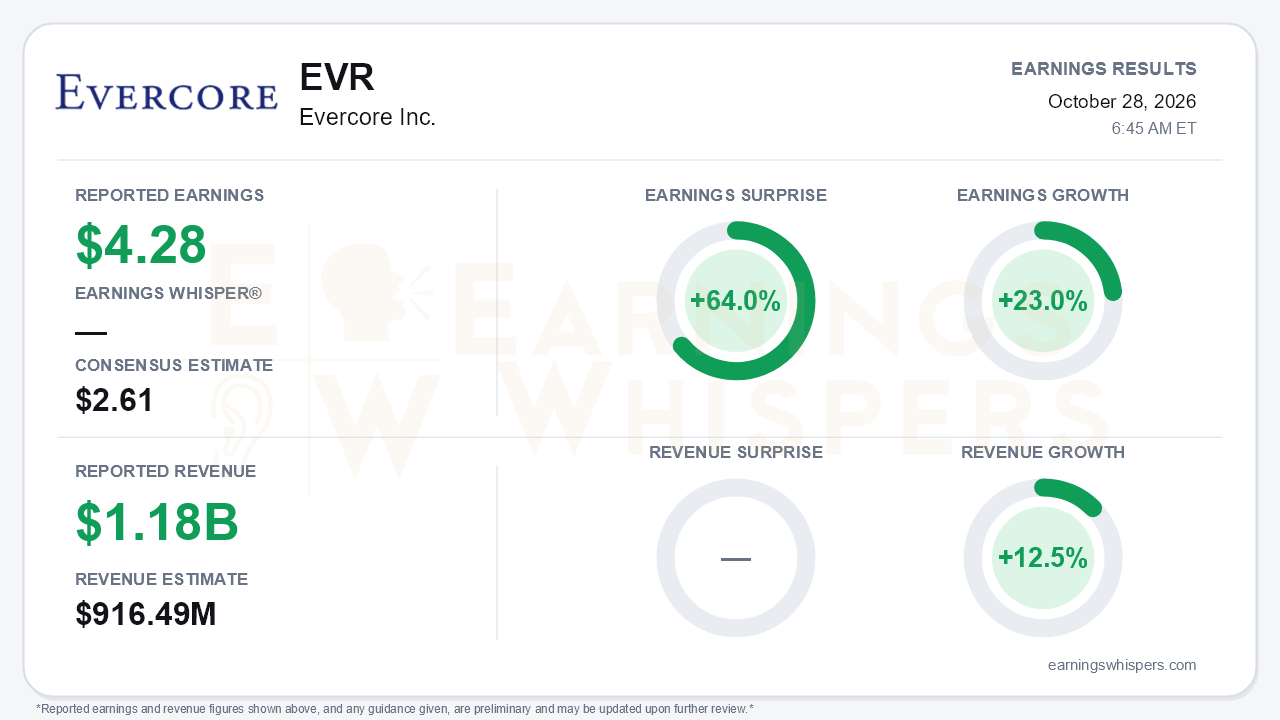
Evercore delivered a quarter that would normally be easy to celebrate. Adjusted EPS of $4.28 beat the $2.61 consensus by 64.0% and grew 23.0% year over year. Revenue of $1.177 billion topped the $916.49 million estimate by 28.4% and rose 12.5%. It was the firm's sixth consecutive quarterly revenue record, and management upgraded its backlog language from "near record" in the second quarter to "record." The central tension is that the stock enters the print down 20% since the opening after the July report, sitting near a fresh 52-week low. The size of the beat says as much about how far estimates had fallen as about the quarter itself. The market is wrestling with decelerating growth, not with any weakness in the franchise.
The deceleration is real but largely arithmetic. Revenue growth of 12.5% compares with roughly 38% year to date and about 56% in the first half, as Evercore laps much tougher second-half 2025 comparisons. Beneath that, the core engine held up well:
- Advisory fees reached a record $1.01 billion, up 14%.
- The number of advisory and underwriting fees rose 21% to 324.
- Fees of at least $1 million climbed 22% to 167, so activity broadened rather than depending on a handful of mega-deals.
The softer spots sit at the edges. Commissions slipped 4% on lower trading volume after rising 9% in the second quarter. Underwriting fees grew 27% year over year, but at $56 million they were down sharply from a record $97 million in the second quarter, on fewer deals. Other revenue fell 35% on a GAAP basis as the investment-funds portfolio, a hedge for deferred compensation, underperformed.
The quality of the margin story deserves a closer look, and it mostly passes. The adjusted compensation ratio fell to 63.0% from 65.0% a year ago and 63.5% in the second quarter, lifting the adjusted operating margin to 22.9% from 21.8%. The adjusted non-comp ratio rose year over year to 14.1% from 13.2% as technology, consulting and travel costs climbed. Even so, it fell sharply from the second quarter's elevated 17.5%, and management nudged its full-year non-comp target from roughly in line with 2025 to "maybe something a little better." The GAAP picture is less flattering. GAAP EPS was $3.93 versus $3.41, and the GAAP operating margin was flat at 20.8%. The gap reflects Robey Warshaw acquisition charges, contingent-consideration expense, and special charges that include a provision for non-U.S. employment taxes tied to prior periods. None of these is alarming, but investors should note that the adjustments are recurring rather than one-off this year.
The call preserved a credible growth story. Management expects activity to stay healthy into 2027 and noted that the Warner Bros. Discovery fee closed October 6 and will land in the fourth quarter. It flagged digital-infrastructure and debt-advisory financing, including the $63 billion Broadcom/Anthropic compute transaction and the $15.6 billion Nexus data-center financing, as "a very high potential area." The talent build continues:
- Investment Banking SMDs rose to 191 from 171 at the start of the year, with more than 50 still ramping.
- Trailing revenue per SMD of $27.3 million compares with a five-year average near $22 million.
- More than 60 senior bankers now cover sponsors, with pitch and win rates rising.
The co-president appointments of Nigel Dawn and Naveen Nataraj add succession clarity. Bears still have legitimate ammunition. IPO activity slowed into the fourth quarter, and sponsor and middle-market activity remains below historical levels. Large-cap M&A concentration, rate uncertainty and a 2028-29 maturity wall are also live concerns. Management declined to call fourth-quarter seasonality after pull-forward commentary.
The market setup is more complicated than the surprise implies. Investor sentiment swung from modestly positive (0.14) to modestly negative (-0.09). That is a meaningful shift in tone, though not a capitulation. Shares at $259.86 sit 18.1% below the 200-day moving average and about 20% below the inter-earnings high of $325.15, set the morning after the last report. They are just 5.9% above the October 20 low of $245.47. The Earnings Whispers trend readings lean negative on price and AVWAP, while sequential growth and momentum are neutral. Management has leaned into the weakness: it bought back 0.5 million shares in the quarter at an average of $291.60, and capital return topped $1 billion year to date, already a full-year record.
The bottom line is that Evercore's fundamentals strengthened on almost every operating measure that matters. Those measures include advisory breadth, comp leverage, backlog and banker productivity, even as the headline growth rate cooled against hard comparisons. The stock has been trading on fears of a cycle peak rather than on reported results. The open question is whether record backlog and the fourth-quarter WBD fee can convert quickly enough to outweigh softer capital markets and an uncertain seasonal finish.
Read our earnings preview for Evercore Inc.: https://www.earningswhispers.com/article/EVR/20843
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 9 hours | |
| 10 hours | |
| 14 hours | |
| Oct-24 | |
| Oct-23 | |
| Oct-20 | |
| Oct-19 |
Goldman, Evercore Explore Funds That Would Let PE Firms Hold Assets for 15 Years
EVR
Benzinga Private Markets
|
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-18 | |
| Oct-16 | |
| Oct-15 |
