Blackbaud Clears Consensus But Misses The Whisper As A 45% Rally Meets Reaffirmed, Not Raised, Guidance
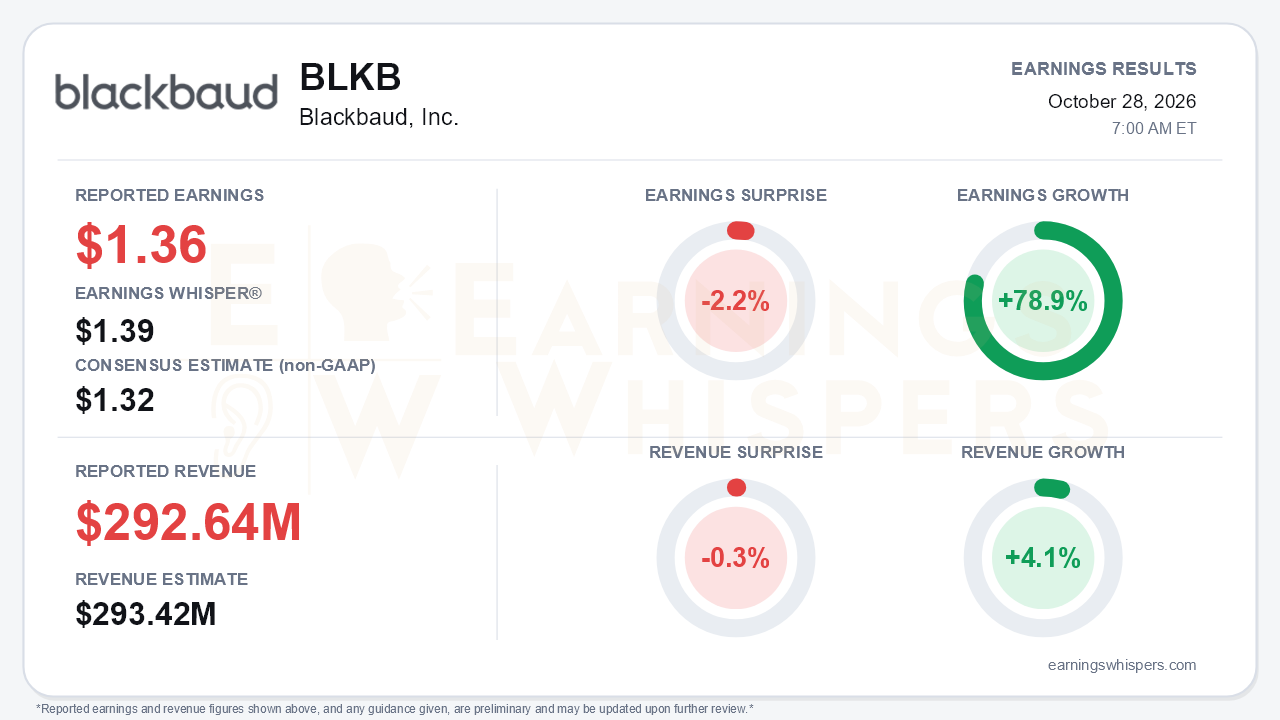
Blackbaud delivered a solid third quarter on a stock that had already priced in a lot of good news. Non-GAAP earnings of $1.36 per share topped the $1.32 consensus but fell short of the $1.39 Earnings Whisper number, a 2.2% miss against the expectation that mattered most for a stock that rallied hard into the print. Revenue of $292.64 million rose 4.1% year over year but came in 0.3% below the $293.42 million consensus. Earnings Whispers calculates earnings growth of 78.9%. That is the central tension: execution and cash generation are improving, but the quarter was not strong enough to justify a guidance raise, and the top line slightly undershot.
The quality of the earnings deserves some scrutiny. Revenue grew only modestly, so margin expansion and buybacks drove much of the EPS lift. Non-GAAP operating margin widened 240 basis points to 32.3%, and adjusted EBITDA margin reached 38.0%. Diluted weighted shares fell to roughly 45.0 million from 48.5 million a year ago, and year-to-date repurchases now exceed 7% of shares outstanding. GAAP results tell a more restrained story. GAAP diluted EPS rose just $0.04 to $1.02, and GAAP net income actually slipped to $46.1 million from $47.5 million because last year's quarter included a tax benefit. Cash flow was the cleanest strength. Quarterly free cash flow of $126.0 million compared with $75 million in Q2 and $37 million in Q1. Leverage fell below 2.3x from 2.7x in Q1.
The operating trend did improve sequentially. Organic revenue growth re-accelerated to 4.1% from 3% in Q2, back near Q1's 4.2%. Recurring revenue was 98.1% of the total. Management also offered something the stock has lacked: clearer visibility into 2027. The 2027 renewal cohort is about 25% smaller than 2026's, and gross dollar retention is expected to return to 91-92% by the end of 2027. Savings from closing the last two colocation data centers begin in 2027, and four-year-plus contracts held at 25% of the mix, up from 20% at the end of 2025. Deal evidence supported the demand narrative, including a seven-figure, multi-year agreement with International Schools Partnership covering more than 100 schools and a competitive CRM displacement at Cal State Chico.
The product slate from bbcon is the longer-dated catalyst. It includes:
- Platform for Good, a unified operating system.
- Lantern, a fundraising-specific language model built with Databricks that arrives in 2027.
- A cloud-native AI rebuild of Raiser's Edge NXT, pulled forward by more than a year.
- New agents and a payments partnership with BILL.
Bears have legitimate ammunition, however. AI products still contribute no meaningful revenue and remain excluded from guidance. The large 2026 renewal cohort will now weigh on contractual recurring growth through the first half of 2027, longer than previously framed. Global workforce transition costs were raised to $8-10 million from $6-8 million, with activity extending through 2027.
Guidance is where the data conflict. Blackbaud says it reaffirmed full-year targets: revenue of $1.173-$1.179 billion, non-GAAP EPS of $5.15-$5.25, and free cash flow of $280-$290 million. It also said it expects to finish in the upper half of the range on all four metrics. Earnings Whispers, however, characterizes the outlook as lowered. The call offers context for that more cautious reading. The current framing is less emphatic than the CEO's Q2 language about the high end across all four metrics. Hitting the upper half of the revenue range also requires roughly a 1.5-point step-up in fourth-quarter organic growth. Either way, investors did not get a raise, and adjusted EBITDA margin was flat sequentially at about 38%.
The market setup is more complicated than the consensus beat implies. Shares have climbed 45.3% from the $36.97 open after the July report, which was essentially the inter-earnings low. The stock entered this report 29.5% above its 200-day moving average and only 5.2% below its October 22 quarterly high of $56.65. Investor sentiment improved from -0.16 to -0.06, a meaningful shift, but it remains slightly negative even after the rally. The Earnings Whispers trend signals are mostly positive on price, momentum, and AVWAP, while sequential growth is only neutral. That pattern fits a stock whose re-rating has outpaced its revenue trajectory.
The bottom line is that Blackbaud's quarter strengthened the margin, cash-flow, and capital-return story and offered a more credible path to better retention in 2027. Still, it missed the whisper, fell slightly short on revenue, and stopped at a reaffirmation. After a 45% run, the stock now depends on fourth-quarter growth acceleration and eventual AI monetization rather than on buyback-fueled EPS alone.
Read our earnings preview for Blackbaud, Inc.: https://www.earningswhispers.com/article/BLKB/20828
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 10 hours | |
| 14 hours | |
| Oct-27 | |
| Oct-14 | |
| Oct-05 | |
| Sep-29 | |
| Sep-29 | |
| Sep-29 | |
| Sep-18 | |
| Aug-18 | |
| Aug-11 | |
| Aug-10 | |
| Jul-29 | |
| Jul-29 |
