Bausch + Lomb Posts A Third Beat-And-Raise On Margin Expansion, But An Abrupt CEO Change Clouds The Story
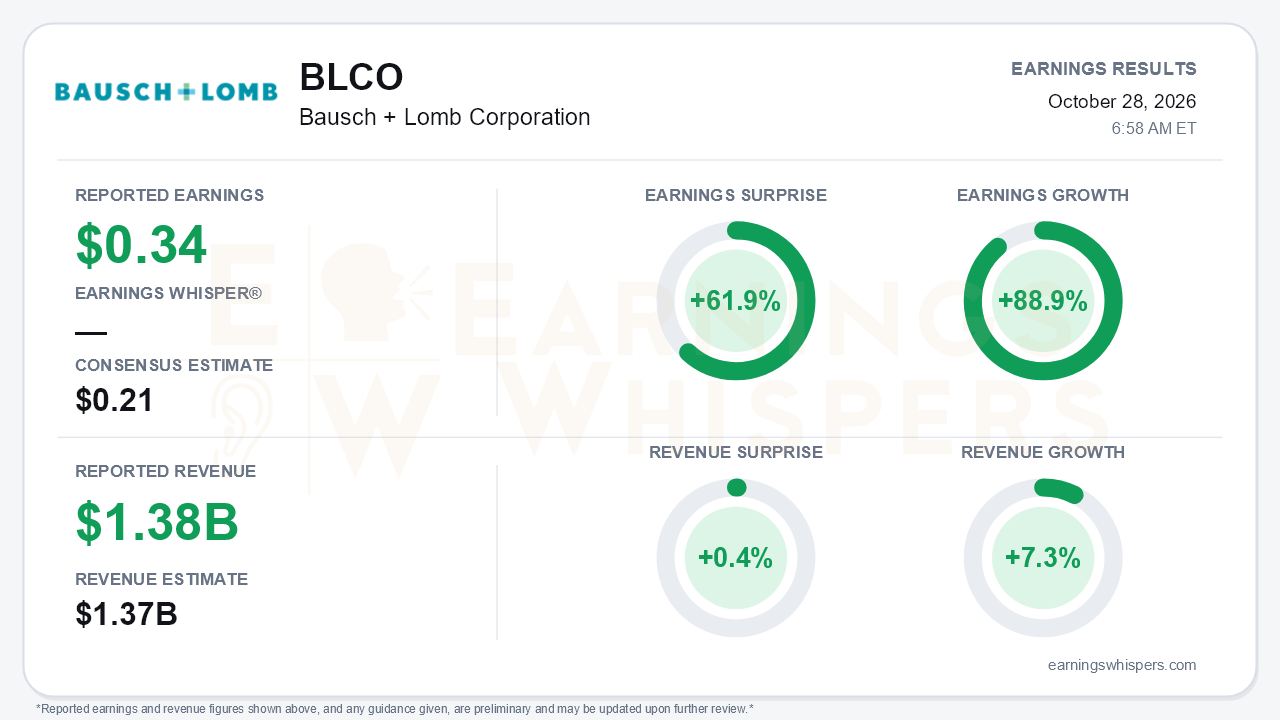
Bausch + Lomb delivered the kind of quarter that changes how investors view its earnings power. The company also introduced a leadership question that the numbers cannot answer. Adjusted EPS of $0.34 beat the $0.21 consensus by 61.9% and grew 88.9% year over year. Revenue of $1.375 billion was only 0.4% above the $1.37 billion estimate and grew 7.3%. The beat came almost entirely from margins rather than the top line. Management raised full-year guidance for the third time in 2026, the biggest change being a $65 million lift to adjusted EBITDA excluding acquired IPR&D, now $1.090-$1.140 billion. That is the good news. The complication is that Brent Saunders is gone, and Bausch Health CEO Tom Appio is serving as interim chief, with no rationale offered beyond filings. That is the central tension.
The quality of the beat deserves scrutiny, though it largely holds up.
- **Margin expansion:** Adjusted EBITDA rose to $325 million from $243 million. Margin reached 23.6%, versus 17.6% in Q2 and 16.1% in Q1, and already sits above the company's 2028 target of 23%.
- **GAAP results improved too:** Operating income climbed to $155 million from $95 million. GAAP net income swung to $32 million, or $0.09 per share, from a $28 million loss.
- **Gross margin had help:** Cost of goods sold actually fell year over year despite higher sales. Part of that reflects a roughly $14 million one-time tariff refund, worth about 100 basis points of gross margin. Excluding it, gross margin was still 63.6%.
- **Cash flow is the strongest evidence:** Free cash flow of $178 million compares with $19 million in Q2. Net leverage fell to 4.1x from 4.7x last quarter and 5.7x a year ago. That matters for a company still carrying $95 million in quarterly interest expense.
Growth held steady rather than accelerating. Constant-currency revenue rose 8%, matching Q2 and improving on Q1's 6%. Reported growth of 7% trailed the nine-month pace of 9% because currency turned into a $6 million headwind in the quarter.
Beneath the surface, the growth engines are shifting.
- **Pharmaceuticals (+11%):** MIEBO grew 42% to $119 million, up from $91 million in Q2. Xiidra, however, slowed to 2% growth from 6% in Q2 and 30% in Q1.
- **Vision Care (+5% reported, +6% constant currency):** LUMIFY rebounded sharply. The release cites 35% growth, while the call cited 38% to $66 million, versus just 2% in Q2. Daily SiHy grew roughly 24-25%, up from 16% in Q2, and U.S. contact lenses accelerated to 9%. International contact lenses slowed to 4% from 6%, weighed down by the legacy portfolio.
- **Surgical (+9%, down from 16% in Q2):** Equipment fell 11% as management prioritized system placements over outright sales. Premium IOL growth, while still roughly 70-75%, moderated from 175% in Q2. On the positive side, surgical gross margin improved by about 800 basis points.
The forward catalysts are tangible:
- MIGS approval for Elios is expected by year-end.
- An EDOF pre-submission meeting is set for mid-December.
- A U.S. myopia study starts in Q4, and LUMIFY Next launches in the first half of 2027.
- An encouraging FDA meeting on oral tonabersat for dry/early AMD leads to a PK safety study in early 2027.
- Appio pointed to further SG&A savings and possible accretive M&A.
Bears have legitimate ammunition, however. An interim CEO splitting time with the parent company invites questions about recombination with Bausch Health, which analysts raised directly on the call. Pipeline reprioritization under new leadership could also delay programs. The 2028 margin target was not formally raised and was deferred to 2027 guidance, even though Q3 already exceeded it. The guidance raise itself was characterized as in line with estimates, suggesting the Street had partly anticipated the upgrade. Full-year EBITDA guidance implies fourth-quarter EBITDA of roughly $320-$370 million, so the low end would mean little sequential progress from Q3.
Investor sentiment shifted meaningfully. It moved from -0.22 at the prior report to +0.09, flipping from negative to modestly positive. Shares closed at $17.62 ahead of the release, up 9.0% from the open after the July report and 5.9% above the 200-day moving average of $16.63. The path was volatile. The stock peaked at $18.47 on September 2, then slid to $15.47 on October 12, and rebounded nearly 14% into the print. It entered earnings about 4.6% below its quarterly high. Earnings Whispers trend readings are mostly positive, with price, momentum, and AVWAP constructive while sequential growth is neutral.
The bottom line is that Bausch + Lomb's operating story improved decisively this quarter. Margins, cash generation, and deleveraging all moved well ahead of the Investor Day plan, and the steady 8% constant-currency growth rate provides a credible base. A tariff refund flattered the quarter modestly, and Surgical and Xiidra are cooling. The bigger unknown is governance. Until investors understand why the CEO left and what Bausch Health's role will be, the stock's multiple may lag the improvement in its fundamentals.
Read our earnings preview for Bausch + Lomb Corporation: https://www.earningswhispers.com/article/BLCO/20827
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-12 | |
| Oct-12 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Sep-11 | |
| Sep-02 | |
| Sep-01 | |
| Aug-26 | |
| Aug-24 | |
| Aug-07 |
