O-I Glass Swings To A Loss, Cuts 2026 Guidance Again And Pulls Its 2027 Target As Europe's Profit Nearly Vanishes
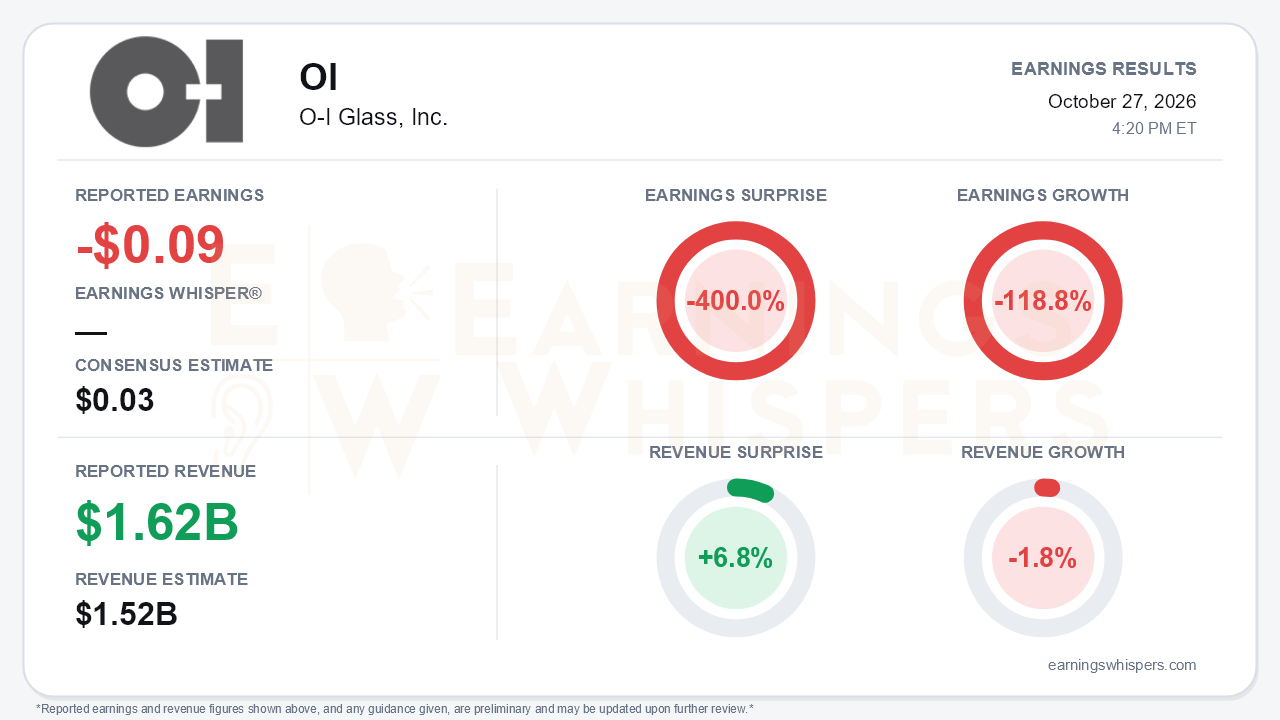
O-I Glass delivered a quarter in which the revenue beat was the least important number. The glassmaker reported a third-quarter loss of $0.09 per share, missing the $0.03 consensus estimate by 400.0% and falling 118.8% from a year ago. Revenue of $1.623 billion beat the $1.52 billion consensus by 6.8%, though it still declined 1.8% year over year. The more consequential news was elsewhere. Management cut 2026 guidance for a third consecutive quarter and withdrew the 2027 EBITDA target it had set only last quarter. That turns a disappointing quarter into a credibility problem for the company's restructuring narrative.
The earnings trajectory is clearly worsening. Adjusted EPS swung from $0.48 a year ago to a $0.09 loss, after second-quarter EPS had already fallen to $0.09 from $0.53. The company attributed part of the third-quarter loss to an unusually high tax rate, which flatters the operating picture somewhat. The segment results, however, leave little room to dismiss the miss as a tax anomaly. Europe produced just $2 million of segment profit versus $95 million a year earlier, down from an already weak $6 million in the second quarter. European sales fell 8%, with price and volume each down roughly 4%. Energy and freight costs ran about $15 million above plan. The Americas carried the quarter. Net sales there rose more than 3% to $970 million, helped by roughly 30% growth in Brazil beer and 18% growth in Andean non-alcoholic beverages. Even so, Americas segment profit slipped 2% to $137 million, and that figure included $6 million of non-recurring insurance compensation.
The guidance revisions show how far the plan has drifted:
- **Adjusted EBITDA:** The 2026 outlook now stands at $925 million to $950 million. That compares with an implied floor of roughly $1.0 billion in July and $1.25 billion to $1.3 billion in February.
- **Free cash flow:** The company now expects roughly $300 million of usage, versus the approximately $200 million inflow originally guided.
- **Volume:** Full-year volume is now expected to fall 3% to 4%, after earlier guidance of roughly flat.
- **Fit2Win savings:** 2026 net benefits were lowered to $180 million, from at least $200 million last quarter and at least $275 million at the start of the year.
- **Leverage:** Net leverage is heading to 4.5x to 5.0x at year-end, against a 2.5x target.
- **Inventories:** Inventories sit near 60 days versus a 50- to 52-day goal, adding working-capital strain.
The tone changed markedly. Last quarter, management described the situation as recalibrating timing, not strategy. This quarter, it called the results "unacceptable" and conceded that the European supply chain was "undercooked."
The call did preserve some building blocks for a 2027 recovery. New business wins have grown to about 4% of annual volume, up from roughly 1.5% in the first quarter and about 2% incremental in the second. Europe's fourth-quarter natural gas needs are fully covered, and 2027 coverage was extended at rates below the forward curve under a new five-year rolling hedge approach. Management said it expects energy inflation to crest in the first quarter of 2027. Other supports include:
- an additional proposed European plant closure;
- a new Brazil furnace coming online into 2027 with its volume largely placed;
- seven high-opportunity European plants still to go through the Fit2Win program;
- a maintained cumulative $650 million Fit2Win target, with at least $170 million slated for 2027.
Lower restructuring cash, versus roughly $160 million in 2026, and capital spending near $400 million underpin a target of positive free cash flow in 2027. Bears, however, have legitimate ammunition. Each of those benefits has been deferred before. The cumulative Fit2Win target was already cut from $750 million to $650 million in the second quarter. The 2027 EBITDA framework is now only directional, built on stable volume and positive net price, with formal guidance pushed to February. External pressures add to the uncertainty: the U.S.-Canada trade dispute is hurting North American volume, social unrest in France is weighing on consumers, and an Andean earthquake disrupted energy supply in South America.
Investors were already skeptical heading into the report, and that skepticism has deepened. Earnings Whispers investor sentiment fell from -0.20 at the prior report to -0.37, a meaningful move further into negative territory. The stock had slid 17.5% from the $7.79 open following the July report to $6.43, as of a snapshot taken on the release date and before the conference call. Shares sit 33.4% below the 200-day moving average of $9.65. That gap shows the market has been discounting a deteriorating plan for months rather than reacting to a single quarter. The Earnings Whispers trend readings lean negative, including a negative AVWAP trend, while the price trend is neutral.
The bottom line is that O-I's revenue beat does little to offset a quarter that undercut the core of the investment case. The company has now made three successive guidance cuts, Europe's profit has nearly disappeared, cash flow has swung negative, and leverage is approaching 5x. The Americas, new business wins and energy hedging give management a plausible path to a better 2027. Investors, though, are being asked to trust a recovery framework from a team whose targets have repeatedly slipped, and February's guidance will need to be hard numbers that hold.
Read our earnings preview for O-I Glass, Inc.: https://www.earningswhispers.com/article/OI/20783
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Oct-05 | |
| Aug-21 | |
| Aug-21 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-14 | |
| Jul-09 | |
| Jun-04 | |
| May-04 | |
| May-04 |
