OceanFirst Beats On Core Earnings As Flushing Integration Wraps, But A Softer Margin Path Keeps The Stock Below Tangible Book
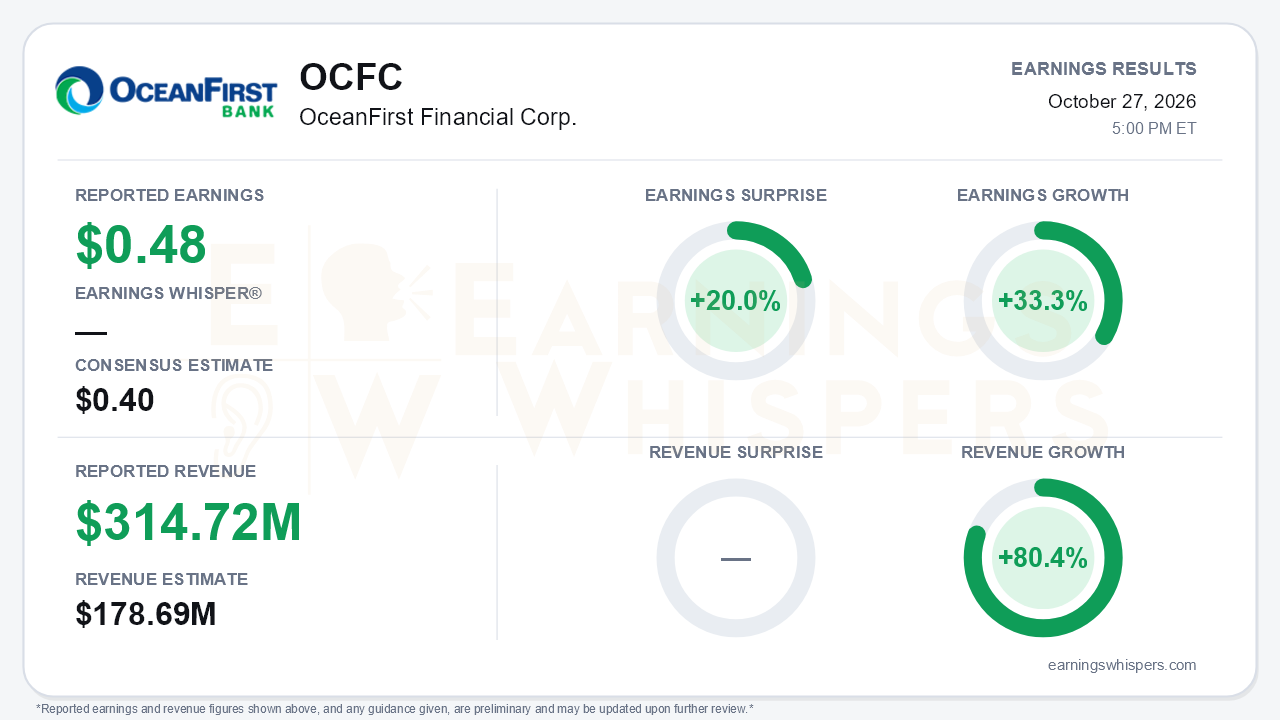
OceanFirst Financial delivered the clean first full quarter after the Flushing acquisition that investors needed. Core earnings of $0.48 per share beat the $0.40 consensus by 20.0% and grew 33.3% year over year. That marks a clear step up from $0.43 in each of the prior two quarters, after core EPS had been flat sequentially. Revenue of $314.72 million topped the $178.69 million consensus by 76.1% and rose 80.4%, a figure dominated by the four months of Flushing now in the numbers. GAAP results tell a noisier story. Net income available to common shareholders was $16.5 million, or $0.17 per share, versus $0.30 a year ago, depressed by $37.1 million of merger-related expenses (about $0.30 per share after tax). It was still a swing from the $0.04 loss in the June quarter. The central tension is that the operating engine is clearly improving, while the margin outlook and per-share capital metrics give skeptics something to hold onto.
The quality of the beat deserves some scrutiny. Net interest income jumped to $172.1 million from $120.7 million in the linked quarter, and reported margin widened to 3.18% from 3.05%. That figure was flattered by 16 basis points of purchase accounting accretion and $5.5 million of non-recurring interest recoveries on a non-performing investment and loan acquired from Flushing. Those recoveries were not stripped out of core earnings. Management pegged the underlying margin closer to 3.08%. The expense side, by contrast, was the genuine standout. Core operating expenses of $114 million came in well below the $120-125 million range guided last quarter. The core efficiency ratio improved to 61.75% from 70.30% a year ago, and core return on tangible common equity reached 10.35%. Higher tax drag also hit GAAP results, with non-deductible merger costs pushing the effective rate to 44.2%.
Underneath the accounting, organic growth reaccelerated. Loans grew $215.7 million, about 5% annualized, driven by $325 million of commercial growth. Commercial originations climbed to $735 million from $642 million in the second quarter and $429 million in the first, and the pipeline expanded to $541 million from $409 million. Deposits rose $319 million. The Premier Bank team posted its strongest quarter, adding $181 million to reach $674 million, after gains of $150 million and $9 million in the prior two quarters. Management lifted its growth outlook to 1-2% per quarter, versus 1-2% for the entire second half previously. It also guided fourth-quarter expenses to $110 million, the low end of its prior range, and set a base of roughly $105 million from early 2027. The hire of former Signature executive Eric Howell to lead Premier Bank adds a credible lever for faster team recruitment.
The forward picture is not uniformly brighter. Guidance now assumes a December rate hike, deposit costs rising about 10 basis points per quarter and a roughly 40% deposit beta. That leaves the fourth-quarter margin stable to modestly higher off the 3.08% core base, near the low end of the prior 3.09-3.14% range. Funding pressure is already visible: total deposit costs rose to 2.17% from 2.06%, and brokered time deposits grew to $1.05 billion from $886 million. Management acknowledged roughly a $5 million quarterly gap to its 2027 EPS goal and said the 3.25% margin target may take longer. It also flagged that the Premier deposit target could slip a quarter or two. Offsetting tailwinds include more than $1 billion per quarter of fixed-rate asset repricing and at least $1 billion of securities runoff over 12-18 months to fund loans and pay down wholesale funding. Credit looks contained. Reported non-performing loans rose to 0.85% of loans on acquired purchased-credit-deteriorated (PCD) loans, but they were just 0.37% excluding those loans, and net charge-offs ran at an annualized 0.04%.
The market setup is more complicated than the surprise implies. Shares closed at $16.67 heading into the release, down 12.4% since the open following the July report. That leaves the stock 9.8% below its $18.47 200-day moving average and below tangible book value of $18.08 per share. Earnings Whispers investor sentiment, already negative, weakened meaningfully to -0.38 from -0.22, and the price and AVWAP trend readings remain negative. That discount to tangible book is precisely why management is leaning into buybacks. It has 3.2 million shares remaining under authorization and expects to resume excess capital accretion this quarter, even as tangible book per share and the CET1 ratio of 10.6% both slipped modestly on merger costs and securities marks.
The bottom line is that OceanFirst removed its biggest near-term risk by completing the Flushing integration on schedule, while delivering an expense beat and reaccelerating loan and deposit growth. Bears still have legitimate ammunition: a margin path now tied to a rising-rate assumption, a self-identified gap to 2027 earnings goals, and a core beat helped by accretion and one-time recoveries. With sentiment souring and the stock below both its 200-day average and tangible book, the burden now shifts to the next few quarters to prove that cost savings and repricing can outrun deposit-cost pressure.
Read our earnings preview for OceanFirst Financial Corp.: https://www.earningswhispers.com/article/OCFC/20782
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-27 | |
| Oct-05 | |
| Aug-10 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-07 | |
| Jun-29 | |
| Jun-08 | |
| Jun-01 | |
| Apr-27 | |
| Apr-25 |
