Universal Health Realty Holds FFO Flat At $0.88 As A GAAP Lift Masks A Stalled Core And Tenant UHS Flags Palm Beach Gardens Strain
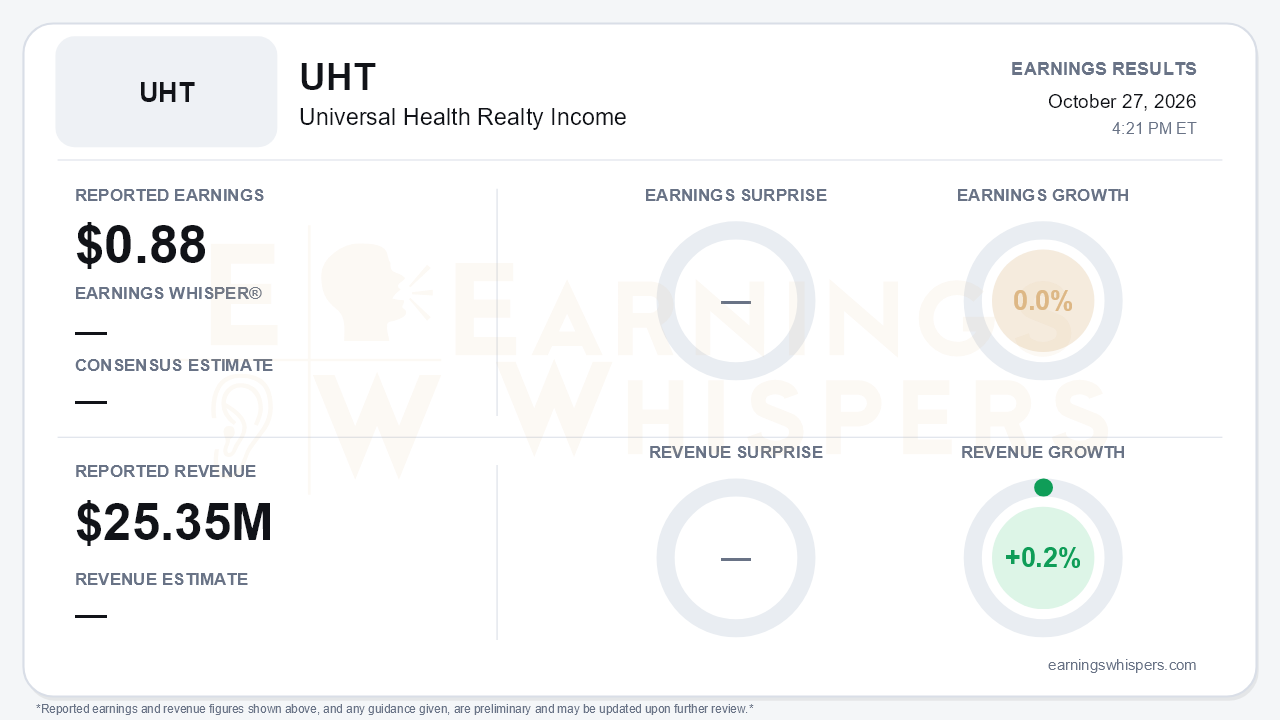
Universal Health Realty Income Trust (NYSE: UHT) delivered a quarter defined by stability rather than progress. Funds from operations were $0.88 per diluted share on revenue of $25.35 million, with earnings growth of 0.0% year over year and revenue growth of just 0.2%. No consensus estimate or Earnings Whisper was available, so the quarter cannot be framed as a beat or a miss. The central takeaway is that the core portfolio is treading water while the more interesting signals sit in the balance sheet, the development pipeline and the condition of its key tenant.
The quality of the GAAP improvement deserves scrutiny. Net income rose to $4.9 million, or $0.35 per diluted share, from $0.29. Most of that $913,000 gain came from the absence of roughly $900,000 of nonrecurring depreciation booked in the year-ago quarter. Interest expense also fell by $287,000 as a lower effective borrowing rate, helped by swaps, more than offset higher average borrowings. Those gains were partly offset by a $275,000 one-time settlement benefit in Q3 2025 that did not recur. Strip out the accounting noise and FFO rose only $53,000, to $12.3 million. Beneath the headline, lease revenue from non-related parties edged up to $14.9 million from $14.8 million. Other operating expenses climbed to $7.9 million from $7.6 million, and other revenue from non-related parties fell to $421,000 from $577,000. One modest bright spot was bonus rent at UHS's McAllen Medical Center, which rose to $1.0 million from $895,000. Year to date, FFO improved to $2.67 from $2.59, so the flat third quarter represents a deceleration from the first half.
The balance sheet is quietly getting heavier. Credit-line borrowings rose to $377.7 million from $356.2 million at year-end, leaving $97.3 million of capacity on the $475 million facility, which matures in 2028. Total equity declined to $139.5 million from $152.4 million because dividends continue to exceed GAAP net income. The quarterly dividend was raised to $0.75 from $0.74, which is about 85% of the quarter's FFO. That payout is covered but leaves limited room if core income stays flat while borrowing grows. Lower rates have been doing the heavy lifting on interest expense. Management's own risk language warns that further rate increases could significantly hurt results.
The forward story centers on two items. First, the October sale of a Chicago land parcel for $1.96 million is expected to produce a gain of roughly $1.90 million in the fourth quarter. That will flatter GAAP net income but is excluded from FFO. Second, the roughly $34 million Miller Medical Plaza, an 80,000-square-foot medical office building, is slated for completion in December 2026. A UHS subsidiary has signed a 10-year master flex lease covering about 75% of the space, which should add income once the building is delivered.
The supplied conference-call material introduces a source conflict that investors should understand. That analysis references the Talkspace acquisition, adjusted EBITDA guidance of $2.61-2.72 billion and $690 million of buybacks. Those details describe Universal Health Services (UHS), UHT's advisor and largest tenant, not the trust itself. It should not be read as UHT management commentary, but it is directly relevant.
- **Palm Beach Gardens:** UHS said its hospital there is ramping more slowly than expected and lost about $15 million in the quarter. That is the campus where the Miller Medical Plaza sits. The flex lease shrinks as third-party leases are signed, and a slow hospital ramp could plausibly make third-party leasing harder. That last point is an inference, not a disclosed fact.
- **2027 headwinds:** UHS steered 2026 results toward the low end of guidance. It also quantified a $175-200 million Medicaid supplemental-payment headwind and at least $15 million of exchange pressure for 2027. Its leverage rose to 2.17x from 1.8x.
- **Offsetting strength:** On the positive side, UHS reported acute same-facility admissions up 4.9% and stronger operating cash flow.
Those UHS headwinds echo the Medicaid and exchange-subsidy risks cited in UHT's own release. Rent coverage is not in immediate question, but tenant health is the trust's most important long-run variable.
Market context is thin. Investor sentiment readings and a current price were not available. Shares opened at $44.83 after the July report, and the 200-day moving average now sits at $41.12. Without current pricing, it is not possible to say whether the stock has held above that level.
The bottom line is that UHT produced a steady, dividend-covering quarter with no real core growth. The GAAP gain was largely an accounting comparison, and borrowing continues to rise. The next leg of growth depends on the Miller Medical Plaza, whose prospects are tied to a UHS hospital currently ramping slower than planned.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Sep-21 | |
| Sep-08 | |
| Jul-27 | |
| Jul-27 | |
| Jun-10 | |
| Jun-05 | |
| Apr-27 | |
| Apr-27 | |
| Mar-11 | |
| Mar-02 | |
| Feb-26 | |
| Feb-25 |
