Universal Health Services Misses As Volume Surge Collides With Pricing Erosion, Low-End Guidance And Newly Quantified 2027 Headwinds
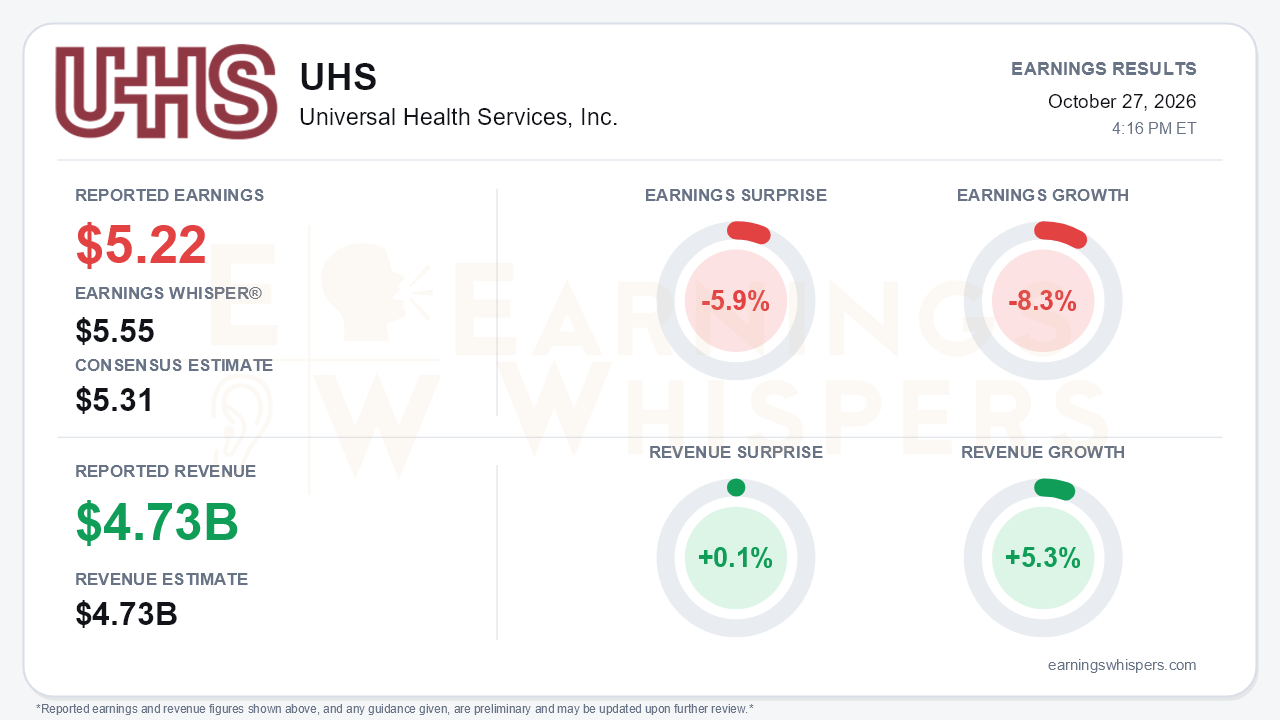
Universal Health Services delivered a third quarter in which patient volumes accelerated but earnings went the other way. Earnings of $5.22 per share missed the $5.31 consensus by 5.9% and fell well short of the $5.55 Earnings Whisper number. Revenue of $4.733 billion was essentially in line, edging past consensus by 0.1%. Earnings fell 8.3% year over year, a sharp reversal after management cited adjusted EPS growth of 12% in the second quarter and 16% in the first. Revenue grew 5.3%. That is the central tension: UHS is filling more beds, but each admission is producing less, costs are absorbing the growth, and the rest of 2026 now points toward the bottom of an outlook that was already lowered once.
The quality of the quarter looks weaker than the headline. Results included a net favorable pre-tax impact of about $21 million that was not in the July forecast: $47 million of expanded Medicaid supplemental payments, mainly from Washington, D.C. and California, offset by a $26 million professional-liability reserve tied to the tentative Cumberland litigation settlement. Management also cited about $8.5 million of Talkspace deal costs. Excluding these items, management acknowledged that results came in below internal expectations. Adjusted EBITDA net of NCI fell to $624.6 million from $670.6 million, and its margin compressed to 13.2% from 14.9%. Same-facility operating margins fell in both segments:
- Acute care declined to 11.3% from 12.8%.
- Behavioral health declined to 17.9% from 19.3%.
Below the operating line, net interest expense rose to $56.3 million from $38.4 million after Talkspace-related borrowing. The diluted share count fell about 7% to 59.1 million, so per-share results held up better than net income.
The call explained where the operating leverage went. Acute same-facility adjusted admissions rose 4.9%, up from 2.9% in Q2 and flat in Q1, helped by 177 new beds and a 4.6% increase in ED visits. Pricing moved in the opposite direction. Acute revenue per adjusted admission fell 1.7%, compared with gains of 3.0% in Q2 and 6.3% in Q1, for three reasons:
- Surgeries declined 0.7% as GI and orthopedic cases keep moving to ASCs and physician offices.
- An adverse medical-surgical mix shaved roughly 100 basis points from pricing.
- Exchange volumes dropped 17% as patients shifted to self-pay.
Behavioral patient days improved to 2.1% growth from 1.4%. Behavioral pricing growth, however, slowed to 2.1% from 6.1% in Q2. The clearest positive was labor. Behavioral salaries, wages and benefits per patient day grew 3.6%, down from 4.8% in Q2 and roughly 6% in Q1, with headcount up about 1.5%.
The forward picture deteriorated more than the quarter itself. Management reiterated 2026 guidance but now expects results toward the low end of the $2.61 billion to $2.72 billion adjusted EBITDA range, which had already been cut by about $50 million in July. Several de novo facilities are lagging:
- Cedar Hill's break-even slipped from Q4 2026 to the first half of 2027.
- Palm Beach Gardens lost about $15 million in the quarter while ramping slower than planned.
Management also quantified 2027 headwinds for the first time. These include $175 million to $200 million in lower Medicaid supplemental payments and at least $15 million from exchange changes, with Medicaid work requirements still unquantified. Expansion-state Medicaid accounts for roughly 15% of acute adjusted admissions and 30% of behavioral patient days. On the other side, management pointed to several potential 2027 offsets:
- Recovery of $80 million to $100 million in 2026 losses at Laurel Ridge, Cedar Hill and Palm Beach Gardens.
- Laurel Ridge recertification.
- Capex falling to about $800 million from roughly $1 billion.
- Talkspace revenue synergies, expected within 12 to 24 months.
Cash generation was a genuine bright spot. Q3 operating cash flow was $637 million versus $381 million a year ago. Even so, leverage rose to 2.17x from about 1.8x after the Talkspace financing.
Investor sentiment entered the report negative but less so than three months earlier, improving modestly from -0.15 to -0.07. The stock has rallied 18.6% since the open after the July report, to $177.32. It now sits essentially on its 200-day moving average of $177.54. Earnings Whispers price and AVWAP trend readings are positive, reflecting that recovery. Shares therefore came into the report having already priced in a fair amount of stabilization, which leaves a below-whisper miss and low-end guidance with less cushion. Notably, the company repurchased 1.35 million shares in Q3 at an average price of about $179, close to where the stock trades today.
The bottom line is that UHS solved its volume problem just as pricing, mix and de novo execution became the bigger issues. Bulls can point to accelerating admissions, moderating labor inflation, strong cash flow and a capex step-down. Bears have legitimate ammunition in a decelerating earnings line, lower-quality profits propped up by supplemental payments, slipping facility timelines and a 2027 reimbursement headwind that now carries a real dollar figure. With the stock parked at its 200-day average after a strong run, the 2027 guidance due in February is likely to be the next decisive test.
Read our earnings preview for Universal Health Services, Inc.: https://www.earningswhispers.com/article/UHS/20805
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-09 | |
| Oct-05 | |
| Aug-25 | |
| Aug-17 | |
| Aug-17 | |
| Jul-29 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 | |
| Jul-15 | |
| Jul-14 | |
| Jul-08 |
