Scorpio Tankers Beats Despite A Summer Lull, And Q4 Bookings Above $180,000 A Day For LR2s Point To A Sharp Rebound
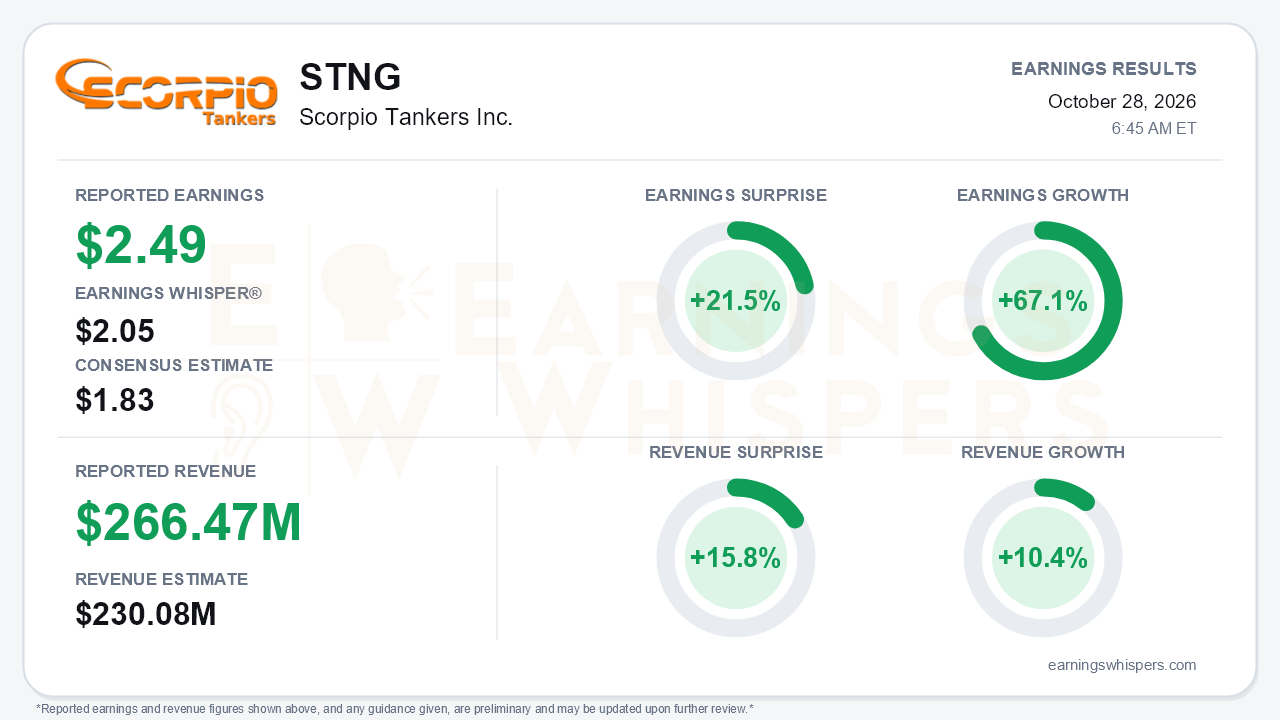
Scorpio Tankers delivered a clear beat in what was its weakest quarter of 2026. Adjusted diluted earnings of $2.49 per share topped the $1.83 consensus by 21.5% and cleared the $2.05 Earnings Whisper number. Earnings grew 67.1% year over year. Revenue of $266.47 million beat the $230.08 million consensus by 15.8% and grew 10.4% from a year ago. The central tension is that the quarter marked a sharp sequential step down from a record second quarter, while the outlook for the fourth quarter improved dramatically. Management backed that outlook by raising the quarterly dividend 67%, from $0.45 to $0.75.
The quality of the beat deserves some unpacking. IFRS net income was $224.3 million, or $4.60 per diluted share, but that figure includes a $152.6 million gain on vessel sales. It also absorbed a $55.6 million non-cash loss on the conversion derivative embedded in the convertible notes, a charge that rises as the share price rises. Stripping out both leaves adjusted net income of $127.4 million. That is still well ahead of last year's $72.7 million, but roughly half of the $243.7 million earned in the second quarter. Adjusted EBITDA showed the same pattern: $172 million, up from $148 million a year ago but down from more than $300 million in Q2. The year-over-year gains are notable because the fleet shrank considerably. Average vessels fell from 99.0 to 75.1 after 26 ship sales. Even so, fleet TCE per day rose to $37,508 from $26,231, led by LR2s at $55,184 versus $31,482. Not every line improved. Operating costs per day rose to $8,678, and G&A climbed to $37.0 million on higher compensation costs.
The conference call is where the story turned. Rates rose steadily through the quarter and then surged after it ended:
- MR earnings went from about $29,000 a day in July to $53,000 in October and roughly $70,000 in early November.
- LR2 earnings moved from about $55,000 in July to $168,000 in October and roughly $215,000 in partial November fixtures.
- Fourth-quarter bookings to date stand at about $181,000 a day for LR2s on 44% of days, $56,000 for MRs on 47%, and $40,000 for Handymaxes on 37%.
At the Q2 call, quarter-to-date LR2 rates had been only about $65,000. Management's demand case also changed character. It moved from ton-mile arguments that offset falling volumes to outright volume growth. Middle East crude exports have roughly doubled to about 17 million barrels per day, global refinery runs are up about 4 million barrels per day, and seaborne product exports reached 20.6 million barrels per day in September. On supply, roughly 70% of LR2s are now trading crude, and management cut its estimate of effective clean fleet growth to as little as 1%. The tone shifted with the data, from Q2's warning that records aren't meant to last to a declaration that the party hasn't started.
The balance sheet gives management room to act on that view. Net cash rose to about $1.4 billion, or roughly $27 per share, after the 7.5% notes were redeemed. Remaining debt of $655 million is mostly a low-coupon convertible, and cash break-even is below $11,000 a day. Bears still have legitimate ammunition:
- Newbuilding and joint-venture commitments climbed to about $1.3 billion, from $978 million in Q2 and $641 million in Q1. Four VLCCs and a Volare stake push the company beyond its product-tanker core, although management says the commitments can be funded without debt.
- Refining margins are retreating from record highs.
- Inventory restocking has been pushed out to late 2027.
- The rally depends heavily on Hormuz and Red Sea disruption, and similar rate spikes have reversed quickly before.
- Shares above the roughly $99 conversion price would bring dilution from the convertible into play.
Investors were not leaning into the story ahead of the report. Earnings Whispers sentiment, measured on a scale of -1 to +1, slipped from roughly neutral at -0.06 to -0.21, a meaningful though not extreme shift toward caution. The price action has been firmer than that sentiment suggests. As of October 27, the day before the report, shares were at $85.33. That is up 10.8% from the open after the July report and about 11.6% above the 200-day moving average of $76.43. The stock sat 5.3% below the $90.06 52-week high set on September 17 and 16% above the August low. Among the internal trend readings, AVWAP is positive while price and momentum are neutral.
The bottom line is that Scorpio's third-quarter beat matters less than what came after it. Earnings decelerated sharply from Q2, and the GAAP figure depends heavily on asset-sale gains. However, fourth-quarter bookings near triple the Q3 LR2 average, a 67% dividend increase, and $1.4 billion of net cash give the upbeat outlook real substance. The open question is durability: the rate surge depends on geopolitical dislocation, and capital commitments are growing quickly.
Read our earnings preview for Scorpio Tankers Inc.: https://www.earningswhispers.com/article/STNG/20881
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-19 | |
| Sep-29 | |
| Sep-15 |
IBD Stock Of The Day Scorpio Tankers Sails Toward Buy Point As Oil-Needy World Seeks Its Services
STNG
Investor's Business Daily
|
| Sep-03 | |
| Aug-17 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-20 | |
| Jul-01 | |
| Jun-18 |
