Chefs' Warehouse Beats And Raises Again As Margin Gains Outrun A Cooling Top Line
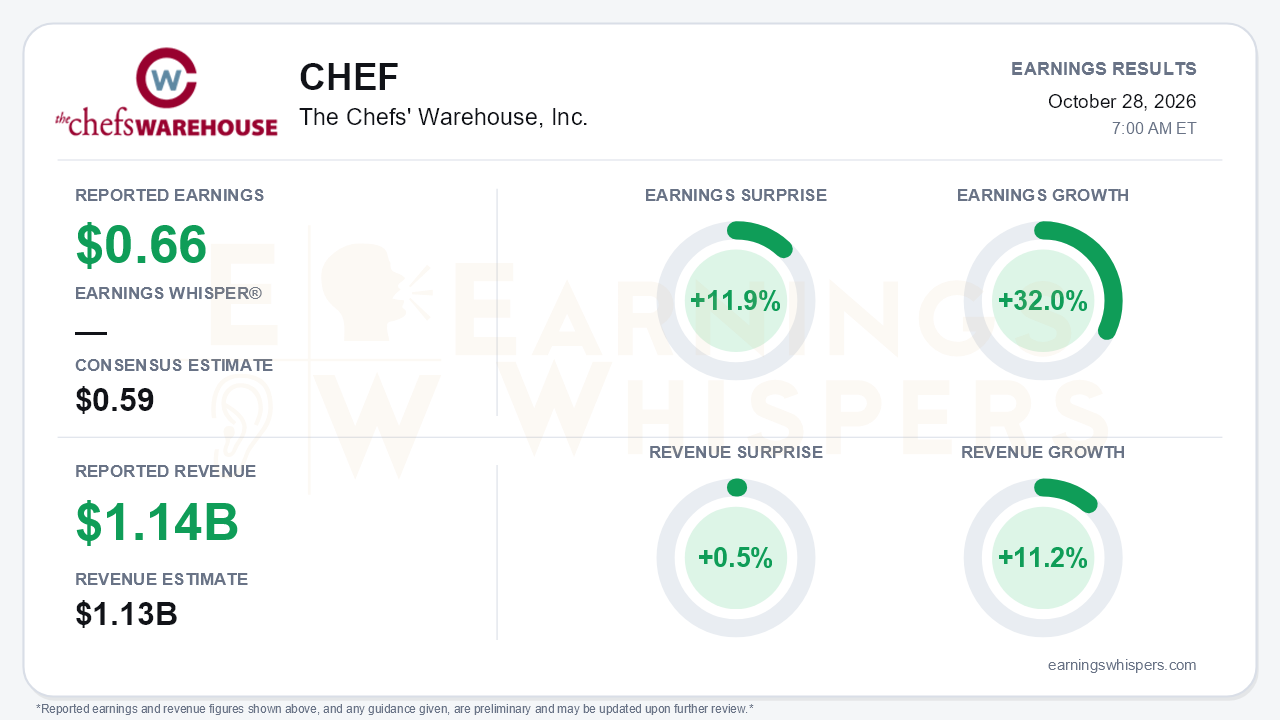
The Chefs' Warehouse delivered a clean beat-and-raise third quarter. Adjusted earnings of $0.66 per share topped the $0.59 consensus by 11.9% and grew 32.0% year over year. Revenue of $1.135 billion rose 11.2% but beat expectations by only 0.5%. That gap is the central tension. Earnings are being driven increasingly by margin rather than volume, and the volume engine eased from its second-quarter pace. Management raised full-year guidance for the second straight quarter, but the new targets were in line with estimates rather than ahead of them. The report extends a credible profitability story more than it changes it.
The quality of the earnings beat holds up well. Gross profit climbed 15.0% to $284.3 million, and gross margin expanded 84 basis points to 25.0%. That expansion was wider than the 49 and 53 basis points of the prior two quarters. Center-of-the-plate margins rose 137 basis points and specialty margins rose 63 basis points, which management credited to product mix, procurement scale and AI-driven pricing tools. Operating margin improved to 4.4% from 3.8%, and adjusted EBITDA rose 26% to $82.2 million.
GAAP EPS of $0.67 slightly exceeded the adjusted figure. That reflects a small other-operating gain and a discrete tax benefit tied to stock vesting. The adjusted number, by contrast, was taxed at a normalized 31% rate versus 28% a year ago, so the adjusted growth came despite a tax headwind. Investors should note that stock compensation nearly doubled to $9.3 million. It is added back to adjusted EBITDA but not to adjusted net income. Year-to-date operating cash flow of $141.1 million, up from $55.4 million, adds further credibility to the earnings.
The top-line detail is softer. Organic growth slowed to 10.3% from 12.2% in the second quarter, roughly back to the first quarter's 10.4%. Within that:
- Specialty organic growth eased to 8.4% from 10.0%.
- Center-of-the-plate pounds rose 6.6%, down from 8.8%.
- Specialty inflation cooled to 2.6% from 4.0%, so part of the slowdown is price rather than demand.
Customer acquisition actually improved. Unique customers grew 5.7% excluding the Middle East, up from 4.9% in the second quarter and 4.3% in the first. Operating leverage came entirely from gross margin. Fuel costs pushed adjusted opex to 17.8% of sales from 17.5%, and not all of that cost was passed through. Management also flagged pockets of softness, including conference attendance down 10–12% and weaker à la carte activity at private clubs.
The forward picture contains both catalysts and caveats. On the positive side:
- **Middle East recovery:** Revenue has returned to roughly 100% of prior-year levels, up from about 94% in the second quarter and 75% in the first.
- **October trends:** Management said October continued at double-digit growth.
- **Margin target pulled forward:** Raised guidance of $317–321 million in adjusted EBITDA, up from $305–315 million, implies a margin of about 7%. That reaches the company's 2028 target two years early.
- **Refinancing and share count:** The October $675 million term loan retired the 2028 convertible notes. Diluted shares are guided to 43–43.5 million in the fourth quarter and 42–43 million in 2027, down from about 46 million, which is a meaningful per-share tailwind.
The trade-off is leverage, which is expected to rise to 1.7–2.0x by year-end from 1.4x, along with roughly $2.7 million of one-time fourth-quarter interest expense. The fourth-quarter guide also implies a slowdown. Management attributed it to lapping the Italco acquisition, a roughly one-point tougher comparison, and caution about December tourism in the Middle East.
Investor sentiment moved the opposite way from the fundamentals. It slid from essentially neutral (-0.04) to modestly negative (-0.22) ahead of the report, a meaningful but not extreme deterioration. Price action helps explain the caution. Shares are up 8.8% since opening at $100.17 after the July report, which marked the inter-earnings low, and they remain about 26% above the 200-day moving average. However, the stock set a 52-week high of $118.51 on October 2 and has since given back about 8%. The Earnings Whispers trend readings are mixed: momentum is positive while AVWAP is negative. That mix fits a stock that has rallied substantially and is now digesting the move.
The bottom line is that Chefs' Warehouse is executing well on the parts of the model it controls: gross margin, procurement, customer wins, cash generation and capital structure. The decelerating organic growth, cooling inflation and in-line guidance raise give bears legitimate ammunition. Those factors also explain why sentiment soured even as estimates rose. The setup now depends less on volume and more on whether margin expansion and a shrinking share count can keep per-share earnings compounding while the top line normalizes.
Read our earnings preview for The Chefs' Warehouse, Inc.: https://www.earningswhispers.com/article/CHEF/20831
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-14 | |
| Sep-11 | |
| Aug-19 | |
| Aug-18 | |
| Aug-12 | |
| Aug-04 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| Jul-07 |
