AerCap Crushes Estimates And Raises Guidance A Third Time, But Sale Gains And Maintenance Windfalls Carry The Beat
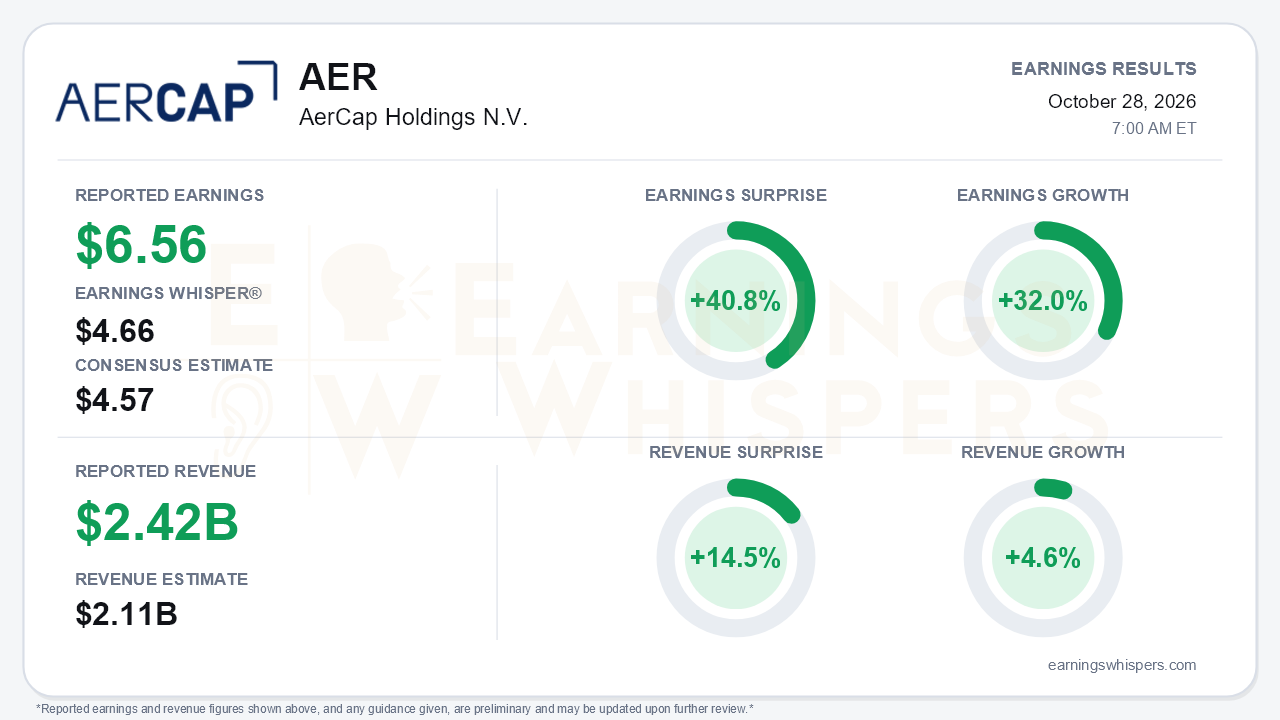
AerCap delivered a quarter that was hard to argue with on the surface. Adjusted earnings of $6.56 per share topped the $4.57 consensus by 40.8% and cleared the $4.66 Earnings Whisper number by a wide margin. Revenue of $2.415 billion beat the $2.11 billion estimate by 14.5%. Adjusted EPS grew 32.0% year over year and accelerated sharply from $5.14 in the second quarter and $5.39 in the first. Management also raised full-year adjusted EPS guidance for the third straight time, to roughly $20.70 from $16.80 just three months ago, before any fourth-quarter gains on sale. That is the central tension: the earnings power on display is real, but a large share of it came from sources management itself expects to fade.
The quality of the beat deserves scrutiny. Basic lease rents, the recurring core of the business, were $1,698 million, essentially flat with $1,690 million a year ago, although up from $1,677 million in the second quarter. The upside came elsewhere:
- **Gains on sale** reached a record $353 million on $1.1 billion of asset sales across 70 assets. That is a 45% unlevered margin, up from 20% in Q2 and 24% in Q1.
- **Maintenance rents and other receipts** jumped 31% to $267 million.
- **Buybacks** shrank the diluted share count to 153.9 million from 174.1 million a year earlier, which flattered per-share growth.
- **The tax rate** was a favorable 12.3%, below the roughly 15% full-year expectation.
Total revenue grew just 4.6% year over year, below the 9% pace for the first nine months. GAAP EPS of $6.17 actually fell from $6.98, although the prior-year figure included $475 million of Ukraine-related insurance recoveries.
The call made the normalization question explicit. Net maintenance contribution has totaled $453 million year to date, including $184 million in Q3. Management guided it back to about $50 million per quarter in 2027. Full-year asset sales are now expected above $5 billion, up from an initial $2-3 billion range. However, management said sales should normalize to $2.5-3 billion annually once the China exposure reduction winds down. Net spread was 8.1% versus 8.0% a year ago, and management expects it to stay roughly flat near term. Its explanation is that a higher cost of debt, now 4.2% versus 4.0%, offsets lease-rate gains. The more durable signal is the higher core outlook: management lifted EPS excluding gains to roughly $16, from about $14 in Q2 and $13 in Q1. That suggests the underlying franchise is improving, not just the trading income.
The forward catalysts lean constructive:
- The order book is fully placed through 2027 and 80% placed through 2028, including 131 aircraft added this year.
- Spirit aircraft returning to lease should support gradual net spread expansion.
- MAX 10 certification could improve Boeing's narrowbody competitiveness.
- A new $1 billion buyback follows more than $2.2 billion repurchased in 2026, roughly 10% of shares. With leverage at 2.0x versus a 2.7x target, AerCap retains plenty of balance-sheet capacity.
- Book value per share rose to $124.89 from $109.22 a year ago.
Higher jet fuel is now the dominant macro theme, a shift from the more wait-and-see framing earlier in the year. Management sees it cutting both ways. Fuel costs are pressuring long-haul low-fare carriers and could reduce flying of older aircraft. They could also generate sale-leaseback demand as airline liquidity tightens, which management expects to intensify in the new year. Bears have legitimate ammunition in appraiser views that narrowbody midlife values and lease rates may have peaked. That would directly threaten the gain-on-sale engine that powered this quarter.
Investor expectations had already soured heading into the report. Earnings Whispers sentiment swung from a positive 0.33 after the prior report to a negative 0.32. That is a substantial deterioration, and it suggests investors were bracing for fuel-driven airline stress rather than another raise. The stock reflected that caution without breaking down. At $150.05, shares were down 3.2% from the $155 open after the July report and 5.5% below the 52-week high of $158.81 set on August 5. They were still 4.0% above the 200-day moving average and 9.7% above the September 15 low of $136.77. The Earnings Whispers trend readings are mixed: momentum and AVWAP are positive, while the sequential growth trend is negative.
The bottom line is that AerCap delivered a decisive beat and a credible guidance raise, and the rising core EPS outlook gives the story more substance than a pure gain-on-sale spike. Still, the headline masks a flat lease-rent base and windfalls that management explicitly expects to normalize in 2027. Turning sentiment back positive will likely require evidence that buybacks, order-book growth, and fuel-driven sale-leaseback opportunities can bridge that gap.
Read our earnings preview for AerCap Holdings N.V.: https://www.earningswhispers.com/article/AER/20821
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 5 hours | |
| 6 hours | |
| 10 hours | |
| Oct-05 | |
| Oct-05 | |
| Sep-23 | |
| Aug-26 | |
| Aug-14 | |
| Aug-06 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-21 |
