First Financial Bancorp Posts Record Earnings And Raises Margin Outlook, But Rate Hikes Hit Tangible Book And Loan Growth Cools
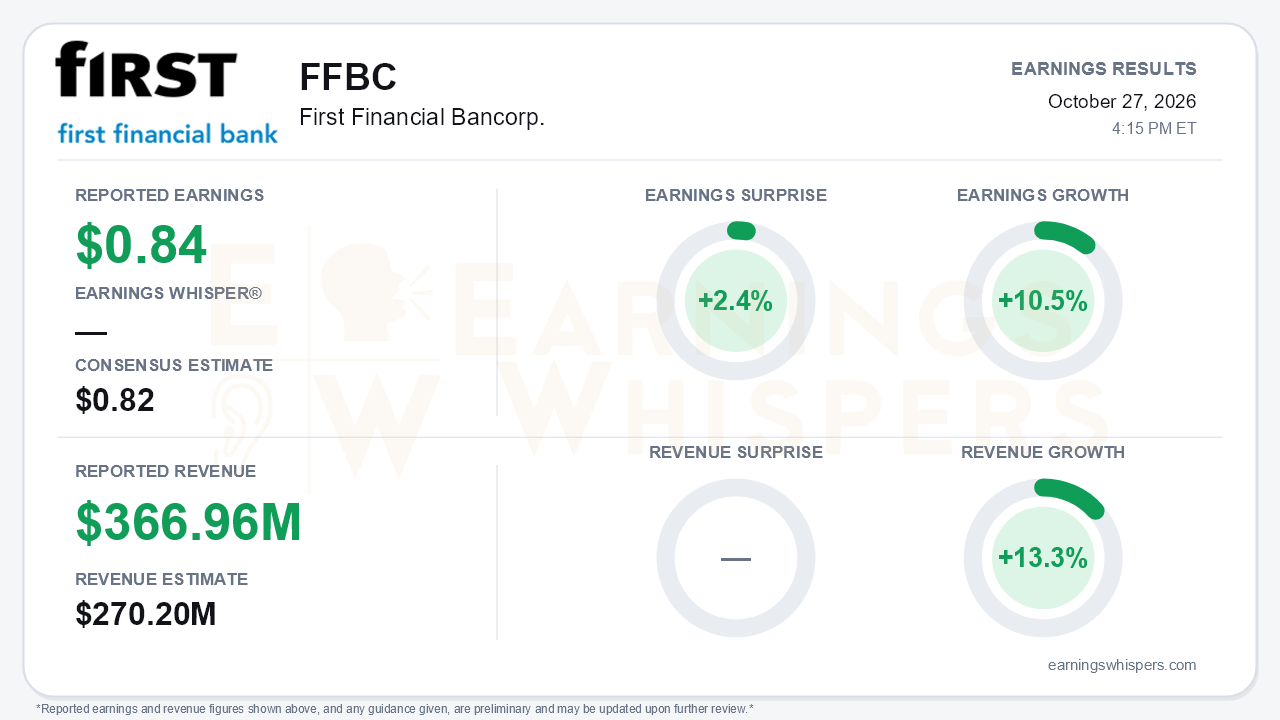
First Financial Bancorp delivered the best earnings quarter in its history. Adjusted EPS of $0.84 topped the $0.82 consensus by 2.4% and grew 10.5% year over year. The quarter also extended a clean sequential climb in adjusted EPS, from $0.77 in the first quarter to $0.80 in the second and $0.84 now. GAAP EPS was $0.77, with the gap driven mainly by $7.5 million of acquisition-related costs tied to the pending Finward deal. The same rising-rate backdrop that is lifting earnings is also eroding the balance sheet, and that is the central tension. Net interest margin and fee income beat management's own targets. Tangible book value, loan growth expectations and classified assets all moved the wrong way.
The headline revenue comparison needs context. Earnings Whispers shows revenue of $366.96 million, up 13.3% year over year and 35.8% above the $270.2 million consensus. That figure reflects gross interest income plus noninterest income. The company's own measure, record net revenue of $273.9 million, is the more relevant comparison against consensus and points to a modest top-line beat rather than a blowout. The quality of the beat still holds up.
- **Margin:** Fully tax-equivalent NIM rose 9 basis points to 4.07%, above the 3.96%-4.01% range guided on the prior call. Asset yields rose 13 basis points, outpacing a 4-basis-point increase in funding costs.
- **Net interest income:** Net interest income reached $196.3 million, up 22.3% from a year ago as recent acquisitions added scale.
- **Fees:** Adjusted fee income hit a record $77.6 million, or 28% of revenue, beating the $74-77 million guide. Foreign exchange income jumped 33.5% sequentially, and wealth management, bankcard and client derivative fees each grew by double digits.
- **Expenses:** Adjusted expenses of $156.9 million overshot the plan. Management attributed the overrun to incentive pay tied to record revenue, plus higher healthcare and collection costs.
The call lifted the near-term earnings outlook but trimmed the growth outlook.
- **Raised:** Management raised fourth-quarter NIM guidance to 4.08%-4.12%, assuming a December rate hike. It estimated each 25-basis-point hike adds roughly 7-8 basis points of margin initially, settling at 3-4 basis points. FX guidance rose to $18-20 million from $15-17 million, and total fee guidance is $75-78 million.
- **Loans:** Loan growth slowed to about 5% annualized from 7% in the second quarter. Fourth-quarter guidance eased to low-to-mid single digits, well short of the 6%-8% full-year target set at the start of the year. C&I growth was strong and broad-based across Chicago and Northeast and Southwest Ohio. CRE is softening, however, with weaker multifamily production, intensifying industrial competition, thinner spreads and looser structures.
- **Leasing:** Leasing revenue guidance slipped to $21-23 million.
- **Funding:** Public fund deposits are leaving for higher-yielding alternatives, and Oak Street payoffs remain a drag.
Bears have legitimate ammunition on credit and capital. Classified assets jumped to $281.4 million, or 1.26% of assets, from $226.8 million, mostly because of one ICRE relationship tied to a borrower bankruptcy. CRE nonaccruals rose to $53.9 million from $44.4 million, and CRE gross charge-offs climbed to $5.1 million. Overall net charge-offs held at 21 basis points and nonperforming assets at 0.45%, so this looks like a contained workout rather than broad deterioration. Management expects to resolve it over the next few quarters.
The capital hit is more visible. Higher long-term rates pushed AOCI losses to $387 million, cutting tangible book value per share 6% to $15.65 and the TCE ratio 43 basis points to 7.81%. The rate marks also stretched the Finward tangible book earnback to roughly 0.9 years from 0.6. Regulatory capital ratios all improved, however, with CET1 at 12.54%. The buyback flagged last quarter went unmentioned, though the dividend rose to $0.26.
Forward catalysts are concrete:
- federal approval for Finward, with a January 1, 2027 close targeted, pending state and Finward shareholder approvals;
- a leadership restructuring that elevates Jamie Anderson to President and CFO;
- additional margin lift if the Fed hikes again.
Investors entered the report with tempered enthusiasm. Earnings Whispers sentiment slipped from essentially neutral to modestly negative, a meaningful but not dramatic shift. The stock tells a similar story. Shares reached $36.18 during the third quarter but closed September at $31.32, roughly where the TBV decline and rate shock left them. At $32.54, the stock is down 2.1% since the open after the July report, despite a quarter of record profits. It remains 5.4% above its 200-day moving average of $30.86, so the longer-term trend has not broken. AVWAP readings remain negative, consistent with a stock that has given back its mid-quarter gains.
The bottom line is that First Financial's earnings engine is running at its strongest level ever, with margin, fees and returns all exceeding management's own targets. That strength is increasingly a rate story rather than a volume story. Loan growth guidance has been cut twice from the year's original target, CRE competition is intensifying, and rising rates are pressuring tangible book as much as they help NIM. Investors weighing the stock must decide whether near-term margin upside and the Finward close outweigh slowing balance sheet growth, a credit workout still in progress and weaker tangible capital heading into a dilutive acquisition.
Read our earnings preview for First Financial Bancorp.: https://www.earningswhispers.com/article/FFBC/20760
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-02 | |
| Sep-25 | |
| Sep-15 | |
| Jul-22 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-21 | |
| Jul-21 | |
| Jul-01 | |
| Jun-08 |
