HF Sinclair's Blowout Beat Rests Partly On A $600 Million Non-Cash Waiver, As Investors Turn Cautious Despite A Credible Tight-Market Story
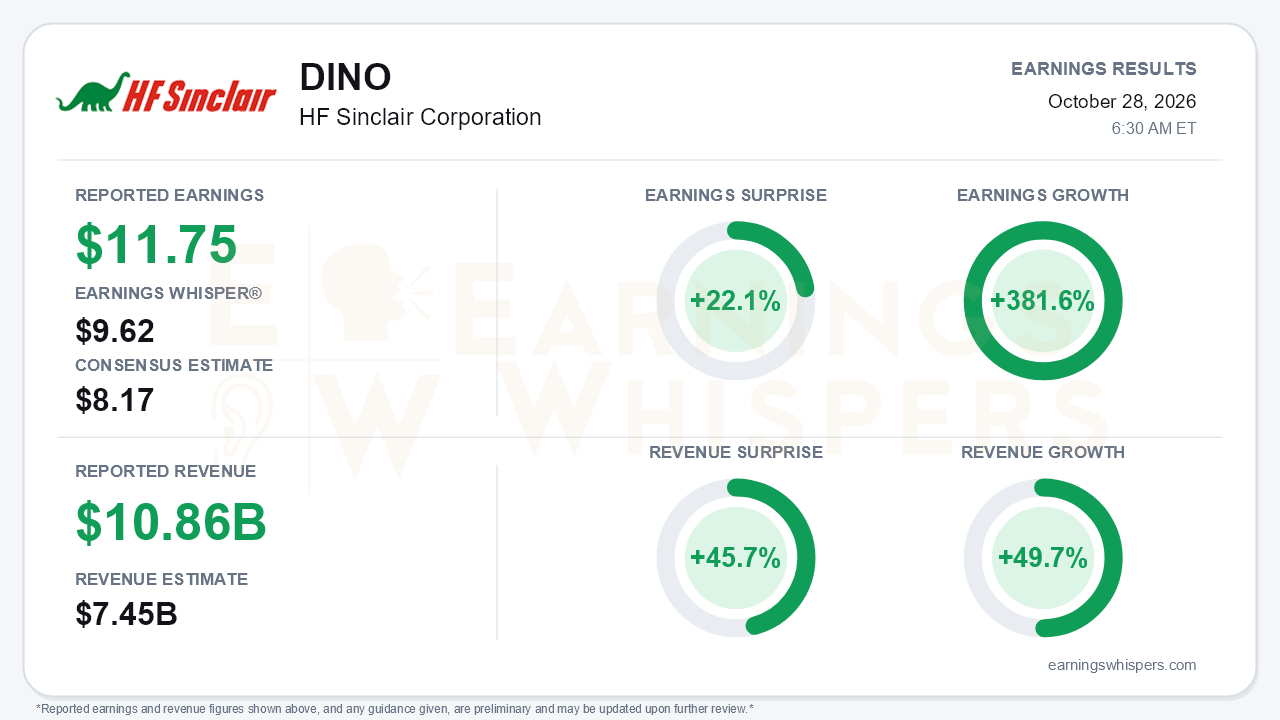
HF Sinclair delivered the kind of quarter refiners get only a few times a cycle. Adjusted earnings were $11.75 per share, against a $8.17 consensus and a $9.62 Earnings Whisper number, a 22.1% beat. Earnings grew 381.6% year over year, and revenue of $10.857 billion rose 49.7%, beating the $7.45 billion consensus by 45.7%. The progression is just as striking: adjusted EPS climbed from $0.69 in Q1 to $5.31 in Q2 and then $11.75, and adjusted EBITDA roughly doubled from Q2 to $2.98 billion. The central tension is that a meaningful slice of the beat came from a roughly $600 million small refinery exemption (SRE) benefit. That benefit is non-cash this year, and management itself concedes that margins will normalize.
The quality of the beat deserves scrutiny. Refining Adjusted EBITDA reached $2.58 billion, up from $661 million a year ago. The adjusted refinery gross margin hit $54.22 per barrel versus $19.16, which the release attributes to tight transportation-fuel supply, elevated cracks and the EPA RINs waivers. Strip out the SRE and refining still earned about $2 billion, and management put capture at roughly 105% excluding the waiver, a level it calls structural. The cash flow statement shows the non-cash element. Operating cash flow of $1.78 billion trailed GAAP net income of $2.02 billion. GAAP EPS was $11.38, lower than the adjusted figure because of $109 million in pre-tax Mississauga retirement charges in Lubricants & Specialties.
Beneath the headline, operations were softer than the margins suggest. Crude charge fell to 614,060 BPD from 639,050 BPD, and Mid-Continent utilization dropped to 96.3% from 107.8% during the El Dorado turnaround. Refining operating expense per throughput barrel jumped to $9.18 from $7.12, and management no longer commits to its $7.25 per barrel target. Several smaller segments rolled over sequentially:
- Renewables Adjusted EBITDA slid to $109 million from $123 million in Q2 and $133 million in Q1.
- Midstream fell to $101 million from $112 million.
- Lubricants eased to $174 million from $207 million, though that is still more than double the year-ago $78 million.
Marketing was the clean volume story. Branded gallons reached 420 million, up from 387 million in Q2 and 325 million in Q1.
The call preserved a credible forward narrative. Management extended its tight-market view to roughly 2028, from 2027 at the Q2 call. It also noted that WCS heavy-crude differentials have widened to $25-30, versus about $14 cited in Q1, and expects them to stay wide through 2027. That matters because the El Dorado vacuum furnace project is finishing and should add 10,000 BPD of heavy crude capacity, which management guides to a $25-30 million EBITDA uplift.
Steve Ledbetter was named permanent CEO effective January 1, 2027, ending leadership uncertainty that dated to late 2025. The company also took an equity stake in the Phillips 66/Kinder Morgan Western Gateway pipeline, and the lubricants spin remains on track for mid-to-late 2027. Capital returns accelerated to $572 million, up from $265 million in Q2, including $479 million of buybacks. Management reiterated a 50% payout for the year, and the dividend is now $0.525. Cash of $3.33 billion against $2.77 billion of debt leaves HF Sinclair in a net cash position.
Bears have legitimate ammunition, however. The Westline Connect FID has slipped again, from mid-2026 to end-2026 and now Q1 2027. Q4 crude guidance of 560-600 kbpd is below the prior quarter's 590-620 range. 2026 capex was raised to about $725 million sustaining plus $150 million growth, with a further step-up likely in 2027. Management also flagged a potential resumption of Chinese product exports as a wildcard for margins.
The market setup is more complicated than the surprise implies. Shares stood at $114.21 heading into the report, up 24.7% since the post-Q2 open and 47.7% above the 200-day moving average. They had, however, already retreated 11.7% from a 52-week high of $129.37 set on October 14. Investor sentiment moved the other way, slipping from a slightly positive 0.06 to a mildly negative -0.16. That is a notable cooling for a stock riding a historic margin run, and it suggests investors are weighing peak-earnings risk more heavily than the beat itself. Earnings Whispers trend readings remain mostly positive, with sequential growth neutral.
The bottom line is that HF Sinclair posted a genuinely exceptional quarter, with strong ex-SRE capture, surging cash returns and a fortress balance sheet. But roughly $600 million of the refining result was a non-cash regulatory windfall, opex discipline slipped, and management is openly guiding toward normalization. With the stock near cycle highs and sentiment souring, the debate has shifted from how strong earnings are to how durable they will be.
Read our earnings preview for HF Sinclair Corporation: https://www.earningswhispers.com/article/DINO/20838
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-21 | |
| Oct-06 | |
| Sep-28 | |
| Sep-24 | |
| Sep-22 | |
| Sep-19 | |
| Sep-16 | |
| Aug-25 | |
| Aug-18 | |
| Aug-12 | |
| Aug-11 |
An Oil Refiner That Fled California Is Back-With a Giant Pipeline From Texas
DINO
The Wall Street Journal
|
